Marcos Gil, REALTOR® · Keller Williams Commonwealth

Brokered by

The Journal

  • Buying Land With Septic in Kentucky: What to Check

    Buying Land With Septic in Kentucky: What to Check

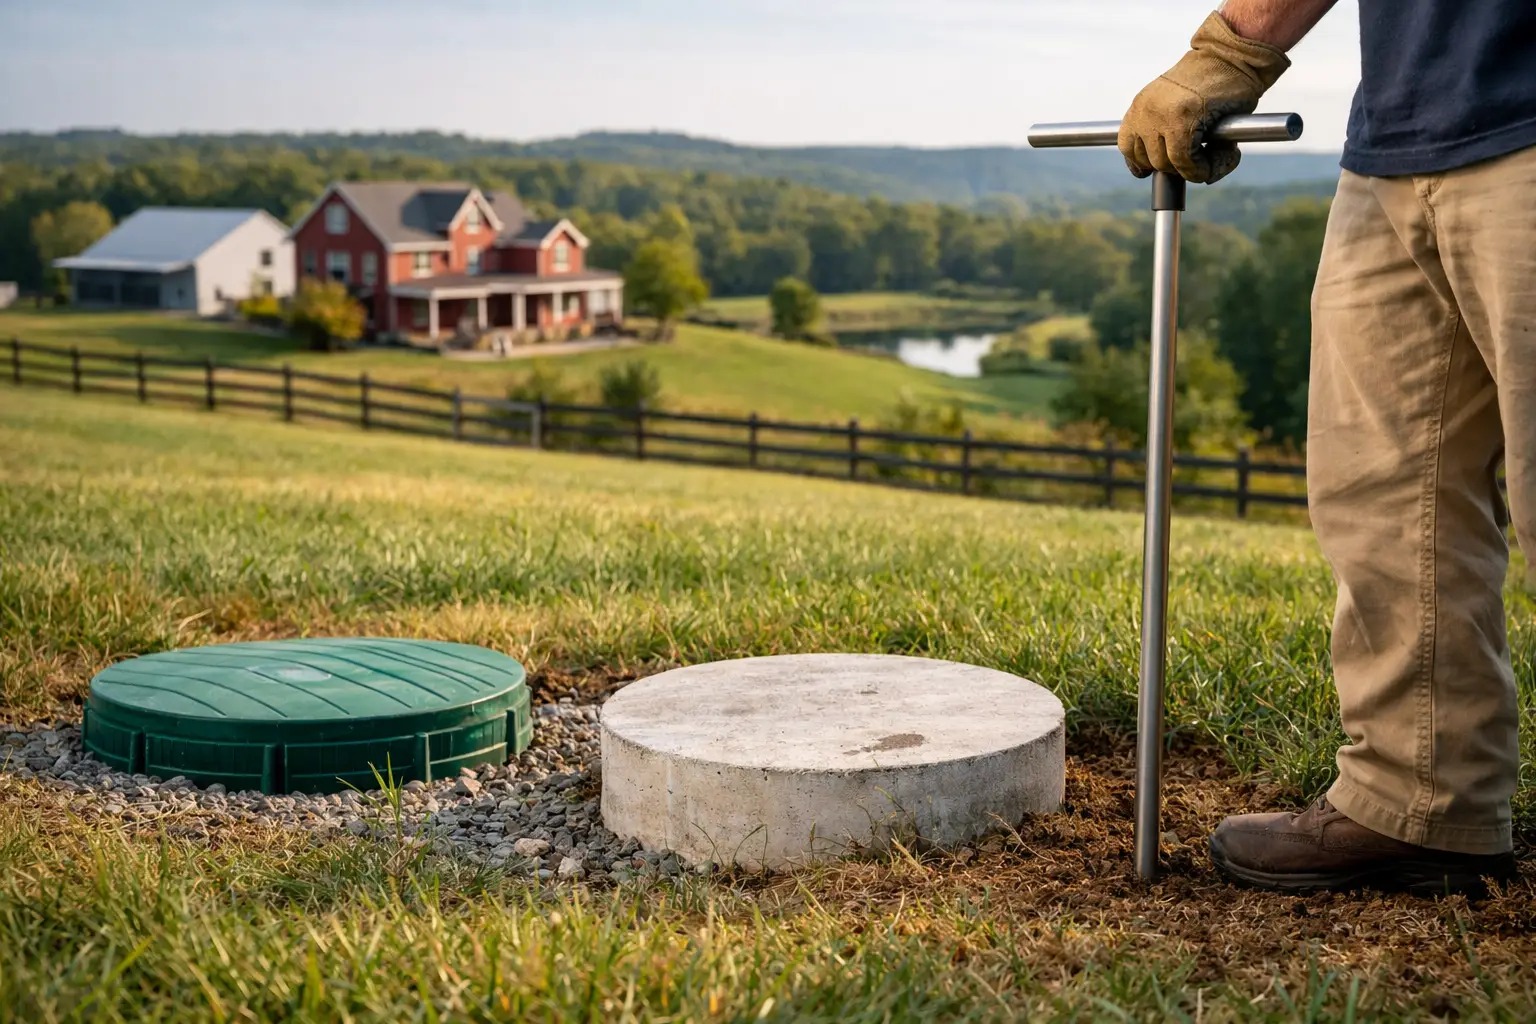
    A beautiful tract can fail the most basic test of ownership: whether it can legally and reliably handle wastewater. That is the central risk in buying land with septic Kentucky buyers should understand before they become attached to the view, the creek frontage, or the promise of privacy. In Central and Eastern Kentucky, usable acreage is not the same thing as buildable acreage, and buildable acreage is not automatically septic-suitable acreage.

    The disciplined order is simple: sewer first, always. If public sewer is available, confirm the actual connection point, capacity, extension requirements, tap fees, and whether the property can physically reach it. If it is not, septic due diligence needs to happen early enough to influence price, contract terms, and the decision to proceed at all.

    Why Septic Changes a Kentucky Land Purchase

    A septic system is not just a tank buried in the yard. It is a permitted wastewater treatment system tied to the property’s soils, slope, drainage, proposed home size, water source, and site plan. A parcel can have ten, fifty, or one hundred acres and still offer only a narrow area where a residence and onsite sewage system can be approved.

    That distinction matters across the Lexington-Richmond-Red River Gorge corridor. Rolling terrain, shallow bedrock, wet-weather drainage, restrictive soil conditions, flood-prone ground, and irregularly shaped tracts can all limit the feasible building envelope. On a wooded Gorge-area parcel, the obvious cabin site may not be the site that works for septic. On a farm outside Richmond, the pasture nearest the road may be ideal for access but unsuitable for a leach field.

    A listing phrase such as “septic approved,” “perc tested,” or “septic on site” should begin a document request, not end the analysis. Ask what was approved, when, for how many bedrooms, for which exact location, and whether the approval remains usable for the home you intend to build.

    Start With Sewer Availability and the Legal Record

    Before discussing tank condition or soil tests, establish whether the property is served by public sewer, can be served by public sewer, or must rely on an onsite system. An agent, seller, or neighbor may use “sewer nearby” loosely. Nearby is not connected, and a line across the road does not necessarily mean a practical or affordable connection.

    For an existing septic system, request the septic permit, site evaluation, installation record or as-built drawing if available, pumping and maintenance receipts, repair invoices, and any records of prior failure. These documents should be sourced, dated, and interpreted. A permit from decades ago can still be useful, but it does not confirm present performance or establish that an addition, guest house, finished basement bedroom, or short-term rental use will be supported.

    For vacant land, ask the local health department what records exist for the parcel and whether a new site evaluation will be required. Kentucky’s onsite sewage process is administered locally, so procedures and record availability can vary by county. A soil and site evaluation – often casually called a perc test – is not something to assume transfers from one lot configuration or building plan to another.

    If the seller cannot produce a permit or clear record, that is not automatically a deal-breaker. It is, however, a reason to price the uncertainty correctly and make the offer contingent on satisfactory septic and site approval.

    Existing Septic Systems Need More Than a Walkover

    A green lawn, no odor, and drains that appear to work during a brief showing are not evidence that a septic system is sound. Many systems reveal trouble only under sustained use, heavy rain, or when a tank is overdue for pumping.

    Hire a qualified septic professional to inspect the system during the due-diligence period. The inspection should identify the tank type and approximate size, assess accessible components, locate the drainfield where possible, evaluate signs of surfacing or backup, and review whether the system appears appropriately matched to the home. A separate plumbing inspection may also be warranted, particularly for older rural homes, cabins, and properties with additions.

    The most consequential question is often bedroom count. Septic approvals are generally tied to design flow, commonly connected to the approved number of bedrooms rather than the number of people currently occupying a home. If a three-bedroom property is marketed with a fourth sleeping room, bunk room, or finished lower level, buyers should not assume the septic approval supports that use.

    This deserves special attention for Red River Gorge cabins and investment properties. A property that performs acceptably as a lightly used second home may face materially different demand as a high-turnover short-term rental. Rental income projections should never be built on occupancy assumptions that outrun wastewater capacity.

    The Reserve Area Is Part of the Property

    Where a replacement or reserve area is required, it is not spare land to casually repurpose. It may be essential to the property’s long-term usability if the original drainfield fails. Parking pads, barns, pools, retaining walls, driveways, heavy equipment, and deep-rooted landscaping can all create problems when placed over septic components or an intended reserve area.

    This is where survey review and site planning become practical, not academic. Confirm the boundaries, easements, proposed driveway, utility route, well location if applicable, house footprint, drainfield, and reserve area together. On a narrow or steep parcel, each decision competes for the same usable ground.

    Buyers also need to understand that a future lot split can change the equation. A tract that works as one homesite may not support a second residence, family compound, or additional cabin. If development potential is part of the value proposition, investigate septic feasibility before assigning a premium to hypothetical density.

    Wells, Water, Drainage, and Topography Belong in the Same Review

    Septic is one part of a larger site system. If the property will use a private well, the well and septic layout must work together with required separation distances and the actual terrain. The proposed well location should not be treated as a pin dropped anywhere on a survey.

    Water management matters just as much. Walk the parcel after rain if possible. Look for drainage swales, wet spots, springs, sinkholes, pond overflow paths, and evidence of standing water. In parts of Eastern Kentucky, slope and rock can turn an apparently straightforward homesite into a much more engineered project. In low-lying areas, flood conditions and saturated soils can make conventional expectations unrealistic.

    The trade-off is not always a rejection of the property. Some sites can be improved with an alternative system, grading, or a more carefully located home. But those solutions can be expensive, may require specialized design and approval, and should be understood before the inspection period expires. “It can probably be worked out” is not a budget.

    Write the Contract Around the Real Risk

    For land or rural homes, a generic inspection contingency can be too vague. The purchase agreement should give the buyer enough time and authority to obtain septic records, inspect an existing system, conduct any needed soil or site evaluation, confirm access to utilities, and evaluate well and drainage conditions.

    The exact structure depends on the property. A buyer purchasing an older farmhouse may need a septic inspection, pumping history, and a repair estimate. A buyer purchasing raw acreage may need written confirmation that a homesite and onsite sewage system can be approved for the intended use. A buyer acquiring land for a cabin portfolio may need clarity on how many separate systems and dwellings are realistically permissible.

    Keep the economics visible. If the system is near the end of its useful life, that does not necessarily mean walk away. It may mean adjusting the purchase price, requesting a credit where appropriate, reserving funds, or choosing a property whose location and land quality justify the future capital expense. What matters is knowing whether the issue is a manageable improvement or a constraint that limits the entire plan.

    A Better Way to Look at Rural Value

    Kentucky land is often marketed through emotion: the ridge view, the horse pasture, the quiet road, the proximity to Lexington or the Gorge. Those qualities have real value. Yet the infrastructure underneath them determines whether that value can be used, financed, insured, rented, or resold without friction.

    The best rural purchase is not necessarily the parcel with the most acreage or the newest-looking cabin. It is the one where access, water, wastewater, boundaries, terrain, and intended use align on paper as well as they do from the road. Ask the septic questions early, retain the right professionals, and let the answers shape the offer before the land starts shaping your expectations.
  • Central Kentucky Market Pulse — Week of August 15, 2026

    One agent, one weekly read on the corridor — and this week the numbers come straight from the Bluegrass REALTORS® MLS rather than a third-party estimate. The short version: both Lexington and Richmond are still seller’s markets, prices are up year over year in both, and the real difference between them is not price. It is speed.

    Lexington and Richmond, side by side

    MeasureLexington (Fayette Co.)Richmond & Berea (Madison Co.)
    Active listings645337
    Months of supply2.1 months3.1 months
    Average days on market23.950.1
    Median sold price, July$372,500$322,000
    Year-over-year change+5.7%+4.2%
    Median asking price$414,900$330,500
    New listings, last 7 days7627

    Source: Bluegrass REALTORS® MLS via FlexMLS. Monthly statistics reflect the last complete month, July 2026; new-listing counts are as of August 15, 2026. Months of supply is calculated as active inventory divided by the trailing twelve-month average of closed sales. Deemed reliable but not guaranteed.

    What this means if you are buying

    In Lexington, you are competing on the clock. An average of 23.9 days on market means a well-priced home in a desirable pocket is spoken for inside of a month — often inside of a week. With 2.1 months of supply, you need financing lined up and a decision process that can move in days, not weekends. Browsing without pre-approval in this market is how buyers lose three houses before they get serious.

    In Richmond, you have room to think. At 50.1 days — more than double Lexington’s pace — and 3.1 months of supply, Madison County gives buyers something Fayette County does not: time to walk a property twice, get an inspection scheduled without panic, and negotiate on more than price. And the entry point is roughly $50,500 lower at the median. If you are searching homes for sale in Richmond KY, that combination is the whole argument for looking south of Fayette County.

    What this means if you are selling

    Both markets moved up year over year — Lexington’s median sold price is up 5.7% and Madison County’s up 4.2%. But notice the gap between asking and selling in each market. Lexington’s median asking price is $414,900 against a $372,500 median sale; Madison County’s spread is narrower. Inventory that lingers is usually inventory that was priced against the asking column instead of the selling column. A valuation grounded in what actually closed is worth more than an optimistic list price you will spend two months walking back.

    One more signal worth watching: Lexington’s active inventory bottomed at 531 listings in March and has climbed to 645 since — a 21.5% increase off the floor. That is normal summer seasonality, not a downturn. But it does mean sellers who list in the fall will face more competition than sellers who listed in the spring did.

    Common Questions

    Is the Central Kentucky market slowing down?

    Not by these numbers. Both counties show year-over-year price gains and both remain under four months of supply, which is seller-favorable territory. Inventory is up from its March low in Lexington, but it is still slightly below where it stood a year ago. That is a market normalizing from extreme tightness, not one turning over.

    Why is Richmond so much slower than Lexington if prices are rising in both?

    Different buyer pools. Fayette County draws a large relocation and university-driven demand base concentrated in a compact geography, so well-priced homes clear fast. Madison County covers more ground with a more local buyer base. Slower is not weaker — Madison County still closed 155 sales in July against 337 active listings.

    How is months of supply calculated?

    Active listings divided by the trailing twelve-month average of monthly closed sales. We use a twelve-month average rather than the current month because summer months flatter the ratio and would make both markets look tighter than they are.

    Thinking about a move anywhere on the corridor? Selling, buying, or you just want the numbers for your street — call or text.

    By Marcos Gil, REALTOR® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209.

  • Is a Red River Gorge Cabin Investment Worth It?

    Is a Red River Gorge Cabin Investment Worth It?

    A Red River Gorge cabin investment is rarely won or lost on the nightly rate shown in an online search. It is won in the less glamorous details: whether guests can reach the property after a hard rain, whether the septic system matches the sleeping capacity being marketed, whether insurance is available at a workable premium, and whether the gross revenue estimate still makes sense after management, maintenance, utilities, and reserves.

    The Gorge has genuine demand. Climbers, hikers, wedding guests, families, and Lexington-area buyers seeking a quick reset continue to support a distinctive lodging market. But it is not a uniform market, and a cabin with a pretty view is not automatically a sound investment. The better question is whether a specific property can operate reliably, legally, and profitably in its exact location.

    What Makes a Red River Gorge Cabin Investment Different

    Red River Gorge cabins trade on experience. Guests may pay a premium for a hot tub, fire pit, wooded privacy, architectural character, pet-friendly policies, proximity to trailheads, or a view that feels removed from ordinary life. A well-positioned cabin near Slade can attract a different guest than a larger, more secluded property farther into Wolfe, Powell, Lee, Menifee, or Estill County.

    That distinction matters because location affects more than demand. It changes drive times, road maintenance, cellular service, emergency access, trash service, utility reliability, and the practical cost of turning a rental between stays. A property can be technically close to the Gorge yet feel inconvenient to the guest who arrives after dark on an unfamiliar two-lane road.

    Unlike a conventional long-term rental, this asset is an operating business tied to a real property. The buyer is underwriting land, improvements, furnishings, local regulations, guest expectations, and an ongoing maintenance program at the same time. Gross bookings are only one input.

    Start With Revenue, Then Stress-Test It

    A credible income estimate should begin with comparable cabins, not broad regional averages. Compare bedroom count, guest capacity, finish level, amenities, road access, proximity to Slade and major recreation draws, and whether the property has meaningful differentiation. A three-bedroom cabin with a hot tub and polished interiors may compete in a different rate band than a basic three-bedroom on the same road.

    Past booking statements can be useful, but they are not proof of future performance. Ask how the revenue was generated. Was the owner actively managing pricing? Did the property benefit from unusually strong reviews, a recent renovation, or a one-time event cycle? Were owner stays blocked during high-demand weekends? Did the reported figure include cleaning fees or taxes that do not belong in operating revenue?

    A conservative underwriting model should separate gross rental revenue from the money actually available to the owner. Account for management fees, platform fees, cleaning coordination, laundry, consumables, electric, internet, propane, water, septic service, pest control, snow or road work where applicable, repairs, furnishings, insurance, property taxes, and a capital reserve.

    Cabins are hard on systems. Hot tubs need regular attention. HVAC equipment works through Kentucky humidity and winter cold. Decks, stairs, roofs, retaining walls, and gravel drives all require recurring capital. An owner who models only mortgage payment, taxes, and a cleaning fee is not modeling the asset.

    Seasonality Is a Planning Issue, Not a Footnote

    The Gorge has multiple demand drivers, which is an advantage. Climbing and hiking seasons can be strong, weekends carry disproportionate weight, and fall can produce exceptional demand. Still, weekday occupancy and shoulder-season performance often decide whether an investment has sufficient margin.

    Build a monthly model rather than applying one annual occupancy percentage. Then test it against a lower-rate, lower-occupancy case. If the property only works at an optimistic average daily rate and near-perfect weekend conversion, the acquisition price may be too aggressive or the operating plan too thin.

    Sewer First, Always: Utilities and Site Due Diligence

    For rural Kentucky cabins, sewer first, always. Many properties rely on septic systems, and the distinction between bedroom count, septic capacity, and advertised guest count can be consequential. A listing may describe bunks, lofts, or sleeping rooms that do not align with the system’s permitted design. That creates operational, regulatory, and resale risk.

    Obtain the available septic records, identify the system type and location, and understand its service history. Ask where replacement area may exist if the current system fails. An inspection should go beyond a casual look at the yard. Buyers should also verify the water source, water pressure, filtration needs, well records if applicable, and any shared-water or private-road agreements.

    Roads deserve the same seriousness. Who owns and maintains the approach? Is there a recorded easement? Can a standard guest vehicle reach the cabin in wet weather? Will a propane truck, trash hauler, cleaner, emergency vehicle, or repair contractor have practical access? A steep, narrow drive can be part of the cabin experience, but it may also narrow the guest pool and raise operating costs.

    The property condition review should include roof age, drainage, foundation movement, deck structure, retaining walls, tree risk, moisture control, HVAC, electrical capacity, internet options, and cell coverage. In a remote setting, a small deferred-maintenance issue can become expensive because service calls take longer and contractor availability can be limited.

    Regulations, Restrictions, and the Cost of Being Wrong

    Short-term rental rules are local and can change. County requirements, building-code considerations, occupancy standards, lodging taxes, business licensing, deed restrictions, homeowners association rules, and insurance requirements should be verified for the specific parcel before a buyer removes contingencies. Do not rely on a seller’s statement that a cabin has “always been rented.” Prior use is not a complete legal or operational analysis.

    If the property sits in a development, read every recorded restriction and amendment. Some communities regulate rental duration, parking, signage, noise, exterior changes, or amenity use. Others place maintenance obligations on owners that affect annual expenses. The same is true for private roads and shared drives: the agreement may be more important than the view.

    Insurance deserves early attention. Wood construction, remote fire response, steep drives, water features, hot tubs, and rental use can affect availability, deductibles, exclusions, and premiums. Request quotes before finalizing the financial model, not after inspection. A low initial insurance estimate can make an otherwise marginal deal appear viable.

    Buy the Right Cabin, Not the Loudest Listing

    The strongest investment candidates generally have a clear guest proposition and fewer hidden operating problems. That does not always mean the newest or largest cabin. A modest property with excellent access, reliable systems, a well-designed outdoor area, and a manageable maintenance profile may outperform a more dramatic cabin that is difficult to reach and expensive to keep guest-ready.

    Consider who the intended guest is. A two-person retreat can command a healthy rate with privacy, design, and a quality hot tub. A family-oriented cabin may need usable bedrooms, safe outdoor space, durable furnishings, and dependable internet. A group property requires adequate parking, septic capacity, noise management, and enough common space that the sleeping count feels credible rather than crowded.

    This is also where buyer goals matter. Some owners want personal use and will accept lower yield in exchange for protected weekends. Others need income consistency, a 1031 exchange replacement property, or a business that can support professional management. Neither approach is wrong, but the underwriting should match the purpose. A personal retreat should not be priced as though every premium weekend will remain available for rental.

    An Exit Strategy Should Be Present at Purchase

    Cabin values can be influenced by lifestyle demand, construction quality, acreage, views, road conditions, and income history. But short-term rental revenue is not guaranteed to transfer neatly to the next owner. A buyer should be able to explain the property’s appeal without relying entirely on one year of bookings.

    Think through the likely resale audience. Is the next buyer an investor, a second-home owner, a local household, or someone seeking land and privacy? A cabin with broad appeal, documented improvements, clean records, and well-maintained systems is easier to position when market conditions change. Keep invoices, permits, septic records, service logs, and before-and-after documentation. In a rural transaction, orderly records can materially improve buyer confidence.

    A disciplined Red River Gorge cabin purchase is not about finding a fantasy number on a revenue calculator. It is about paying the right price for a property whose access, systems, regulations, guest appeal, and operating costs have been examined in writing. The cabin should still make sense after the view wears off and the first repair invoice arrives.

  • VA Home Buying Kentucky Guide for Smart Buyers

    VA Home Buying Kentucky Guide for Smart Buyers

    A VA loan can put a Kentucky home within reach with no required down payment, but the financing is only one part of the decision. This VA home buying Kentucky guide focuses on the questions that tend to matter most in Central and Eastern Kentucky: what you can actually afford, whether the house will meet VA property standards, and where local property conditions can complicate an otherwise strong purchase.

    For buyers considering Lexington, Richmond, Berea, Winchester, Georgetown, or communities near the Red River Gorge, the right strategy is not simply to find a seller willing to accept VA financing. It is to build an offer around verified financing, sound property condition, and a location that still works after the excitement of moving has passed.

    Start With Eligibility, Entitlement, and a Real Preapproval

    VA-backed mortgages are available to eligible veterans, active-duty service members, certain National Guard and Reserve members, and qualifying surviving spouses. The starting document is a Certificate of Eligibility, or COE, which confirms the entitlement available for a VA loan. A lender can often retrieve it electronically, although some files require additional documentation and time.

    Do not confuse a prequalification with a meaningful preapproval. A prequalification is often an early estimate based on unverified numbers. A serious preapproval reviews income, assets, credit, debts, and the intended occupancy of the property. It also addresses whether you have full entitlement available, whether a prior VA loan affects your purchasing power, and how the funding fee applies to your situation.

    The VA does not set a universal minimum credit score, but individual lenders do. Lender standards, rate pricing, residual-income calculations, and debt-to-income tolerances vary. That is why two lenders can give the same buyer materially different answers. Compare the loan estimate, not just the advertised rate. Ask about lender fees, discount points, the funding fee, estimated cash to close, and the cost of any rate lock.

    A zero-down loan does not mean a zero-cash transaction. Inspection fees, earnest money, appraisal costs, prepaid taxes and insurance, and closing items can still require funds. Seller-paid concessions may help, subject to loan rules and negotiation, but they should never be assumed before the property and contract terms are known.

    Set the Budget Around Ownership, Not Approval

    Kentucky can offer more house for the money than many coastal or major metro markets, but ownership costs change sharply by property type and location. A newer home in a Lexington subdivision may have predictable utilities and a homeowners association. A farmhouse outside Richmond or a cabin near Campton may bring acreage, private roads, septic systems, wells, drainage obligations, and more variable insurance costs.

    Property taxes also need a local reading. A home in Fayette County, Madison County, Clark County, or a smaller Eastern Kentucky jurisdiction can carry different assessments and taxing districts. If you are relocating, ask for the current tax bill, then understand that a future assessment or exemption status may change the figure. The listing portal estimate is a starting point, not a budget.

    Insurance deserves equal attention. Coverage for a conventional in-town home is usually straightforward, while a wooded cabin, a property with a long private drive, or a house near a flood-prone area may require more careful underwriting. Obtain an insurance quote early, particularly if a property has a metal roof, older systems, a detached structure, a creek, or a history of claims.

    Choose a Kentucky Location With Your Daily Life in Mind

    For military-connected buyers near Blue Grass Army Depot, Richmond and much of Madison County can make practical sense, while Lexington may appeal to households seeking broader employment access, medical care, restaurants, and university-adjacent neighborhoods. The commute trade-off is real. A lower purchase price farther east can be attractive until fuel, drive time, and weather make the daily route less appealing.

    A property near the Red River Gorge can offer privacy and outdoor access, but it is not simply a less expensive version of Lexington. Internet service, road maintenance, emergency access, utility reliability, topography, and short-term-rental activity can affect both daily use and future resale. The same is true for acreage throughout the corridor. A beautiful view does not answer whether the driveway is shared, the parcel has a recorded easement, or the land has a usable building site.

    Before narrowing your search, decide what cannot be compromised: commute time, school preferences, walkability, acreage, bedroom count, or proximity to services. Then separate preferences from requirements. This prevents buyers from stretching for a property that looks exceptional online but creates an expensive operational burden.

    The VA Appraisal Is Not a Substitute for an Inspection

    The VA appraisal has two jobs. It establishes an opinion of value for the lender and checks whether the property appears to meet the VA’s Minimum Property Requirements. The appraisal is not a whole-house inspection, and it should not be treated as one.

    In practice, VA appraisers may flag conditions that affect safety, sanitation, structural soundness, or marketability. Peeling paint on an older home, a roof near the end of its useful life, exposed wiring, damaged handrails, inadequate heating, water intrusion, or an unsafe deck can become issues that require correction before closing. The exact outcome depends on the property and appraiser, but buyers should plan for this possibility rather than presenting it as a surprise to the seller.

    An independent inspection remains essential. In Central and Eastern Kentucky, pay particular attention to roof age, crawlspace moisture, foundation movement, grading, gutters, electrical panels, plumbing supply lines, HVAC age, and evidence of prior repairs. For rural homes, sewer first, always. If the property uses a septic system, understand its age, capacity, maintenance history, and whether any additions or guest spaces were permitted to rely on it.

    A well should be evaluated for flow and water quality when appropriate. If there is a private road, establish who maintains it, how costs are allocated, and whether the access agreement is recorded. These are not cosmetic details. They affect financing, insurance, resale, and the practical use of the property.

    Making a Competitive VA Offer Without Giving Up Protection

    A VA offer can be competitive when it is clean, well-supported, and written for the specific property. The financing type alone does not make an offer weak. What sellers notice is uncertainty: vague lender communication, an unrealistic closing timeline, excessive contingencies, or a buyer who appears unprepared for appraisal and inspection findings.

    A strong offer starts with a lender who can speak directly to the listing side and document the buyer’s readiness. It should include an earnest-money amount appropriate to the price point and local norms, a workable closing date, and clearly written inspection and financing terms. If competition is intense, the decision to offer above list price should be grounded in recent comparable sales, not fear of missing out.

    The VA amendatory clause protects the buyer from being obligated to proceed if the appraised value is below the contract price. That protection matters. It does not prevent a buyer from renegotiating, bringing funds to cover a gap if permitted and financially sensible, or walking away when the numbers no longer work. The right choice depends on the property, the appraisal support, your available cash, and how long you expect to own the home.

    Avoid waiving inspections simply to imitate a cash buyer. A more disciplined approach is to shorten a reasonable inspection period, focus negotiations on material defects, and obtain specialist opinions when the initial inspection points to roofing, structural, electrical, septic, chimney, or drainage concerns.

    Plan the Closing Window Before You Go Under Contract

    A conventional VA purchase often closes within a standard contract period when the lender file, appraisal, title work, and property condition are all moving properly. Delays tend to arise from incomplete borrower documentation, appraisal repairs, title issues, employment changes, or rural-property questions that should have been raised earlier.

    Keep financial activity quiet after preapproval. Do not open new credit accounts, finance furniture, change jobs without discussing it with the lender, or move large undocumented deposits into your accounts. Save every requested document promptly. Underwriting is evidence-based, and last-minute explanations can slow a file that was otherwise on track.

    For out-of-area buyers, build a local due-diligence plan before travel. Have the inspection scheduled quickly, ask for video documentation where useful, and make sure the property boundaries, access, utility arrangements, and major repair history are sourced, dated, and interpreted before deadlines expire. A good transaction is not just quietly done. It is built on facts that still hold up after closing.

    The best VA purchase is rarely the house with the most dramatic first impression. It is the one whose price, condition, financing, and location make sense together – including on a wet Kentucky morning, during a long commute, or when the first repair bill arrives.

  • Central Kentucky Market Pulse — Mid-August 2026

    One agent, one weekly read on the corridor — Lexington to Richmond to the edge of the Gorge. Here is where the market data lands this week, and what it means if you are on either side of a transaction.

    The numbers this week

    MarketAvg. property pricePrice / sq ftDays on marketEst. traditional rent
    Lexington$490,572$21570$1,730/mo
    Richmond$399,005$18775$2,147/mo
    Winchester$380,341$183123$2,068/mo
    Beattyville$234,262$203155$1,501/mo

    Source: Mashvisor market data for Kentucky, pulled August 13, 2026. Occupancy, nightly-rate, and rental figures are model estimates — useful for direction, never for underwriting a specific property. Deemed reliable but not guaranteed.

    Horse farm outside Lexington, Kentucky — board fences and bluegrass pasture
    Board fences and bluegrass — the landscape behind the numbers

    What it means this week

    Lexington keeps its premium. At roughly $215 per square foot against Richmond’s $187 and Winchester’s $183, the price gap between Fayette County and its neighbors remains the corridor’s defining fact — and the reason commuter-belt buying stays active. If you are weighing the trade, start with the community guides.

    Supply is coming to the rental side. Developer Hillpointe announced its first Kentucky projects this month — two Central Kentucky communities totaling 868 new residences in Lexington and Nicholasville (The Lane Report, Aug 2026). More attainable rental inventory changes the math for small landlords over the next two years.

    Richmond’s rent-to-price ratio is quietly the corridor’s strongest. An estimated average rent near $2,100 on a ~$399k average price is a healthier ratio than Lexington’s — one reason investor interest keeps drifting down I-75. Selling into that demand? Start with a free valuation.

    Common Questions

    Is now a good time to buy in the corridor?

    Market time in the 70–75 day range means neither a frenzy nor a freeze: buyers can negotiate without racing, sellers still move with correct pricing. Your specific answer depends on rate, timeline, and town — the buying guide at /buying/ walks the decision through honestly.

    Why do Beattyville numbers look so different?

    Smaller market, fewer transactions, longer market times — averages swing more. It remains the corridor’s lowest entry point by a wide margin, which is exactly why we track it alongside the metro markets.

    Thinking about a move anywhere on the corridor? Selling, buying, or just want the numbers for your street — call or text.

    By Marcos Gil, REALTOR® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209.

  • Moving to Lexington Kentucky Guide for Buyers

    Moving to Lexington Kentucky Guide for Buyers

    Lexington can look deceptively simple from a distance: a university city, horse country, a lively downtown, and neighborhoods that appear close together on a map. A useful moving to Lexington Kentucky guide begins with the fact that daily life can change materially from one side of town to another. Your commute, lot type, school assignment, utility access, and tolerance for traffic around New Circle Road may matter more than a subdivision’s marketing language.

    For relocating households, the strongest purchase is rarely the one with the prettiest listing photos. It is the property that fits the way you will actually use Lexington – on a Tuesday morning drive, after a heavy rain, during Keeneland season, and when an older home needs its first repair.

    Start With How You Will Use Lexington

    Lexington is compact compared with many major metros, but it is not one market. A physician working near UK HealthCare, a family commuting to the Blue Grass Army Depot, and a buyer splitting time between Lexington and the Red River Gorge will reasonably prioritize different locations.

    Begin with the destinations that will shape your week: work, school, airport access, medical care, family, recreation, and regular errands. Then test those routes at the times you would actually drive them. A nominal 15-minute commute can behave differently when you are crossing New Circle Road, approaching downtown, or traveling near the University of Kentucky during the academic year.

    Lexington’s central neighborhoods appeal to buyers who want character, mature trees, walkable pockets, and a shorter trip to downtown or UK. Areas such as Chevy Chase, Ashland Park, Kenwick, and Southland offer distinct housing stock and lifestyle patterns. They can also bring older systems, narrower driveways, more varied floor plans, and renovation histories that require a closer read.

    Outer neighborhoods and newer development areas can provide different advantages: newer construction, larger garages, more predictable layouts, and proximity to specific employment corridors. Hamburg and the east side offer commercial convenience and access toward Winchester. Beaumont, the south side, and parts of the west side can suit buyers who value neighborhood amenities and easier access to particular routes. The right choice depends less on a broad ranking and more on where your life happens.

    Housing Costs Are More Than the Purchase Price

    Buyers relocating from a higher-cost market may see Lexington as affordable. That can be true, but affordability is not a license to skip analysis. Desirable homes that are correctly priced, well prepared, and located in tightly held neighborhoods can draw meaningful competition. Meanwhile, a lower asking price may reflect deferred maintenance, an awkward location, flood exposure, a dated mechanical system, or a floor plan with limited resale appeal.

    Build a monthly ownership figure before you fall in love with a house. Include principal and interest, property taxes, homeowners insurance, HOA dues where applicable, utilities, expected maintenance, and any near-term improvements. Older homes may have the architectural detail buyers want, but their carrying costs can be less predictable than those of a newer home.

    If you are moving from a state where property taxes are structured differently, ask for the actual tax history and confirm how an ownership change may affect your estimate. Treat online calculators as starting points, not final underwriting. The same standard applies to square footage, lot size, school information, and renovation claims: sourced, dated, and interpreted.

    Decide What You Will Trade

    Most Lexington buyers make a trade, whether they name it or not. A central location may mean an older home and a smaller lot. A newer house may mean a longer drive to downtown. Acreage on the edge of the county may offer privacy but introduce septic, well, driveway, fencing, and maintenance questions.

    There is no universal answer. The practical question is which compromise will still feel acceptable after the novelty of a new address wears off.

    A Moving to Lexington Kentucky Guide to Neighborhood Fit

    Do not choose a neighborhood based solely on a postal label or a list of popular areas. Lexington’s housing character changes block by block. One street may contain restored historic homes; the next may have rentals, commercial traffic, or a drainage pattern worth investigating.

    For university-affiliated households, central and near-campus locations can reduce commute time and offer access to restaurants, cultural events, and established neighborhoods. For executives and frequent travelers, access to Blue Grass Airport and major routes may carry more weight. Families often want to understand parks, daily errands, school transportation, and how the neighborhood functions beyond an open house on a Saturday afternoon.

    School preferences deserve particular care. School attendance zones can change, and a listing description is not an authoritative source. Verify current assignments directly with the appropriate district and separately evaluate whether the home, route, and household rhythm support your needs. A school name should never substitute for due diligence.

    For buyers who want a horse-country setting without giving up Lexington access, the line between city convenience and rural responsibility deserves attention. Fayette County’s protected rural landscape is part of the region’s appeal, but a property outside the urban service area may operate very differently from an in-town home. Internet service, trash collection, road conditions, easements, fencing obligations, and emergency access all warrant review.

    Inspect the Property, Not the Story

    Lexington has a broad range of housing ages and construction types, from historic properties to recent subdivisions. That range makes inspections especially consequential. A renovated kitchen can coexist with aging supply lines, an original sewer lateral, poor drainage, an undersized electrical panel, or a roof near the end of its service life.

    For older homes, sewer first, always. A sewer scope is a modest step compared with the cost and disruption of repairing a buried line. Pay close attention to drainage as well. Walk the exterior, identify downspout discharge points, look for grading that directs water toward the home, and ask what happens during sustained rain. Basements and crawl spaces should be evaluated for moisture history, not merely whether they look dry on showing day.

    New construction deserves scrutiny too. A new home is not automatically a finished or trouble-free home. Confirm what is included, review builder warranties, understand lot drainage, and inspect the work before closing. In developing areas, ask about future phases, nearby road construction, commercial plans, and HOA authority. The view behind a new house is only permanent if the underlying land use supports that assumption.

    Utility and Land Questions Change Outside Town

    If your Lexington search extends to acreage, farms, or nearby communities, add another layer of diligence. Confirm whether water is public or well-supplied, whether sewer is public or septic, and whether the property has recorded easements or shared drives. For land, understand access before imagining the build site.

    A parcel can be beautiful and still be operationally difficult. Topography, soil conditions, floodplain areas, deed restrictions, utility availability, and road frontage all influence what you can build, finance, insure, and eventually resell. Buyers looking toward Richmond, Madison County, or the Red River Gorge corridor should expect these questions to become more central, not less.

    Plan the Move Around the First 90 Days

    A relocation succeeds when the first few months feel manageable. Before closing, identify your utility providers, insurance requirements, local service professionals, and likely maintenance priorities. If the home is older, reserve time and money for work that is not glamorous: servicing HVAC equipment, cleaning gutters, addressing grading, changing locks, and learning shutoff locations.

    If you are buying from out of state, use the inspection period strategically. Attend inspections when possible, request clear photographs and repair explanations, and distinguish between a safety issue, a maintenance item, and a cosmetic preference. Not every defect is a reason to abandon a home. But unresolved structural, water, sewer, electrical, or access concerns should be understood in dollars and consequences before you proceed.

    Lexington rewards buyers who look past the first impression. The right home may be a brick bungalow near UK, a newer property with room to grow, or a quiet acreage tract beyond the city edge. Choose the one whose location, condition, and long-term costs remain convincing after the listing has faded and the ordinary routines of Kentucky life begin.

    Horse country outside Lexington, Kentucky
    Horse country at the edge of the city — the reason people make the move

    Related guides: Walnut Hill, Lexington KY – Rural-Edge Living · Idle Hour: An Established East Lexington Neighborhood Guide · Griffin Gate, Lexington KY – Golf & Resort Living · Gleneagles, Lexington KY – Neighborhood Guide · Bryant Oak Place, Lexington KY – Neighborhood Guide · Relocating to Kentucky With Horses

  • Pre Listing Home Repairs Checklist for Sellers

    Pre Listing Home Repairs Checklist for Sellers

    A house can show beautifully on Saturday and still lose leverage on Monday when the inspection report arrives. For Kentucky sellers, a pre listing home repairs checklist is less about making every surface new and more about identifying the defects that change a buyer’s confidence, lender eligibility, or willingness to proceed.

    The right preparation is selective. A dated but well-maintained ranch in Lexington may need a different scope than a Richmond home on a crawlspace, a historic property with original windows, or a Red River Gorge cabin marketed to second-home buyers. The objective is not to erase age. It is to establish that the property has been cared for, its major risks are understood, and its asking price reflects its actual condition.

    Start With the Repairs That Can Stop a Sale

    Cosmetic work earns attention because it is visible. Operational defects deserve attention because they can derail a transaction. Before considering paint colors or hardware, address health, safety, water, structural, and major-system concerns.

    Sewer first, always. A sewer scope is a relatively modest early expense compared with a renegotiation after a buyer finds roots, a belly in the line, deteriorated cast iron, or a failed connection. This matters in older Lexington neighborhoods and in rural or semi-rural settings where septic systems, laterals, and drainage conditions require a different level of scrutiny. If a problem exists, a seller can price it deliberately, repair it with documentation, or disclose it clearly. Discovering it under contract is the least favorable version of the same fact.

    Water comes next. Look for active roof leaks, staining at ceilings, failed flashing, damp basements, crawlspace moisture, loose gutters, negative grading, and downspouts that empty beside the foundation. Central Kentucky’s clay soils and heavy rain events make drainage a practical ownership issue, not a cosmetic one. A clean basement with a persistent moisture source is not a clean basement for long.

    Then examine the systems buyers expect to function on day one: HVAC, electrical, plumbing, water heaters, fireplaces, and appliances that will remain. An aging furnace is not automatically a repair. A furnace that does not heat, lacks a service history, or shows a safety concern is different. The same distinction applies to an older roof that has useful life remaining versus a roof with active leaks or missing shingles.

    Pre Listing Home Repairs Checklist: The High-Value Review

    Use this checklist to organize a walk-through before photographs, staging, or launch. It is most useful when each item receives a practical decision: repair, obtain a specialist opinion, disclose, or leave alone and price accordingly.

    • Sewer, septic, and water: Scope the sewer where appropriate; inspect septic components if applicable; correct active leaks; verify water pressure; and address visible corrosion, damaged supply lines, or nonfunctioning fixtures.
    • Roof, gutters, and drainage: Repair active leaks and loose flashing, clear gutters, extend downspouts away from the foundation, correct obvious grading issues, and remove tree limbs contacting the roof.
    • Foundation, basement, and crawlspace: Investigate new or widening cracks, standing water, musty odors, sagging floors, exposed insulation damage, and signs of wood-destroying insects. Do not conceal moisture with fresh paint.
    • Electrical and safety: Repair exposed wiring, inoperative outlets, missing cover plates, loose fixtures, unsafe panels, and nonworking smoke or carbon monoxide detectors. Confirm stair railings and guardrails are secure.
    • Heating, cooling, and ventilation: Service systems that are due for maintenance, replace failed components, clean obvious condensate issues, and ensure bathroom fans, range hoods, and dryer vents function properly.
    • Exterior and structure: Secure loose siding, trim, shutters, steps, decks, handrails, fences, and gates. Replace rotted wood where it is active or structurally relevant.
    • Interior function: Fix doors that will not latch, windows that will not open or lock, running toilets, dripping faucets, damaged caulk, and broken cabinet hardware. These small failures create an outsized impression of deferred maintenance.

    Keep receipts, paid invoices, warranties, permits, and service reports. A repair without documentation may still help the house, but it does less to support a buyer’s confidence. For material work, the paperwork should identify the contractor, date, scope, and any transferable warranty.

    Know What Not to Repair Automatically

    Not every inspection comment deserves a seller-funded project. This is where many owners over-improve a home without improving its market position.

    An inspector may call out an older electrical panel, original windows, minor settlement cracking, a roof approaching the end of its expected service range, or a furnace past a manufacturer’s typical lifespan. Those findings may be accurate while still not requiring a repair before listing. The question is whether the item is unsafe, failing, likely to create a lending obstacle, or inconsistent with the home’s price and competitive set.

    For example, replacing all original windows in a well-kept historic home may be a poor use of funds if buyers value architectural authenticity and the windows operate as intended. Conversely, failed window seals, rotted sashes, or windows that cannot be secured are functional defects worth addressing. A full kitchen renovation may not return its cost in a neighborhood where comparable sales do not support it. Fresh caulk, repaired cabinet doors, better lighting, and a disciplined price may do more.

    The property type changes the analysis. Horse farms and acreage require special attention to fencing, gates, outbuildings, water access, driveways, drainage, and barn safety. Cabins and short-term-rental candidates call for a close review of decks, stairs, retaining walls, HVAC, water systems, and access. A buyer considering a rental property will read deferred maintenance as operating risk, even when an owner-occupant might see it as a weekend project.

    Get Ahead of Lender and Appraisal Friction

    Some repairs matter because they affect financing, not because they are the largest item on an inspection report. VA, FHA, and certain conventional loan scenarios can bring heightened attention to peeling paint, broken handrails, exposed electrical conditions, roof failure, unsafe access, defective heating, or water intrusion.

    This is especially relevant for military-connected buyers near Blue Grass Army Depot and for first-time buyers using government-backed financing. If the likely buyer pool includes FHA or VA purchasers, correct obvious health-and-safety conditions before listing rather than waiting for an appraiser to identify them. It widens the number of buyers who can reasonably pursue the property.

    Be careful with permits. Major electrical, plumbing, structural, deck, HVAC, septic, and addition work may require permits or specialized contractors depending on the jurisdiction and scope. Unpermitted work can become a disclosure issue and may complicate appraisal, insurance, or buyer due diligence. Do not assume that a quick repair is improved by being undocumented.

    Use an Inspection Strategically

    A pre-listing inspection can be useful, but it is not mandatory for every seller. It tends to make the most sense when the home is older, has had long-term ownership, includes a crawlspace or basement history, has unusual systems, is vacant, or will be marketed at a price point where buyers expect well-supported condition information.

    The trade-off is straightforward: once a seller knows about a material defect, it generally needs to be addressed in the disclosure process. That is not a reason to avoid information. It is a reason to seek information early enough to make a controlled decision. A pre-listing inspection is most valuable when there is time to obtain specialist opinions, compare repair bids, and distinguish a real defect from an inspector’s broad caution.

    For some homes, targeted evaluations are more efficient than a general inspection. A sewer scope, roof assessment, HVAC service, structural consultation, chimney review, septic inspection, or wood-destroying insect inspection may answer the questions most likely to arise. The best approach is property-specific, not a generic package of reports.

    Sequence the Work Before You Spend

    Start with a condition review and a realistic valuation range. Repairs should support the property’s market position, not chase a higher number without evidence. A home expected to compete on location, acreage, school access, or architectural character does not need to imitate a newly renovated listing. It needs to present cleanly, operate reliably, and avoid preventable objections.

    Complete messy work first: roof, drainage, crawlspace, electrical, plumbing, and HVAC. Then move to exterior repairs, interior patching, paint, lighting, cleaning, and staging. Photograph only after the repair work is complete. Nothing wastes preparation dollars faster than doing polished cosmetic work before a plumber opens a wall or a drainage contractor crosses the yard.

    When bids arrive, compare scope rather than choosing solely on price. The low estimate may omit disposal, permits, finish work, warranty coverage, or the actual cause of the problem. Sellers benefit from repair decisions that are sourced, dated, and interpreted against the likely buyer response.

    A buyer does not need to believe a home is perfect. They need to see that the owner has treated it seriously. Address the risks that matter, preserve the character that makes the property distinct, and leave the next owner with fewer surprises than the listing photos suggest.

    Fresh paint going onto a home wall during pre-listing preparation
    The highest-return repairs are rarely the expensive ones
  • How to Price a House in Lexington, Kentucky

    How to Price a House in Lexington, Kentucky

    A Lexington home can look perfectly priced on a national portal and still miss the local market by a wide margin. A brick two-story near Chevy Chase, a newer build in Hamburg, and a ranch in Beaumont may share a bedroom count and a rough square-footage range, yet attract different buyers for different reasons. How to price a house in Lexington starts with accepting that a Zestimate-style estimate is a starting point, not valuation in writing.

    The right list price is not simply the highest defensible number. It is the price that reflects recent, relevant evidence while creating enough confidence for qualified buyers to act. That requires current comparables, an honest read of condition, and a practical understanding of what buyers are choosing instead.

    Start with the property, not the desired proceeds

    Sellers understandably begin with a financial goal: the next purchase, a loan payoff, an inheritance division, or a return on improvements. Those numbers matter to the owner, but they do not set market value. The market responds to the property buyers can see, inspect, finance, and compare.

    Before looking at sales, document the house as it exists today. Note the heated living area, lot size, bedroom and bathroom count, age, garage, basement, outdoor living, school assignment, HOA structure, and major systems. Then identify the details that change a buyer’s perception: a renovated kitchen, original baths, roof age, HVAC age, window condition, drainage, electrical updates, and visible deferred maintenance.

    In Lexington, this exercise is especially useful because homes with similar public-record descriptions can perform very differently. A 1950s home in a mature neighborhood may command attention for its setting and architectural character, while a comparable-looking property with unresolved water issues or a dated floor plan can require a clear price adjustment. Sewer first, always. A beautiful listing presentation does not cure a backup risk, a failing line, or an inspection concern buyers can reasonably anticipate.

    Use sold comparables that buyers would actually consider

    The most meaningful comparable sales are recent closed transactions that resemble the subject property and compete within the same buyer decision. Recency matters because mortgage rates, inventory, seasonality, and buyer confidence can shift the market faster than annual neighborhood averages suggest.

    A sound Lexington pricing analysis usually begins with sales from the prior 90 to 180 days, then expands only when the available evidence is thin. The goal is not to collect the largest number of sales. It is to select the most credible ones and explain the differences.

    A useful set of comparables should be similar in location, property type, size, age, condition, and utility. That does not mean every comp must match perfectly. It means each difference should be acknowledged rather than ignored. A renovated home on a quieter street may support a higher value than an unrenovated home near a busier corridor. A finished basement can add value, but rarely at the same per-square-foot rate as above-grade finished space. A larger lot may matter greatly in some areas and very little in a dense subdivision where buyers prioritize interior updates and convenience.

    Active and pending listings belong in the analysis as well. Closed sales tell you what buyers paid. Active listings show the alternatives buyers see today. Pending properties can indicate what is gaining traction, although the final terms remain unknown until closing. This is why stale data can be expensive: a sale from last spring may be relevant context, but it cannot alone establish this month’s list price.

    Price per square foot is a check, not a conclusion

    Price per square foot is useful for spotting outliers and framing a range. It becomes misleading when used as a shortcut. A historic home with restored millwork, a new-construction property with modern systems, and a basic ranch with a finished lower level should not be treated as interchangeable simply because their square footage is close.

    Use the metric to ask better questions: Why did this home sell above the neighborhood range? Was it turnkey? Did it have a premium lot, superior layout, or multiple offers? Why did another one sit? Was the issue price, condition, location, or financing limitations? The answer is usually found in the details, not the average.

    Adjust for Lexington location at a street-level scale

    Lexington is not one market. Even within a recognizable neighborhood, buyer demand can vary by block, school boundary, traffic pattern, lot orientation, and proximity to parks, the University of Kentucky, hospitals, employment centers, or commercial activity.

    For a seller, the question is not whether a neighborhood has a strong reputation. It is how the specific property compares with the strongest available alternatives. A home near downtown may appeal to a buyer who values walkability and character. A family relocating for work may place more weight on commute patterns, garage space, storage, and a move-in-ready condition. A horse-country buyer may care less about subdivision amenities and more about acreage usability, fencing, access, restrictions, and water.

    That distinction becomes sharper outside the city core. In rural Fayette County and throughout the Lexington-Richmond corridor, land value and improvement value need separate consideration. Acreage does not automatically add value at a uniform rate. Road frontage, topography, easements, utilities, septic suitability, floodplain exposure, and farm infrastructure can matter as much as the house itself. A broad comparable search may produce attractive numbers that do not survive a site visit.

    Price condition honestly, then decide whether to improve it

    There are two common pricing errors: pretending a home needs no adjustment for condition, or overestimating the return on every dollar spent before listing. Most projects do not return their full cost dollar for dollar. They can still be worthwhile if they remove a buyer objection, improve photography, or allow the home to compete in a better condition tier.

    Start with repairs that protect value and reduce inspection anxiety. Address active leaks, safety items, visible rot, damaged flooring, malfunctioning systems, drainage concerns, and obvious deferred maintenance. Then consider presentation work such as paint, lighting, landscaping, cleaning, decluttering, and selective cosmetic updates.

    A full renovation is not always the right answer. If a buyer is likely to reconfigure the kitchen or choose their own finishes, the better strategy may be a clean, well-maintained property priced with room for that future work. The decision depends on the price band, buyer profile, expected timeline, and the quality of competing inventory. Preparation should be purposeful, not decorative spending disguised as strategy.

    Choose a launch price, not a negotiation cushion

    The old habit of listing high “to leave room” often creates the wrong kind of room: room for buyers to move on. The first days on market carry disproportionate value because buyers and agents pay attention to new inventory. A price that appears aspirational can reduce showings, weaken urgency, and make a later reduction feel reactive.

    That does not mean every home should be priced below market in pursuit of a bidding war. Some distinctive homes, luxury properties, estates, and rural properties have limited direct comparables and a smaller buyer pool. They may need a carefully supported range and more patience. But the price still needs a reasoned relationship to available alternatives.

    A strong pricing recommendation should state the likely market value range, the recommended launch price, the comparable evidence behind it, and the conditions that could change the result. It should also distinguish list price from probable net proceeds. Seller concessions, inspection repairs, buyer financing, property taxes, brokerage fees, and closing costs all affect the outcome.

    Monitor the first two weeks without panic

    Once the listing is live, watch the response with discipline. Showings, showing feedback, saved-listing activity, open-house conversations, and competing listings can reveal whether the market accepts the price. One comment is anecdotal. A pattern is information.

    If a home receives attention but no offers, buyers may like the location while resisting the price or condition. If showings are scarce, the issue may be the price position, marketing reach, presentation, or a combination of all three. The appropriate response is not always an immediate reduction, but it should be timely. Waiting for the market to “catch up” is rarely a strategy when newer, better-positioned listings are arriving.

    For inherited homes, vacant properties, and investment assets, carry costs deserve special attention. The highest list price is not necessarily the best financial decision if it extends holding time, increases repair exposure, or forces repeated reductions. A clean sale at a well-supported price can be the more favorable result.

    A pricing decision should be sourced, dated, and interpreted

    The most reliable answer to how to price a house in Lexington is a written valuation process rather than a casual estimate. Comparable data should be sourced, dated, and interpreted against the actual house, its condition, its micro-location, and the choices buyers have right now.

    That work protects sellers from two costly promises: the inflated number designed to win a listing appointment and the generic estimate that cannot explain itself. Price the property buyers will actually encounter, prepare it for the questions they will actually ask, and let the evidence lead. The right buyer does not need a sales pitch to recognize a well-positioned home.

    Front exterior and porch of a single-family home
    Every house has a right price — the work is finding it before the market does
  • How to Choose a Kentucky Real Estate Agent

    How to Choose a Kentucky Real Estate Agent

    A Kentucky real estate agent is easy to find. An advisor who can explain why one Richmond home is priced differently from another, flag the drainage risk behind a beautiful acreage listing, or separate a strong Red River Gorge cabin from a costly project is harder to find. The difference is not personality or the number of signs in a yard. It is the quality of the work before a client commits.

    Across the Lexington-Richmond-Red River Gorge corridor, real estate decisions are rarely just about bedrooms, square footage, and the latest automated estimate. They involve commute patterns, school and university schedules, sewer versus septic, road maintenance, flood exposure, horse-farm restrictions, rental rules, repair scope, and the specific buyer pool likely to exist when it is time to sell. Choosing representation should reflect that reality.

    What a Kentucky Real Estate Agent Should Actually Do

    A capable agent does more than open doors and send listing alerts. The core job is to reduce uncertainty while protecting a client’s negotiating position. That requires a current read on the immediate market, not broad statewide commentary or comparable sales pulled without context.

    For a seller, that means valuation in writing. A pricing recommendation should identify the relevant competing listings, recent closed sales, pending activity when available, property-condition differences, and the likely consequences of pricing above or below the market. A well-presented home in a sought-after Lexington neighborhood may need a different strategy than a historic property in Richmond, a farm outside Berea, or a cabin near Slade. They may all be in Kentucky, but they do not trade in the same market.

    For a buyer, representation should begin before the first showing. The agent should help define the decision criteria that matter most: monthly payment, commute tolerance, renovation appetite, land maintenance, resale horizon, and whether a property must serve as a primary residence, second home, or income-producing asset. Those answers determine which listings deserve attention and which should be passed over quickly.

    The best advice is often unglamorous. Sewer first, always. Then ask about water source, easements, driveway responsibility, deed restrictions, insurance availability, utility access, and the condition of systems that cannot be judged from listing photos. A house can be staged beautifully and still carry expensive operational questions.

    Local Knowledge Means More Than Knowing Street Names

    Local fluency is not a memorized list of neighborhoods. It is knowing how a location functions for the person buying it.

    A Lexington professional weighing a newer home in Hamburg against an older home near Chevy Chase may be comparing more than architecture and price. They may be choosing between commute routes, lot size, walkability, maintenance demands, and a different pace of daily life. A relocating household considering Richmond may need a realistic view of the drive to Lexington, access to I-75, proximity to Eastern Kentucky University, and how the local housing stock differs by neighborhood and age.

    In the Red River Gorge region, local knowledge becomes even more operational. Cabin buyers need to understand access in wet weather, topography, private roads, septic capacity, well performance, occupancy expectations, and the practical cost of maintaining a property that may be vacant between stays. Short-term rental income can be attractive, but projections should be treated as a scenario to test, not a promise to repeat. Seasonality, platform dependence, management fees, cleaning costs, furnishing, insurance, and repair reserves all change the math.

    Land requires its own discipline. A tract may look straightforward on a map yet have limited usable area, uncertain road frontage, restrictive easements, poor perc potential, or expensive site-work requirements. For horse property, buyers should also consider fencing, barn condition, water distribution, drainage, pasture management, and the distance between the property and the services they will use regularly. The acreage number alone is not the asset.

    Ask How the Agent Builds a Price Opinion

    Price is where vague advice becomes expensive. An agent should be able to explain the logic behind a recommended list price or offer price without relying on phrases such as “the market is hot” or “we can always come down later.”

    Ask what comparable sales were used and why. Are they recent enough to reflect current conditions? Are they similar in location, lot utility, age, condition, and buyer appeal? Has the agent distinguished a renovated property from one that merely has cosmetic updates? Are active listings being treated as competition rather than proof of value?

    The strongest analysis is sourced, dated, and interpreted. A closed sale is evidence, but it is not automatically a comparable. A listing price is an asking position, not a market result. County records can be useful, but they may lag, omit property-condition details, or require context. Good representation turns those fragments into a defensible recommendation.

    This matters in negotiations. Sellers who understand their pricing position can decide whether to hold firm, make a measured adjustment, or improve the property before launch. Buyers who understand the evidence can write a competitive offer without escalating blindly. Neither side benefits from manufactured urgency.

    Look for Property and Transaction Competence

    A real estate transaction is not a home inspection, legal opinion, lender approval, or construction estimate. Still, an experienced agent should recognize when a question needs to be raised and when a specialist needs to be brought in.

    That practical awareness matters in older homes, rural properties, investment assets, and homes with deferred maintenance. A buyer’s agent should notice signs that warrant further inquiry: a sloping floor, active staining, aging mechanical systems, questionable grading, an improvised addition, or a driveway whose condition may affect access. A listing agent should help a seller identify which repairs, disclosures, and presentation improvements will make the home easier to understand and easier to finance.

    Direct knowledge of repairs can be valuable here, provided the roles remain clear. Clients need transparent recommendations, realistic scopes, and the freedom to choose qualified vendors. The point is not to turn an agent into a contractor. It is to avoid treating preparation as an afterthought once a property is already on the market.

    Transaction management matters just as much. Financing deadlines, inspection periods, appraisal concerns, title questions, repair negotiations, and closing logistics can change the outcome of an otherwise strong deal. Ask prospective agents how they communicate when a transaction becomes complicated. The answer should be specific, organized, and calm.

    Choose the Right Fit for Your Type of Move

    Not every client needs the same kind of representation. A first-time buyer may need a structured explanation of financing, contingencies, and the true monthly cost of ownership. A downsizer may need help deciding whether pre-listing improvements will pay back. An inheritor may need a candid valuation and a clear path through property preparation. An investor may need to test acquisition assumptions against actual operating costs and exit options.

    Relocating buyers should look for an agent who can translate an area without overselling it. That includes honest guidance about commute time, neighborhood character, internet availability, medical access, airport convenience, and the difference between visiting a place for a weekend and living there year-round.

    For private clients, discretion can be as important as exposure. Some properties benefit from broad launch marketing; others require controlled access, careful showing protocols, and a narrower buyer conversation. The right plan depends on the property, the seller’s priorities, and the actual demand profile.

    Questions Worth Asking Before You Commit

    Before signing a representation agreement, ask an agent to walk through a recent transaction similar to yours. Listen for evidence of judgment rather than a rehearsed success story. You want to hear how the price was set, what changed during due diligence, where negotiations became difficult, and how the client was advised.

    Also ask how often you will hear from them, who handles scheduling and paperwork, how they evaluate offers beyond price, and what they do when the data is thin. In rural and specialized property categories, thin data is common. A thoughtful agent will not pretend otherwise. They will explain the limits of the evidence and build a strategy around them.

    A good working relationship should feel direct. You should know what is known, what remains uncertain, what the next decision is, and what it may cost to wait. That clarity is more useful than constant reassurance.

    The right agent will not make a Kentucky property risk-free or guarantee a perfect outcome. They will help you see the trade-offs early enough to make a decision you can stand behind long after the closing table is cleared.

    House keys changing hands at a closing
    The handoff — where good representation shows its work