Marcos Gil, REALTOR® · Keller Williams Commonwealth

Brokered by

The Journal

  • Kentucky Cabin Investments That Hold Up Over Time

    Kentucky Cabin Investments That Hold Up Over Time

    A cabin near the Red River Gorge can produce a compelling listing-page story: views, a hot tub, a fire pit, and proximity to trailheads. That story can also obscure the investment question. Kentucky cabin investments are not interchangeable vacation rentals. A ridge-top A-frame outside Campton, a creekside cabin in Powell County, and a newer rental near Slade may sit within a short drive of one another while carrying very different access, utility, insurance, maintenance, and resale profiles.

    The right purchase begins with the property’s operating reality, not a revenue projection supplied by a listing or booking-platform calculator. Gross income matters, but it is only one line in the analysis. Investors who underwrite the road, the water, the septic system, the local rule set, and the exit audience before negotiating are usually in a stronger position than those who start with a nightly-rate assumption.

    Start With the Location, Not the Cabin Photos

    The Red River Gorge remains the best-known cabin market in Eastern Kentucky, but the phrase “Gorge area” covers several distinct buying environments. Slade offers proximity and recognition. Outlying areas may offer more acreage, privacy, or a lower entry basis, yet a longer drive can affect guest appeal, cleaning logistics, emergency response, and the pool of future buyers.

    Access is not a cosmetic detail. A steep gravel driveway may be manageable in dry weather and a liability in winter or heavy rain. Ask who maintains the road, whether there is a recorded access easement, how delivery vehicles reach the home, and whether ordinary passenger vehicles can navigate the route without concern. If a property depends on a private bridge, shared drive, or low-water crossing, inspect the documentation and the physical condition closely.

    Distance should be measured in drive time, not map distance. Guests arriving after dark, vendors hauling linens, and contractors responding to a plumbing issue experience the route differently than a buyer looking at satellite imagery on a sunny afternoon.

    The cabin’s setting affects its guest and resale audience

    A highly secluded property can command a premium when the experience is exceptional and the access remains straightforward. It can also narrow the resale pool. Conversely, a cabin closer to established hospitality activity may have more competition, but it often benefits from easier wayfinding, service availability, and a more recognizable location signal for guests.

    There is no universal answer. The investment case depends on whether the cabin is intended as a high-occupancy short-term rental, a second home that offsets costs, or a long-hold property with occasional rental use. Those are different strategies and should be underwritten differently.

    Underwrite Kentucky Cabin Investments From the Bottom Up

    A credible pro forma begins with comparable properties, but it should not end there. Identify cabins with genuinely similar bedroom counts, finishes, views, amenities, access, and location. A three-bedroom cabin with paved access and professionally designed outdoor space is not comparable to a three-bedroom home reached by a narrow, unlit mountain road.

    Revenue estimates should account for seasonality. Weekend demand, fall color, climbing and hiking traffic, holidays, and school breaks can create strong periods. Midweek and off-season performance tell a more complete story. Rather than relying on a single occupancy figure, use a conservative base case, a stronger case, and a downside case with softer rates or fewer booked nights.

    Then treat expenses as operating facts, not placeholders. A cabin may require professional management, cleaning coordination, consumables, laundry, pest control, hot tub service, internet, trash handling, propane, electricity, landscaping, snow or storm response, and regular exterior maintenance. Mountain properties can also carry higher wear from moisture, insects, tree cover, and guest turnover.

    A useful underwriting review separates fixed expenses from variable ones. Taxes, insurance, debt service, certain utility minimums, and some maintenance obligations persist even when bookings slow. Management and cleaning costs may move with occupancy, though not always as neatly as a spreadsheet suggests. Reserve capital for roofs, HVAC systems, decks, retaining walls, drainage corrections, appliances, septic work, and furniture replacement. A cabin that photographs well but has deferred exterior work is not a bargain simply because the purchase price appears favorable.

    Sewer First, Always

    Many desirable cabin sites rely on septic systems or other on-site wastewater solutions. This is one of the most consequential areas of due diligence, particularly when the intended guest count exceeds the home’s historic use.

    Confirm the system type, permit history where available, maintenance records, tank location, field location, and capacity. Do not assume that a home advertised with multiple bedrooms can legally or practically support the sleeping configuration proposed for a short-term rental. A property’s number of beds, its wastewater capacity, and its marketed occupancy should make sense together.

    Water deserves the same scrutiny. A private well, shared system, cistern, or spring-fed arrangement may be perfectly workable, but each requires a clear understanding of ownership, testing, storage, treatment, reliability, and repair responsibility. Internet service should be verified at the property, not inferred from a provider’s broad coverage map. Remote workers and families increasingly consider reliable connectivity part of the rental product.

    Rules, Permits, and Insurance Are Part of the Basis

    Before buying a cabin for rental use, establish what is permitted at the parcel level. County rules, local ordinances, deed restrictions, HOA covenants, and insurance requirements can all shape the operation. Rules change, and generalized advice from a social media group is not diligence. The relevant documents should be sourced, dated, and interpreted for the specific property.

    A buyer should also ask whether a current short-term rental operation, permit, or business registration transfers, expires, or must be renewed. The answer may affect the timing of the first rental season. If the seller presents income history, request enough detail to understand whether it reflects owner stays, unusually favorable launch-period demand, discounted bookings, management changes, or one-time events.

    Insurance needs careful attention in wooded and rural settings. Confirm that the policy will cover the intended use, including short-term rental activity if applicable. Review deductibles, exclusions, replacement-cost assumptions, and exposure to wind, water, fire, fallen trees, and guest-related claims. An inexpensive quote that excludes the actual operating model is not useful protection.

    Value the Operational Condition, Not Just the Architecture

    Cabin buyers are often drawn to design, and they should be. A distinctive A-frame, modern glass wall, vaulted living room, or carefully composed outdoor area can make a property more bookable and more memorable. But design does not excuse poor building performance.

    Inspect roofs, flashing, gutters, decks, railings, grading, drainage, crawl spaces, retaining walls, windows, wood siding, and HVAC systems with particular care. In wooded terrain, water management is often the quiet determinant of future expense. Look for staining, settlement, soft decking, standing water, erosion, overloaded gutters, and evidence that repairs were made cosmetically rather than structurally.

    Operational readiness also has a market value. A well-maintained cabin with documented systems, clear access, reliable vendors, and orderly records may justify a higher basis than a similar-looking property requiring immediate repair coordination. Marcos Gil Realty’s repair-informed perspective is particularly useful here: the question is not merely whether an issue exists, but what it will cost, how quickly it can be corrected, and whether it will interrupt revenue during the repair.

    Plan the Exit Before You Close

    An investment is easier to own when it has more than one plausible exit. Consider who would buy the cabin if short-term rental economics soften: another investor, a regional second-home buyer, a full-time resident, or a buyer seeking a recreational retreat. Properties with broad appeal tend to be easier to reposition than cabins built around a narrow novelty.

    This does not mean every investor should avoid specialized properties. It means the premium paid for a dramatic view, unusual layout, or remote setting should be deliberate. A cabin can be an excellent hospitality asset and a less liquid residential asset at the same time.

    Model a sale after ordinary transaction costs and possible repair requests. Also consider the condition in which frequent guest use may leave the property after several years. The strongest operators reinvest in furnishings, exterior care, and guest-facing details before they become obvious deficiencies in a future listing.

    A sound cabin purchase should still make sense after the peak-season screenshots are put away. If the access is clear, the systems are supportable, the numbers remain credible under a conservative case, and the resale audience is understood, the property has earned a closer look. That is where a Kentucky cabin investment becomes less of a wager on weekend demand and more of an asset you can own with confidence.
  • Tools I Actually Recommend for New Kentucky Agents

    New agents ask me what to buy, and the honest answer is almost always: less than you think. Year one is not won by software. It is won by whether you talk to enough people, follow up on time, and know your numbers cold.

    What I would put time into first: your database (every person you know, in one place, with a reason to call), a 90-day prospecting rhythm you can keep on your worst week, and an honest pipeline — not the deals you hope for, the ones with a next step and a date attached.

    Full disclosure on this next one: I built these for my own use first. the agent shelf at WorkbookBarn is a set of planning workbooks — an annual business plan, prospecting planners, pipeline and contract-to-close trackers — written by a working REALTOR® rather than adapted from a generic sales template. Simple tools like these beat an expensive CRM in year one for one reason: you will actually fill them out.

    Whatever you end up using, track your activity weekly, not your commissions monthly. Activity is the only number you control.

  • Kentucky VA Loan Process From COE to Closing

    Kentucky VA Loan Process From COE to Closing

    A VA loan can be one of the strongest financing options available to an eligible Kentucky buyer, but it is not a shortcut around careful underwriting or property due diligence. The Kentucky VA loan process still requires a lender-ready file, a contract written with the right protections, an appraisal that supports value, and a house that meets basic VA property standards. In Central and Eastern Kentucky, the property itself often determines whether the transaction feels straightforward or unexpectedly complicated.

    A clean brick home in a Lexington neighborhood may move through underwriting with few surprises. A cabin near Slade, an older Richmond property with deferred maintenance, or a rural home on acreage can require a more deliberate review of water, septic, access, condition, and market support. The financing is federally backed. The real estate is local.

    Start With Eligibility and a Real Preapproval

    The first document is the Certificate of Eligibility, commonly called the COE. It confirms to the lender that you have VA home loan entitlement based on military service, qualifying National Guard or Reserve service, or, in certain cases, surviving-spouse eligibility. Many lenders can retrieve the COE electronically. When they cannot, the lender can help identify the documentation needed to request it.

    The COE is not a loan approval. That distinction matters. A true preapproval also reviews income, employment, assets, credit, monthly obligations, and the proposed use of the home as a primary residence. A lender may be comfortable with a purchase price in the abstract but adjust its guidance after reviewing childcare, student loans, variable income, retirement income, or a pending move to Kentucky.

    For buyers relocating near Blue Grass Army Depot, the timing of a new assignment or civilian employment offer can be especially important. Ask the lender early how they will document the transition. For self-employed buyers, investors with multiple properties, or households using bonus and commission income, provide complete and current records rather than working from a verbal estimate.

    VA loans are often associated with zero down payment, and that can be accurate for an eligible buyer with sufficient entitlement. It does not mean zero cash is needed. Earnest money, inspection costs, appraisal charges, prepaid taxes and insurance, and reserve requirements can still affect the cash needed before or at closing. The funding fee may apply as well, although some veterans are exempt because of service-connected disability status. Your lender should show the numbers in writing, including whether the fee is financed or paid at closing.

    Choose the Lender Before You Choose the House

    Not every lender handles VA lending with the same discipline. The useful question is not simply who advertises the lowest rate on a given morning. Ask who will underwrite the file, how quickly they can issue a preapproval based on documents, how they handle appraisal reconsiderations, and whether they regularly close VA purchase loans in Kentucky.

    Compare official loan estimates once you are far enough along to receive them. Rate, lender fees, discount points, prepaid items, and projected cash to close belong in the same conversation. A lower rate can be sensible if you expect to hold the mortgage for years; paying points for a rate reduction may make little sense if a military transfer, career move, or planned refinance is likely within a short period.

    The VA does not impose a maximum loan amount on borrowers with full entitlement, but the lender still sets approval standards based on income, credit, debt, and the property. A buyer should avoid treating a maximum approval as a target price. The better purchase range leaves room for maintenance, moving costs, and the reality of owning a home rather than occupying government housing.

    Write a Contract That Protects the Buyer

    Once you find the right property, the purchase contract becomes the working document for the rest of the transaction. The offer should reflect the financing type, intended closing schedule, earnest money, inspection period, appraisal contingency, and any seller-paid closing-cost request. In a competitive Lexington or Richmond listing situation, these terms can matter as much as price.

    A VA buyer should be wary of waiving meaningful protections simply to make an offer look cleaner. The VA appraisal is not a substitute for a buyer’s inspection. It is an opinion of value for lending purposes and an assessment of whether the home appears to meet VA minimum property requirements. It will not provide the detailed condition report that helps a buyer make an informed repair decision.

    Seller concessions can be useful, particularly when a buyer wants to preserve cash. They are not automatic, and they must fit both the contract and lender guidelines. In some cases, a seller contribution toward allowable closing costs improves the buyer’s position more than a modest price reduction. In others, a higher contract price may not appraise. The structure needs to be sourced, dated, and interpreted against the property and current comparable sales.

    The Appraisal Has Two Jobs

    The lender orders the VA appraisal after the contract is in place. The appraiser evaluates whether the home supports the agreed purchase price and whether it appears to meet the VA’s minimum property requirements. Those requirements focus on safety, soundness, and sanitation. They are not a cosmetic checklist, but they can bring visible defects into the transaction.

    Common examples include peeling paint on older homes, exposed electrical issues, a damaged roof, missing handrails where needed, unsafe decks or stairs, active moisture concerns, and inadequate heating. On rural properties, the appraisal may raise questions about the water source, septic system, private road access, or whether the home is readily marketable in its location.

    Kentucky’s older housing stock makes condition especially relevant. A well-kept 1950s ranch may be an excellent VA candidate. A historic home with aging systems can also qualify, but the parties should expect more scrutiny if basic repairs are visible. For acreage and farm-adjacent property, lenders and appraisers may need to separate the value of the primary residence from land or improvements that extend beyond typical residential use.

    If the appraisal comes in below the contract price, the buyer is not required to bridge the gap. The VA’s amendatory clause protects the buyer from being obligated to purchase above appraised value. That does not automatically end the deal. Buyer and seller can renegotiate the price, the buyer can bring additional cash if appropriate and approved, or the parties can dispute factual appraisal errors through the lender’s available process. The best response depends on the comparable sales, not frustration with the number.

    Inspect Beyond What the Appraiser Sees

    The inspection period is where a buyer can investigate the operational reality of the property. For a typical in-town home, a general inspection may identify roofing, plumbing, electrical, HVAC, drainage, foundation, and safety issues worth addressing. For a rural Kentucky property, the scope should expand with the site.

    Sewer first, always, where public sewer is present. A sewer scope can reveal roots, breaks, offsets, or aging lines that a standard inspection cannot see. Where a septic system serves the property, verify the system’s location, age, service history, and whether the bedroom count and use are consistent with the system’s capacity. For a well, understand testing, yield, treatment equipment, and who maintains it.

    A cabin, second-home style property, or home near the Red River Gorge deserves particular attention to slope drainage, retaining walls, private drives, insurance availability, internet service, and access in wet or winter conditions. If the purchase is intended as a primary residence using VA financing, be direct about occupancy. VA financing is designed for an owner-occupied home, not a vacation property or a short-term rental acquisition.

    Underwriting, Final Walk-Through, and Closing

    While inspections and appraisal are underway, the lender moves the file through underwriting. Expect requests for updated pay stubs, bank statements, explanations of deposits, proof of homeowners insurance, and documents related to any credit, employment, or asset changes. Do not open new credit accounts, move large sums without a paper trail, or change jobs without speaking to the lender first. Those decisions can alter the approval late in the process.

    Before closing, review the closing disclosure carefully. It should align with the loan estimate and the contract’s negotiated terms, while reflecting final prepaid items and any approved seller contribution. Ask about any figure that is unclear. A closing statement is not the place for vague assumptions.

    The final walk-through is equally practical. Confirm that agreed repairs are complete, included personal property remains, and no new damage has occurred since inspection. Turn on faucets, test visible systems, and make sure the house is being delivered in the condition the contract requires. If a repair receipt matters, obtain it before closing rather than hoping it appears afterward.

    A well-run VA purchase is not about racing to the closing table. It is about matching a buyer’s earned benefit to a home that is financially sound, physically suitable, and honestly valued. When the lender file is organized and the property review is rigorous, Kentucky buyers can use VA financing with the confidence it was meant to provide.

  • How to Buy a Lexington Home Without Guesswork

    How to Buy a Lexington Home Without Guesswork

    A Lexington purchase can look straightforward until the details begin to separate one house from another. A renovated bungalow near the University of Kentucky, a newer home in Hamburg, and an acreage property beyond New Circle Road may share a price range while carrying entirely different ownership costs, resale profiles, and due-diligence demands. Knowing how to buy a Lexington home means moving beyond the listing portal and making each decision in the right order.

    Start With a Buying Brief, Not a Search Filter

    Bedroom count and price are useful filters, but they are not a buying strategy. Before touring homes, define what the purchase needs to accomplish over the next five to ten years. For some households, that means a short commute to downtown, UK, Baptist Health Lexington, or the airport. For others, it means a yard, a workshop, a horse-friendly setting, or a property that could support a future rental strategy.

    Be precise about the trade-offs you will accept. Older Lexington neighborhoods often offer established trees, walkability, and architectural character, but may also bring smaller closets, aging systems, limited driveway space, and renovation considerations. Newer subdivisions can offer more predictable layouts and modern mechanicals, though lots may be tighter and association rules more restrictive. Neither is automatically the better buy. The right answer depends on how you intend to live in the property and how long you expect to hold it.

    It also helps to separate non-negotiables from preferences. A non-negotiable is a school commute, first-floor primary bedroom, or the ability to keep horses. A preference is a particular paint color or countertop. Buyers who confuse the two often miss suitable homes while waiting for a perfect one that does not exist at the right price.

    Get Financing Aligned With the Property Type

    A pre-approval is more than a letter attached to an offer. It establishes the financing framework for your search: monthly payment comfort, down payment, cash reserves, appraisal risk, and the loan products available for the homes you are considering.

    Ask your lender to model more than one purchase price and rate scenario. Include property taxes, homeowners insurance, mortgage insurance if applicable, and association dues. For rural properties, cabins, farms, and homes with substantial acreage, ask early whether the lender has restrictions involving private roads, well and septic systems, mixed-use structures, or the amount of land included in the loan. These issues can affect underwriting even when the house itself is in excellent condition.

    Kentucky buyers using VA, FHA, conventional, physician, or portfolio financing should not assume one loan is universally best. A VA loan can be an excellent fit for an eligible buyer, but the appraisal and property-condition process may influence the type of house that is practical to pursue. A conventional buyer with a strong down payment may have more flexibility in a competitive multiple-offer situation. The point is not to chase a label. It is to understand the terms before the right home appears.

    Learn the Lexington Map at Street Level

    Lexington is not one market. Price movement, inventory, lot characteristics, and buyer demand can change materially between nearby neighborhoods. A house near Chevy Chase, Kenwick, Beaumont, Hamburg, Masterson Station, or the expanding edges of Fayette County should be evaluated within its own competitive set, not against a citywide average.

    For relocating buyers, the commute is often the first practical lens. A 20-minute drive can become materially longer at school pickup, during UK events, or when construction affects a major corridor. Tour at the times you will actually use the route. Stand outside the property, not just inside it. Listen for traffic, train noise, commercial activity, and nearby athletic fields. Look at the orientation of the backyard and the distance between homes.

    If your search expands into Richmond, Madison County, Georgetown, Versailles, Nicholasville, or the Red River Gorge corridor, reset your assumptions. Septic systems, wells, road maintenance agreements, flood exposure, internet service, land restrictions, and insurance availability deserve earlier attention outside the city core. The address may be close enough for a manageable commute, but the ownership experience can be entirely different.

    How to Buy a Lexington Home With Better Due Diligence

    The strongest buyers are not merely fast. They are prepared to investigate the parts of a property that photographs cannot show. That begins before an offer in many cases, especially when a home is likely to attract immediate interest.

    Review the seller disclosures carefully, but treat them as a starting point rather than a complete property report. Ask what has been replaced, when it was replaced, who performed the work, and whether permits or warranties exist. A new kitchen is visually appealing; the age and condition of the roof, HVAC, electrical service, foundation drainage, and plumbing will usually matter more to long-term ownership.

    For Central Kentucky properties, water management deserves particular attention. Look at grading, downspouts, gutters, retaining walls, crawl spaces, basement walls, and the path water takes after a heavy rain. Sewer first, always. Confirm whether the home is served by public sewer or a septic system, then investigate accordingly. A well-maintained septic system can be perfectly suitable, but buyers should understand its age, capacity, maintenance history, and location before proceeding.

    During the inspection period, use qualified specialists when the facts justify it. A general home inspection may identify conditions that warrant a sewer scope, structural review, chimney inspection, roof assessment, radon test, pest inspection, or further evaluation of a well and septic system. This is not about turning every older house into a problem. It is about pricing the condition honestly and deciding whether the home remains the right fit.

    Historic homes, horse properties, and acreage require another layer of review. Boundaries, access easements, fencing, barns, drainage, agricultural use, zoning, and deed restrictions should be understood before the contingency period ends. A beautiful tract without practical access or a clear understanding of its restrictions can become an expensive lesson.

    Write an Offer That Matches the Moment

    A competitive offer is not always the highest number. It is the offer the seller can understand, trust, and compare with confidence. Price matters, but so do financing strength, earnest money, contingency timing, appraisal terms, requested concessions, possession, and the credibility of the buyer’s plan.

    The right terms depend on the property and the competition. On a clean, well-priced home with several interested buyers, a buyer may need to shorten certain timelines or limit requests that are not essential. On a home that has been available longer, there may be room to negotiate price, repairs, closing costs, or a more favorable possession date. Waiving inspections simply to look aggressive can be a poor decision, particularly with older housing stock, rural systems, or a property showing deferred maintenance.

    Use recent comparable sales as evidence, not as a formula. A sale from six months ago may have closed under different inventory, rate, and condition dynamics. The useful analysis is sourced, dated, and interpreted: what sold, what was active at the time, how the homes compared, and whether the subject property has a feature that changes its value. A finished basement, corner lot, backing to green space, renovated systems, or an inferior road location can all alter the comparison.

    Plan for the First Year of Ownership

    Closing is not the end of due diligence. Preserve every inspection report, receipt, disclosure, survey, warranty, and service record in one place. Change locks or rekey doors, locate shutoffs, service the HVAC if its history is uncertain, and create a realistic maintenance reserve. The first year often reveals the small items that did not make sense to negotiate during the transaction but still deserve attention.

    For an investment-oriented purchase, keep the operating picture equally disciplined. Verify rental rules, insurance costs, utility responsibility, parking, projected maintenance, and the legal limits of any short-term-rental plan before assuming income. A desirable Lexington location does not automatically make every property an effective rental asset.

    The best Lexington purchase is rarely the house that looked most impressive for ten minutes. It is the one whose location, condition, financing, and future use continue to make sense after the excitement of the showing has passed.

    Related guides: Walnut Hill, Lexington KY – Rural-Edge Living · Idle Hour: An Established East Lexington Neighborhood Guide · Griffin Gate, Lexington KY – Golf & Resort Living · Gleneagles, Lexington KY – Neighborhood Guide · Bryant Oak Place, Lexington KY – Neighborhood Guide · Lexington Condos & Townhomes: The Low-Maintenance Market · Homes with Workshops & Big Garages in Central Kentucky · Homes with Pools in Central Kentucky · Golf Communities of Central Kentucky · Find a Property

  • Kentucky Homebuyer Closing Guide: What to Expect

    Kentucky Homebuyer Closing Guide: What to Expect

    A Kentucky homebuyer closing guide should begin with one practical fact: the day you receive the keys is not the day to discover an unpaid utility balance, a missing repair receipt, a boundary question, or a wire instruction that arrived by email. Closing is the final transfer of a property, but the quality of the closing is determined by the work done in the weeks before it.

    For a Lexington condominium, a Richmond family home, a farm outside Berea, or a Red River Gorge cabin, the paperwork follows a familiar sequence. The risk profile does not. A sound closing process is sourced, dated, and interpreted for the property in front of you – not borrowed from a generic checklist.

    What Closing Means for a Kentucky Buyer

    Closing is the legal and financial handoff from seller to buyer. Your lender, title company or closing attorney, real estate agents, insurance provider, and sometimes surveyor or contractor each contribute documents or information. The settlement agent coordinates the final figures, confirms that title requirements have been met, receives funds, obtains signatures, and records the deed and mortgage documents with the appropriate county clerk.

    Most financed buyers receive a Closing Disclosure at least three business days before consummation. This document deserves a slow reading. It sets out the loan terms, monthly payment, cash required to close, lender charges, title and government fees, prepaid items, and prorations. Compare it with your Loan Estimate, but do not assume every difference is an error. A change in closing date, insurance premium, prepaid interest, tax treatment, or lender credit can move the numbers legitimately. The question is whether each change is explained and supported.

    Cash buyers have fewer lender documents, but not fewer reasons to review the settlement statement. Title charges, recording costs, tax prorations, earnest-money credits, association fees, and any negotiated repair credit still need to be right.

    Before Closing: Clear the Conditions That Matter

    The purchase contract establishes deadlines, but deadlines alone do not make a buyer protected. Inspection, appraisal, financing, title, and insurance are distinct workstreams. A clean appraisal does not validate a roof, a septic system, a shared driveway agreement, or the insurability of an older electrical panel.

    Inspection Is a Decision Point, Not a Report Collection Exercise

    A general home inspection identifies visible conditions on the day of inspection. It is not a warranty and it is not a substitute for specialized review where the facts call for it. Older Lexington homes may warrant sewer-scope work, electrical review, or further investigation of moisture in a basement. Sewer first, always, where an older urban property, mature trees, slow drains, or a cast-iron line create a reasonable concern.

    In Madison County, Estill County, Powell County, and rural parts of the corridor, water, septic, road access, drainage, and outbuilding conditions may carry more weight than cosmetic updates. A cabin can photograph beautifully while presenting a difficult driveway, inadequate drainage, unverified short-term-rental assumptions, or a septic system poorly matched to its use. If a repair is negotiated, define it precisely: who performs it, whether permits are required, what documentation is due, and whether the work must be complete before closing.

    Title, Survey, and Property Rights

    Title work is where a closing stops being visual and becomes legal. The title search examines the recorded history of ownership and identifies matters that must be resolved, insured around, or accepted by the buyer. Common items include mortgages, judgment liens, easements, restrictive covenants, utility rights-of-way, and prior deeds that affect access or use.

    Do not treat an easement as automatically alarming or automatically harmless. A utility easement in a predictable location may be routine. An access easement serving several parcels, a shared drive without a recorded maintenance agreement, or a restriction affecting a planned barn, fence, rental use, or addition deserves focused review.

    A survey is especially useful when boundaries, fencing, acreage, improvements near a line, access, or planned construction matter. It may not be necessary in every conventional neighborhood purchase, but it is often cheap clarity for land, farms, historic properties, and irregular lots. Ask what type of survey is being provided, what it does and does not certify, and whether the title commitment includes exceptions that the survey could clarify.

    Read Your Closing Disclosure Like an Owner

    The final cash-to-close figure is not a number to glance at in the parking lot. Review it with enough time to ask questions. Confirm the purchase price, earnest-money credit, loan amount, seller concessions, inspection or repair credits, lender credits, and the amount of your down payment.

    Also review the recurring costs. Property taxes in Kentucky are commonly prorated between buyer and seller based on the contract and local billing cycle. The precise treatment can vary with the county, the closing date, lender escrow requirements, and contract language. Transfer and recording charges likewise should be shown clearly, with responsibility allocated according to the agreement and local practice. A settlement statement should not require guesswork.

    Homeowners insurance must be bound before a financed closing, and the policy must meet lender requirements. For rural homes, cabins, and properties with detached structures, make sure the coverage matches the actual property and intended use. A policy written as a primary residence may not fit a second home or rental operation. If you are relying on rental income, do not leave that underwriting question until the week of closing.

    The Final Walk-Through Is a Verification, Not a Second Inspection

    The final walk-through usually occurs shortly before closing. Its purpose is narrow but important: confirm the property is in substantially the agreed condition, confirm negotiated repairs are complete, verify agreed personal property remains, and look for damage caused by moving out.

    Bring the repair agreement and any receipts or invoices that were promised. Run the major systems that can reasonably be checked, including heat or air conditioning depending on the season, faucets, toilets, appliances that convey, garage doors, and lights. Look in the attic, basement, crawlspace access area, and under sinks when relevant. If the seller has moved out, this is also the moment when a concealed leak or newly visible wall damage often becomes apparent.

    A problem at the walk-through does not always mean the transaction should collapse. It may support a holdback, a repair before signing, a credit, or a written agreement for a specific cure. The right response depends on the issue, your financing, timing, and appetite for uncertainty. What should not happen is a verbal promise replacing a written solution.

    Funding the Purchase Without Creating a Preventable Problem

    Wire fraud remains one of the most avoidable closing risks. Criminals can impersonate agents, lenders, title companies, and even family members with convincing email addresses and altered payment instructions. Never rely on emailed wiring instructions alone. Call a known, independently verified phone number for the settlement office and confirm instructions verbally before sending funds. Do not use a number contained in the suspicious message.

    Your lender will also care about the source of funds. Avoid large unexplained deposits, new credit accounts, vehicle purchases, job changes, or transfers that cannot be documented during the final stretch to closing. A gift from a family member can be acceptable, but it generally needs to be documented in the format your lender requires. The rule is simple: do not make your financial file harder to underwrite after it is already approved.

    Bring the identification and certified funds, if required, that the settlement agent has specifically requested. Ask in advance whether a wire, cashier’s check, or other method is acceptable. Personal checks are often not appropriate for the final balance.

    Signing Day and the First Week of Ownership

    At closing, expect to sign the settlement statement, loan documents if financed, deed-related acknowledgments, title affidavits, and tax or occupancy forms. Take your time with documents that create ongoing obligations, particularly the promissory note, mortgage, and any homeowners association materials. Ask questions before signing, not after the recording queue has started.

    Keys, garage remotes, gate codes, mailbox information, warranties, and security-system details should be accounted for. Possession is usually delivered at closing, but the contract controls. If the seller remains in possession after closing, a written post-closing occupancy agreement should address dates, insurance, deposits, utilities, condition, and consequences if the move-out is delayed.

    Once the deed is recorded, keep your closing package in a secure place. Change exterior locks or rekey them, update alarm access, transfer utilities, and photograph the property condition on day one. For acreage or rural property, locate shutoffs, septic records, well equipment, boundary markers, and any shared-road contacts before an urgent repair forces the issue.

    A disciplined closing is not about making a complicated process feel ceremonial. It is about leaving the table with clean title, correct figures, documented repairs, understood obligations, and a property you can actually operate on the morning after you buy it.

  • Lexington Multifamily Investing That Holds Up

    Lexington Multifamily Investing That Holds Up

    A fourplex near the University of Kentucky can look exceptional on a spreadsheet and still be the wrong acquisition. The asking rents may be plausible, the location may be familiar, and the gross yield may look better than a comparable single-family rental. But Lexington multifamily investing is won or lost in the details behind those numbers: lease quality, utility configuration, deferred maintenance, tenant turnover, parking, zoning, and the realistic cost of bringing an older building into dependable operating condition.

    That is especially true in a market where housing demand comes from several distinct sources. University and hospital employment, state government, professional services, equine industry activity, and regional in-migration all support rental demand. They do not, however, support every property in the same way. A duplex in Chevy Chase, a small apartment building near campus, and a workforce-oriented asset on the east side are not interchangeable investments simply because each has multiple units.

    Start With the Tenant, Not the Unit Count

    The first question is not whether a property has two, four, or 20 doors. It is who rents there, why they choose that location, and what alternatives they have when a lease ends.

    Near the university, tenant demand can be deep but turnover is often built into the operating model. Student-oriented properties may require more frequent leasing, more wear on interiors, and a sharper approach to parental guarantors, roommate changes, and pre-leasing. A building that performs well under active management can produce disappointing results when treated like a passive hold.

    In established in-town neighborhoods, tenants may value walkability, neighborhood character, and proximity to employment centers. Those renters can be durable, but older housing stock often comes with older systems. The market may reward a thoughtful renovation, yet the work must be priced against the building’s construction, access constraints, historic considerations, and achievable rent ceiling.

    Further from the urban core, the investment case may rest on affordability and access to employment corridors rather than lifestyle amenities. These properties can provide steadier tenancy, but investors should test the local renter pool instead of assuming a lower acquisition price creates a margin of safety. Nearby competing inventory, household income, transit or commuting patterns, and the condition of surrounding properties all matter.

    A useful underwriting file separates market rent from current rent and from truly collectible rent. Those are three different figures. A unit advertised at a certain price is not necessarily leased at that price, and a signed lease is not the same as consistent cash received.

    Lexington Multifamily Investing Is Submarket Specific

    Lexington is compact enough to feel familiar and varied enough to punish broad assumptions. A property one mile away can serve a different renter profile, sit in a different school context, or compete against a newer and better-appointed inventory set.

    Campus and medical employment corridors

    Properties near the University of Kentucky, UK HealthCare, and downtown employment centers can benefit from reliable demand drivers. The trade-off is that acquisition pricing often reflects that visibility. Investors should not pay a premium simply because a property is close to campus. Examine the walkability of the specific block, parking availability, bedroom count, unit layout, safety perception, and the condition of competing rentals.

    A two-bedroom unit with off-street parking may attract a different tenant than a similarly sized unit requiring street parking and a longer walk. In small multifamily, those distinctions can materially affect vacancy and turnover expense.

    Established neighborhoods and infill locations

    Older duplexes, triplexes, and converted homes are common in desirable Lexington neighborhoods. They can be attractive because land is limited and replacement cost is high. They can also hide the most expensive problems: aging sewer laterals, galvanized plumbing, insufficient electrical service, foundation movement, roof transitions, and poorly documented additions.

    Sewer first, always. A sewer scope is a modest diligence expense compared with the cost and disruption of replacing a failed line under a driveway, mature landscaping, or an occupied building. The same principle applies to electrical panels, main water lines, drainage, and shared mechanical systems. Cosmetic renovation is easy to see. Infrastructure is where the real operating risk sits.

    Outer-ring and value-oriented locations

    Properties in less central locations may offer more favorable entry pricing or larger unit counts for the capital deployed. The question is whether the property is priced correctly for its tenant base and its physical condition. A lower rent does not excuse unreliable collections, chronic vacancy, poor layout, or a building that will require repeated capital infusions.

    The better opportunity is often a property with a clear, limited business plan: correct below-market rents, improve unit condition without overbuilding, repair known systems, and professionalize management. The weaker opportunity is the one marketed as “value-add” without a credible explanation of what value can actually be added.

    Underwrite Operations as Carefully as Purchase Price

    Small multifamily is frequently sold on gross rent multiplier, cap rate, or a simple cash-flow estimate. Those shortcuts can be useful for an initial screen. They are not a purchase decision.

    Begin with trailing operating statements, then reconstruct them. Verify rent rolls against leases and bank deposits where appropriate. Identify which utilities are owner-paid, whether tenants reimburse any portion, and whether common-area electric, water, trash, lawn care, snow removal, pest control, or laundry equipment are included in the expense history. In a four-unit building, one incorrectly assumed utility line can change the investment materially.

    Property taxes deserve separate attention. A sale can trigger a reassessment or otherwise alter the tax picture, and historical taxes may not reflect the new basis. Insurance should be quoted for the asset as it will be owned, not copied from a seller’s older policy. For buildings in older neighborhoods, ask whether replacement-cost coverage, ordinance and law coverage, and deductibles are sufficient for the actual structure.

    Set aside reserves for capital expenditures even when the seller says the building has been “well maintained.” A property can be clean, occupied, and still be approaching major expenditures. Roof age, HVAC age, windows, paving, water heaters, retaining walls, and exterior wood condition should be documented, dated, and interpreted. If the inspection identifies a concern, convert it into a cost range and a timing assumption before removing contingencies.

    Management is another line item investors routinely underestimate. Self-management can work for an owner with nearby operations, maintenance capacity, and the appetite for tenant communication. It is less compelling when the investor lives out of state, owns a demanding business, or acquires a tenant profile with high turnover. The right question is not whether management can be avoided. It is what the asset requires to perform well and whether that requirement is fully funded.

    Financing Can Change the Deal More Than the Rent Increase

    Two-to-four-unit properties can sometimes be financed differently from larger apartment buildings, particularly when an owner intends to occupy one unit. That may create a more accessible path into multifamily ownership, but it does not eliminate the need for disciplined underwriting. Owner-occupancy rules, reserve requirements, appraisal standards, debt-service coverage expectations, and lender treatment of projected rents all need to be understood early.

    For a five-unit or larger acquisition, commercial financing commonly places more weight on the property’s income, borrower experience, liquidity, and debt-service coverage. Loan terms, rate structure, prepayment provisions, recourse, and future refinance assumptions deserve the same scrutiny as the property itself. A deal that works only after an aggressive refinance or a perfect rent-growth assumption is not a conservative acquisition.

    Investors using a 1031 exchange have an additional constraint: the identification window can create pressure to buy quickly. That pressure is understandable, but it is not a reason to waive building-level diligence. A replacement property must still fit the investor’s long-term hold strategy, tax posture, operational capacity, and risk tolerance.

    Make Diligence Physical, Financial, and Legal

    A strong inspection is necessary, not sufficient. For multifamily, diligence should connect physical findings to the rent roll and operating statement. If three units have window air-conditioning, for example, confirm electric capacity and tenant utility responsibility. If a building has separate meters, verify that the meter configuration matches the leases and actual unit layout. If the seller reports recent renovations, ask what was permitted, who completed the work, and whether invoices or warranties are available.

    Review leases for renewal dates, security deposits, concessions, pet terms, utility responsibilities, notice periods, and any informal arrangements that may not appear on the rent roll. Walk every unit when possible. A vacant model unit tells very little about how occupied units have been maintained.

    Then review the legal and site context. Confirm zoning, unit count, parking compliance, access, easements, flood considerations, and any local restrictions relevant to the current use. Converted homes are particularly worth examining closely. The building may have functioned as multifamily for years, but investors should understand how the use is documented and what constraints could affect future renovation, rebuilding, or financing.

    The Best Deal Is Usually the One You Can Explain Clearly

    Good Lexington multifamily acquisitions rarely depend on a clever spreadsheet formula. They depend on buying a specific building at a defensible basis, for a known renter pool, with enough capital to correct what is wrong and operate it properly afterward.

    Before making an offer, write the investment case in plain language. State why tenants will choose the property, where rent growth will come from, which repairs are required, what could interrupt cash flow, and what return remains if the optimistic case never arrives. If that explanation is vague, the property is not ready to buy. If it is clear, dated, and supported by the building itself, you have the kind of discipline that tends to hold up long after closing.

  • EKU Off Campus Housing Guide for Richmond Renters

    EKU Off Campus Housing Guide for Richmond Renters

    A lease can look inexpensive until the first utility bill, parking charge, roommate dispute, or August move-in problem arrives. This EKU off campus housing guide is built for the practical questions that matter before you commit: where you will live, how you will get to campus, what the lease actually requires, and whether the monthly number still works after every recurring cost is counted.

    Eastern Kentucky University gives students and university-affiliated households a compact campus setting, but Richmond rental choices spread well beyond the blocks nearest campus. A good decision is rarely about finding the lowest advertised rent. It is about matching location, lease structure, property condition, and transportation to the way you will actually live for the next 10 to 12 months.

    Start With Your Real Monthly Housing Cost

    Advertised rent is only the starting point. Ask for a written breakdown of what is included and what is billed separately. In many rentals, tenants may be responsible for electricity, water, sewer, trash, internet, renter’s insurance, parking, and sometimes a monthly administrative or pest-control fee. A house shared by several tenants can also have a very different utility profile than an apartment with newer systems and better insulation.

    Build a monthly ceiling before touring. Include rent, expected utilities, transportation, groceries, and a reserve for move-in costs. The security deposit, first month’s rent, application fee, utility deposits, furniture, and moving supplies can make the first month materially more expensive than the months that follow.

    If parents are contributing or co-signing, have the financial conversation early. A guarantor may be responsible for more than one student’s share of rent. In a joint lease, one roommate’s missed payment can become everyone else’s problem, depending on the lease language.

    Choosing an Area for EKU Off Campus Housing

    Richmond is not one uniform rental market. The right area depends on whether walking to campus, keeping a car, working off campus, or living with roommates matters most.

    Near campus and downtown Richmond

    Housing near EKU and downtown can appeal to renters who want a shorter campus trip and easier access to restaurants, services, and university activity. The trade-off may be older housing stock, more varied maintenance histories, limited off-street parking, or smaller floor plans. Older homes can be appealing and perfectly functional, but they deserve a closer look at windows, heating and cooling, drainage, electrical outlets, and laundry arrangements.

    Do not assume a listing described as close to campus is an easy walk in every season or at every hour. Drive or walk the actual route. Note sidewalks, crossings, lighting, hills, and the time required with a backpack, groceries, or bad weather.

    Eastern Bypass and retail-oriented corridors

    Apartment communities and newer rental options along the Eastern Bypass and Richmond’s commercial corridors often make sense for renters who drive, work part-time, or want convenient access to groceries and daily services. These locations can offer more predictable parking and modern layouts, but the campus commute may be less convenient without a car.

    For these properties, ask whether parking is assigned, whether guests need permits, and whether towing is actively enforced. A unit with two bedrooms is not automatically designed for two vehicles.

    Residential areas farther from campus

    A house or duplex farther from EKU can provide more space, a yard, or a quieter separation from campus life. It can also create a transportation dependency. Calculate the commute rather than treating it as an afterthought. Fuel, maintenance, insurance, and the inconvenience of moving a car for every errand can outweigh a modest rent difference.

    Avoid broad neighborhood labels or assumptions. Evaluate the specific property, the route you will use, the lease terms, and your own daily schedule. That is more useful than a generalized ranking of one part of Richmond against another.

    Read the Lease Like It Is a Financial Document

    Because it is one. A lease governs far more than rent due dates. Before signing, confirm the lease start and end date, renewal terms, late fees, notice requirements, guest rules, pet rules, parking rules, maintenance procedures, and the policy for subletting or replacing a roommate.

    The most consequential question for many EKU renters is whether the lease is joint and several or individual by bedroom. Under a joint lease, the landlord may generally seek the full amount due from any tenant named on the agreement. An individual lease can limit that exposure, but it may carry a higher rent or different utility structure. Neither arrangement is automatically better. It depends on how well you know your roommates and how much financial risk you are willing to accept.

    Pay close attention to automatic renewal provisions. Some leases require notice 30, 60, or more days before the end date if you do not intend to renew. Missing that deadline can reduce your options for the following year.

    Ask how maintenance requests are submitted and what qualifies as an emergency. Then test the unit before move-in. Run faucets, flush toilets, operate appliances, check every outlet you can reasonably access, and look under sinks. Sewer first, always: slow drains, recurring odors, water staining, or soft flooring near bathrooms deserve documentation before keys change hands.

    Tour for Condition, Not Just Layout

    A staged model unit or a quick showing can hide operational details. During a tour, assess the actual unit you would lease whenever possible. Look for water marks on ceilings, damaged screens, loose handrails, window operation, visible pests, and evidence of rushed repairs. Notice whether doors close properly and whether bedrooms have practical storage and outlets.

    For a house, inspect the exterior as well. Gutters, grading, steps, porches, exterior lighting, and the condition of driveways affect daily living. In Richmond’s wet periods, drainage is not cosmetic. Water that is not directed away from a building has a way of becoming an interior problem.

    At move-in, take dated photos and video of every room, including existing damage, appliance condition, and meter readings where applicable. Submit the landlord’s move-in checklist promptly and retain a copy. This is not adversarial. It creates a clear record when the security deposit is reconciled later.

    Roommates Need Written Ground Rules

    A compatible friend is not necessarily a compatible roommate. Before applying together, discuss budgets, visitors, cleaning, pets, overnight guests, parking, noise, shared purchases, and what happens if one person wants to leave early.

    Put your agreement in writing, even if it is informal. Decide how utilities will be divided, whose name is on each account, and when reimbursements are due. If one roommate is the sole account holder for internet or electricity, the others should understand the consequence if payments are late.

    The same principle applies to furnishings. A shared living-room sofa is simple until the lease ends. Clarify who owns what before money changes hands.

    Timing Matters More Than Most Renters Expect

    Richmond’s student-oriented rental cycle can tighten well before the next academic year begins. Waiting until summer may produce a few opportunities, but it can also mean fewer layouts, less choice in roommate configurations, and more pressure to sign quickly. Start researching early enough to compare several properties, not merely accept the first available unit.

    That does not mean signing sight unseen months in advance is always wise. If you are relocating from outside Kentucky, request a live video tour of the exact unit, read the lease before paying a nonrefundable fee, and verify who manages the property. Dated information matters. A review from years ago or an old online listing tells you less than current lease terms, current photos, and a direct answer about the unit you are being offered.

    When Renting May Not Be the Only Option

    For a typical undergraduate timeline, renting is usually the cleaner choice. Buying a condo, townhome, or small house can introduce financing costs, maintenance exposure, resale risk, and management obligations that do not fit a short stay.

    The analysis changes for a household planning to remain in Richmond for several years, a faculty or staff relocation, or a family considering housing for multiple students over time. In those cases, compare ownership costs against rent with conservative assumptions for repairs, insurance, taxes, vacancy, and resale. A property should work as a home first and an investment only after the numbers have been sourced, dated, and interpreted.

    Marcos Gil Realty can provide local housing guidance for buyers and relocating households whose EKU connection extends beyond a single lease term.

    The right Richmond rental should feel manageable after move-in, not merely exciting on tour day. Give yourself enough time to inspect the property, read every obligation, and price the full monthly commitment. That discipline leaves more room for the part of college housing that should matter most: having a dependable place to come home to.

  • How to Inspect Historic Homes Before You Buy

    How to Inspect Historic Homes Before You Buy

    A historic home can make an ordinary showing feel decisive: heart-pine floors, tall windows, original millwork, a front porch that belongs to the street rather than the driveway. But knowing how to inspect historic homes means looking past the details that photograph well. The question is not whether an older house has quirks. It will. The question is whether its systems, structure, drainage, and past repairs support the price, your intended use, and the work ahead.

    In Central and Eastern Kentucky, that work often begins below grade. Many older Lexington and Richmond homes sit on aging sewer laterals, stone or early concrete foundations, and sites where decades of water management have been improvised one repair at a time. A period-appropriate restoration can be worthwhile. An unpriced infrastructure problem is not character.

    How to Inspect Historic Homes Before the General Inspection

    Start during the showing, before emotion outruns observation. Walk the exterior slowly from the street to the rear lot. Look at roof lines, gutters, downspouts, grading, retaining walls, porch columns, masonry joints, and the condition of painted wood. Water is the common thread. It enters through failed roofs and flashing, migrates through neglected gutters, pools against foundations, and damages framing long before a room looks compromised.

    Pay attention to the ground around the house. Soil should generally move water away from the foundation, not toward it. Downspouts that empty at the base of a wall, low spots beside the house, stained foundation masonry, and damp basement odors all deserve follow-up. In Kentucky’s freeze-thaw cycles and heavy rain events, a modest drainage issue can become a persistent basement or crawlspace problem.

    Inside, use your senses without trying to become the inspector. Does the house smell damp, heavily fragranced, or freshly painted in only one location? Are there stains at ceiling corners, bubbling plaster, uneven flooring, or doors that no longer latch? Each can have an ordinary explanation. Together, they create a pattern worth investigating.

    Original plaster deserves a careful reading. Fine cracking can be normal in a house that has settled over a century. Broad cracks, separation from lath, recurring staining, or a wall that feels loose may point to moisture, movement, or deferred repair. Do not assume drywall over old walls means the issue was resolved. Sometimes it merely means it was covered.

    Put Structure and Water Ahead of Cosmetic Work

    Historic houses were built with materials and methods that differ substantially by era. A 1910 foursquare, a Victorian cottage, and a mid-century ranch may all be considered older homes, but they call for different questions. The inspection should identify what is original, what has been altered, and whether the alterations were competently executed.

    Foundation evaluation is especially important. Stone foundations can perform well for generations when mortar, drainage, and ventilation are maintained. Problems arise when hard modern mortar traps moisture in softer historic masonry, when walls bow under soil pressure, or when prior owners have patched movement without addressing its cause. Ask the inspector to distinguish cosmetic cracking from active displacement. If conditions warrant it, bring in a structural engineer rather than relying on a broad verbal opinion.

    The roof should be evaluated as a system, not just by age. Ask about remaining life, flashing at chimneys and dormers, ventilation, visible decking condition, and any evidence of past leaks in the attic. Slate, standing-seam metal, and wood shingles may be historically appropriate and long-lived, but repair requires specialists and costs can be materially different from an asphalt replacement. That is not automatically a reason to walk away. It is a reason to budget accurately.

    Porches also deserve more than a quick glance. Their columns, railings, decking, steps, and roofs are exposed on every side. Rot at the bottom of a column may be repairable; widespread framing deterioration can become a substantial project. Confirm whether a previous repair preserved load-bearing function or simply improved the appearance from the sidewalk.

    Sewer First, Always

    For older homes connected to public sewer, a sewer scope is a separate due-diligence item, not an optional add-on. Sewer first, always. A standard home inspection may identify slow drains or visible plumbing concerns, but it does not show the condition of the lateral line running from the house to the public connection.

    Older properties may have clay tile, cast iron, Orangeburg, or mixed piping, sometimes with roots at joints, bellies, offsets, cracks, or partial collapses. A line can appear functional during a brief inspection and still be near the end of its useful life. The scope should include video, location information where possible, and a written assessment of recommended repair or replacement.

    If the property uses a septic system, the process changes. Ask for system records, confirm the location and capacity of the tank and field, and arrange a septic inspection suited to the system type. For rural historic homes, also verify the water source, well components, pump age, water quality, and any shared-road or access obligations. A beautiful farmhouse without clear utility and access facts is not yet a fully understood purchase.

    Inspect Electrical, Plumbing, and Heating as Working Systems

    Period details should never distract from life-safety systems. Older electrical panels, limited service capacity, ungrounded outlets, knob-and-tube wiring, cloth-covered conductors, or amateur additions need direct evaluation by a licensed electrician. Some older wiring can remain serviceable in limited conditions; insurers and lenders may take a different view, particularly when renovation plans involve new loads, electric vehicle charging, or a larger HVAC system.

    Plumbing requires the same discipline. Galvanized supply lines can corrode internally and reduce water pressure. Cast-iron drains may be nearing replacement age. Look for active leaks beneath sinks, evidence of past water damage around bathrooms, and shutoff valves that actually operate. If a home has been renovated, ask whether supply and drain lines were replaced throughout or only where walls were opened.

    Heating and cooling should be assessed for condition, capacity, and distribution. Historic homes often have rooms added over time, and those additions may be uncomfortable because ductwork, insulation, or equipment sizing was never reconsidered. A newer furnace sticker is useful information, but it is not the whole answer. Ask whether the system heats and cools the entire house evenly and whether the electrical service can support future upgrades.

    Understand Windows, Lead Paint, and Preservation Rules

    Original wood windows are often treated as a binary choice: replace them all or keep them at any cost. The better answer depends on their condition, energy goals, historic value, and repairability. Well-maintained original windows, combined with weatherstripping and storm windows, can perform better than many buyers expect. Full replacement may make sense where units are badly deteriorated, but it can change the home’s appearance and may be restricted in designated historic districts.

    Lead-based paint is common in homes built before 1978. The federal disclosure requirement is familiar to many buyers, but the practical issue is condition. Intact painted surfaces present a different risk profile than peeling trim, friction surfaces around windows and doors, or renovation work that creates dust. If children will live in the home or major work is planned, seek appropriate testing and use contractors trained in lead-safe practices.

    Before committing to exterior changes, verify whether the property is within a local historic district or subject to neighborhood preservation standards. Rules may affect windows, doors, roofing materials, siding, additions, and even paint-related exterior work. These standards protect streetscape value, but they can add review time and limit inexpensive substitutions. Buyers should understand that trade-off before inspection deadlines pass, not after a contractor has been hired.

    Read the Renovation History, Not Just the Finish Schedule

    Ask for permits, invoices, warranties, contractor information, and before-and-after photos when they exist. The goal is not to demand a perfect archive. It is to determine whether significant work was planned, permitted where required, and completed with a coherent approach.

    Be cautious with renovated historic homes that look uniformly new but offer little documentation. Fresh cabinetry and polished fixtures can coexist with old wiring behind walls, unresolved drainage, or a basement that was cosmetically finished around moisture problems. Conversely, a house with visible age and documented stewardship may be the more dependable opportunity.

    Your inspection period should give you time to obtain specialist opinions where the general inspection raises questions. That may include a structural engineer, roofer, chimney professional, electrician, plumber, HVAC contractor, pest specialist, sewer-scope provider, or preservation-minded window contractor. Use the findings to decide whether to proceed, renegotiate, request repairs, or reserve capital for work after closing. The right path depends on the home’s price, rarity, condition, and your appetite for management.

    A well-bought historic home is not one without defects. It is one whose defects are sourced, dated, and interpreted before you own them. Keep the inspection focused on water, structure, sewer, safety, and documentation, then let the architectural details earn their place in the decision.

  • What Is a Sewer Scope Inspection for Homebuyers?

    What Is a Sewer Scope Inspection for Homebuyers?

    A polished kitchen, fresh paint, and a clean general inspection can still leave one expensive question unanswered: what is a sewer scope inspection, and what is happening below the ground between the house and the public sewer? For buyers, especially those considering older Lexington or Richmond homes, the answer can materially change the cost and terms of a purchase. Sewer first, always.

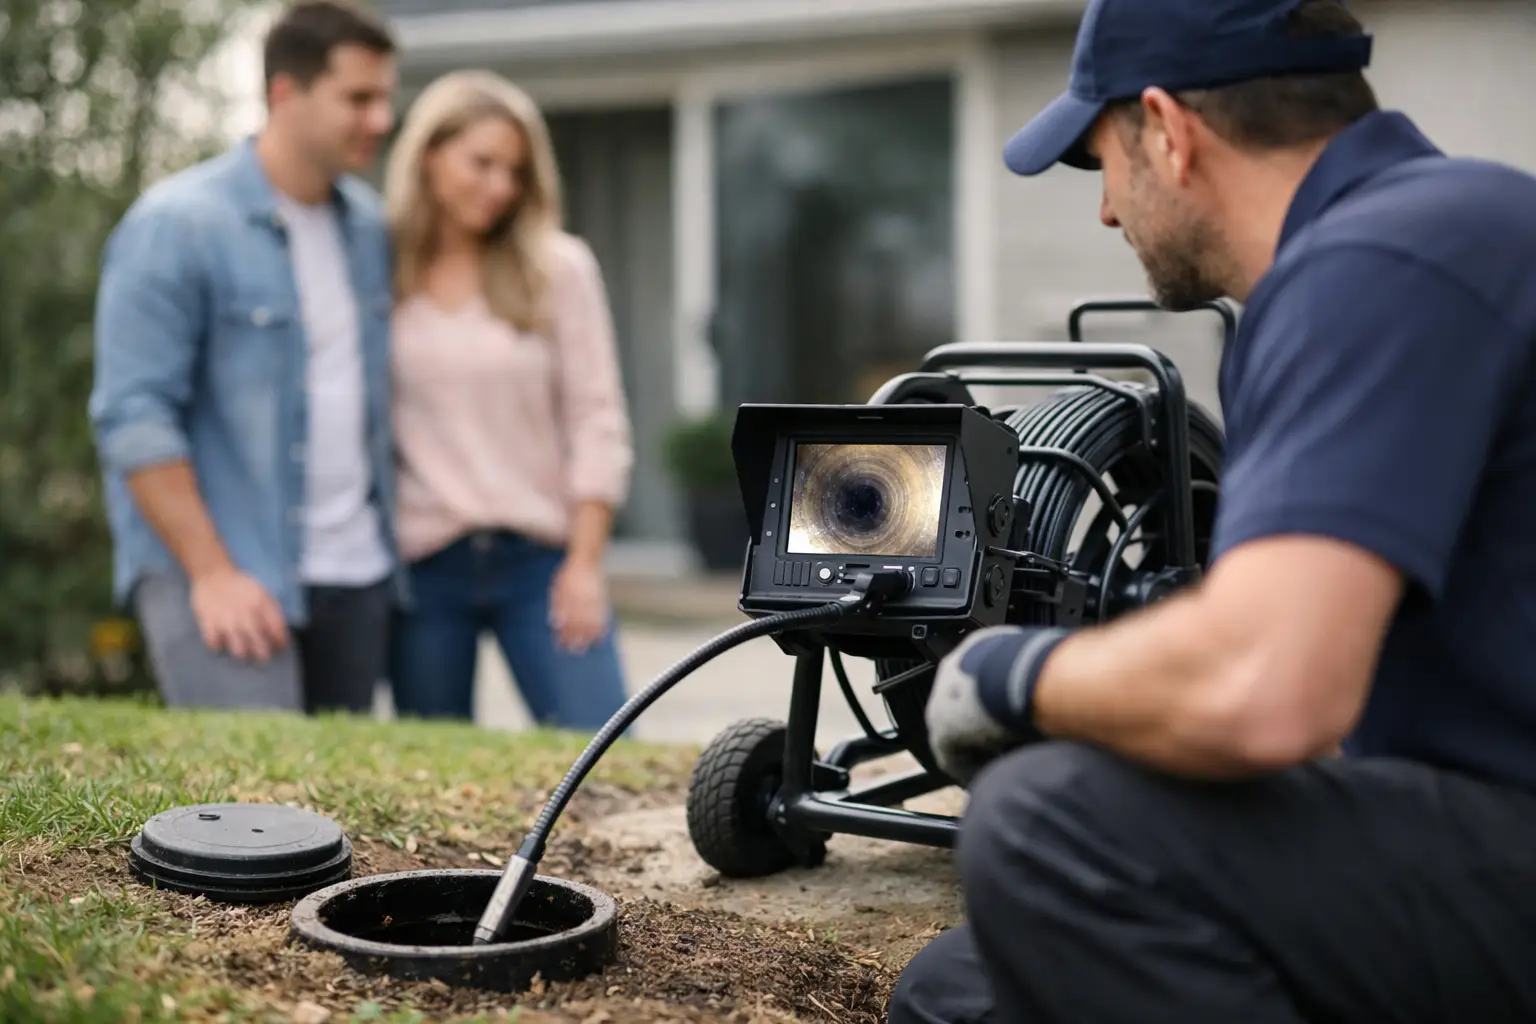
    A sewer scope inspection uses a specialized waterproof camera to view the private sewer lateral – the pipe that carries wastewater from the home to the municipal sewer connection. A technician feeds the camera through an accessible cleanout, records the line, and identifies visible defects, blockages, and pipe conditions that a standard home inspection cannot see.

    It is not glamorous due diligence. It is often some of the most useful due diligence on the property.

    What a Sewer Scope Inspection Actually Covers

    The camera travels through the drain line, typically from a cleanout near the home or in the basement, toward the street connection. The technician watches a live feed and usually provides video, photos, a written finding, or some combination of the three. Good reporting identifies the approximate location of a concern, the direction of the camera, and the distance from the access point.

    The scope is intended to evaluate the condition of the visible sewer lateral. It can reveal roots, separated joints, crushed sections, heavy buildup, standing water, poor connections, and obsolete pipe materials. It may also show whether the line appears to be flowing normally at the time of inspection.

    That last phrase matters. A camera is a visual inspection, not a guarantee that the line will never back up. It may not reveal every defect behind a heavy deposit, a section obscured by water, or a problem that only appears under unusual volume. Still, it gives a buyer far more evidence than assuming the pipes are fine because the toilets flushed during a showing.

    Why the General Home Inspection Is Not Enough

    A capable home inspector will test fixtures, observe drainage, and note obvious signs of plumbing trouble. They do not typically run a camera through the buried lateral as part of a standard inspection. The underground line may extend dozens of feet beyond the foundation, through landscaping, driveways, sidewalks, or public right-of-way areas.

    The home can look entirely sound while that line is compromised. A slow drain may be a minor maintenance issue. It may also be the first signal of root intrusion or a deteriorating clay line. By the time sewage backs up into a lower-level bathroom, the repair conversation is no longer theoretical.

    For a purchase, the distinction is straightforward: the general inspection tells you how the home is performing at the surface. A sewer scope helps establish what is happening in one of its least visible and potentially most disruptive systems.

    Common Findings in Central and Eastern Kentucky Homes

    The age of a home is a useful screening tool, but it is not the whole story. A newer house can have construction debris, a poorly aligned connection, or damage from settlement. An older house may have a well-maintained line that still has years of service left. The camera evidence, sourced and dated, should lead the decision.

    In Lexington, Richmond, and established small-town neighborhoods across the corridor, these are the findings that most often deserve attention:

    • Root intrusion: Tree roots can enter at joints or small cracks, particularly in older clay or cast-iron lines. Roots may be cleared, but repeated intrusion usually points to a joint or pipe condition that needs a longer-term plan.
    • Offset or separated joints: Sections of pipe shift over time due to settlement, age, or installation issues. Waste can catch at the opening, increasing the chance of blockage.
    • Bellies or standing water: A low section of pipe holds water rather than draining fully. The severity depends on the amount of standing water, pipe material, flow, and whether solids are collecting there.
    • Cracks, breaks, or a collapse: These findings can range from localized repairs to full replacement. The exact location, depth, access, and surface restoration needs drive the cost.
    • Orangeburg, clay, or deteriorating cast iron: Older materials are not automatic deal-breakers, but they require informed budgeting. Orangeburg, a fiber-based pipe used in parts of the mid-20th century, is particularly worth evaluating closely because it can deform and fail with age.

    A report that merely says “roots present” is incomplete for negotiation purposes. Buyers need to know how extensive the roots are, whether the line is backing up, whether the pipe is visibly damaged, and where the concern sits. A defect under open lawn is a different project from one beneath a driveway, mature landscaping, or a finished addition.

    When Should a Buyer Order a Sewer Scope?

    For many properties connected to public sewer, the practical answer is during the inspection period. The cost is modest compared with the cost of replacing a lateral, and it gives the buyer time to request repairs, negotiate a credit, revise the offer strategy, or walk away when the contract permits.

    A scope is especially sensible when the home is older, the seller has limited maintenance history, large trees sit near the route to the street, drains have been slow, or the property has a finished basement. It is also prudent when a home has been renovated extensively. New kitchens and baths do not necessarily mean the buried sewer line was replaced.

    Investors should be particularly disciplined. A sewer failure can interrupt a tenant’s occupancy, create an emergency repair, and damage returns during the first year of ownership. For a Red River Gorge cabin or rural property, first determine whether the home is on public sewer at all. A sewer scope does not replace a septic inspection, tank evaluation, or assessment of the drain field. Those are separate systems with separate risks.

    How to Read the Results Without Overreacting

    Not every unfavorable observation requires a seller-funded replacement. This is where judgment matters.

    A few fine roots in an otherwise intact, flowing line may justify cleaning and periodic maintenance rather than a demand for a new lateral. A moderate belly may deserve a contractor opinion and a repair reserve, particularly if the line is flowing and there is no evidence of recurring blockage. A visible collapse, severe offset, or extensive deterioration is a different category. Those conditions deserve a qualified sewer contractor’s written repair recommendation before the inspection deadline expires.

    Ask for the video, not just a verbal summary. Confirm the footage is from the subject property, and review whether distances were documented. If the technician cannot access the line because there is no cleanout or because the opening is inaccessible, that is itself useful information. Installing a cleanout may be a worthwhile request or future improvement, since it provides a practical point for maintenance and emergency service.

    Buyers should also separate immediate health or function concerns from future capital planning. A line can be serviceable today yet nearing the end of its expected life. That does not always mean the seller must replace it. It does mean the purchase price, cash reserves, and ownership plan should reflect the risk honestly.

    What Findings Mean for Negotiation

    A sewer scope is not a tool for reopening every negotiated point. It is evidence for addressing a documented condition that was not visible during normal review. The cleanest path is usually to obtain a clear contractor estimate, understand whether repair or replacement is recommended, and compare that work with the property’s price and competing options.

    Depending on the contract, the parties may agree to a repair before closing, a credit, a price adjustment, or no change at all. Credits can give a buyer control over the contractor and timing, but they also require enough cash after closing to complete the work. Seller repairs can reduce immediate expense, yet buyers should understand the scope of work, permits if applicable, and whether pavement, landscaping, or other surfaces will be restored.

    Responsibility can become less clear near the public connection. In many locations, the owner is responsible for the private lateral, sometimes extending to the point of connection, but local rules and the precise location of the defect matter. Do not rely on assumptions. Verify the municipal utility’s standards and obtain a contractor’s assessment before assigning responsibility in a negotiation.

    A Small Inspection With a Large Practical Value

    The best time to learn about an aging sewer lateral is before closing, when there are still choices. A camera inspection cannot make an older property new, and it should not erase the value of a well-located home with strong bones and a manageable repair plan. It simply replaces guesswork with a clearer record.

    For Kentucky buyers, that is the point of disciplined due diligence: understand the condition beneath the landscaping, price the risk appropriately, and move forward with eyes open rather than hoping the next flush does not become the first emergency.

  • New Construction Contract Kentucky Guide

    New Construction Contract Kentucky Guide

    A model home can make a new build feel settled long before it is legally or physically complete. The new construction contract Kentucky guide buyers need begins with that distinction: the builder’s sales process is designed to move you from lot selection to deposit, while the contract determines what you are actually buying, when you must perform, and what happens if the build changes course.

    In Central and Eastern Kentucky, the differences can be material. A Lexington infill home, a Richmond subdivision build, a farm-adjacent custom residence in Madison County, and a cabin near the Red River Gorge may all be called new construction. Their utility arrangements, site conditions, lender requirements, access issues, and construction timelines can be very different. The contract should reflect the property in front of you, not merely the builder’s standard form.

    Start With the Builder’s Contract, Not the Model Home

    Most production and semi-custom builders use their own purchase agreements. Unlike a resale transaction, where the parties often begin with a familiar statewide form and negotiate around it, a builder contract is usually drafted for the builder’s process. It may limit the buyer’s remedies, set narrow cancellation rights, define allowances broadly, and give the builder substantial discretion over substitutions and completion timing.

    That does not make the contract unreasonable. It does mean the buyer should read it as an operating document, not a brochure attachment. The floor plan, included-features sheet, lot exhibit, upgrade selections, financing addendum, warranty materials, and community documents should all be identified and retained. If a sales representative says a feature is included, ask where it appears in writing. A conversation about a covered patio, quartz level, appliance package, retaining wall, or fence has little value if the contract and exhibits say otherwise.

    Before signing, separate three categories: what is included in the base price, what is an upgrade with a fixed price, and what is an allowance or a future decision. Allowances deserve extra attention. They can be appropriate for lighting, tile, landscaping, or finishes that have not been selected. But an allowance is not a guaranteed final cost if actual selections exceed it. Ask who approves overages, when they are due, and whether labor, delivery, taxes, and installation are included.

    The New Construction Contract Kentucky Buyers Should Review Closely

    A purchase price is only one line of the transaction. The most consequential provisions often sit in the timelines, contingencies, and remedy language.

    Deposit and earnest money terms

    Know the deposit amount, when it becomes nonrefundable, and who holds it. Some builders use an earnest money structure that becomes nonrefundable shortly after signing, even when construction has not started. Others permit refunds only for a narrowly defined financing failure. A large deposit can be sensible for a highly customized home, but it changes the buyer’s exposure if employment, lending, or life plans shift.

    Ask whether the deposit is applied to the purchase price, whether upgrade deposits are treated differently, and what happens if the builder cannot deliver the home. The contract should be clear about the buyer’s remedy if construction is abandoned, materially delayed, or completed in a substantially different form than promised.

    Financing is not the same as preapproval

    A lender’s preapproval is a useful first screen, not a guarantee that financing will be available at closing. With new construction, months can pass between contract and loan application completion. Credit changes, debt-to-income ratios, rates, appraisal conditions, insurance costs, and employment changes can all affect approval.

    Many builders offer incentives for using a preferred lender or title company. The incentive may be worthwhile, particularly when it offsets closing costs or provides a pricing concession. Still, compare the total loan cost and the contractual protections. The right question is not whether the preferred lender is good or bad. It is whether the offer is competitive and whether the financing contingency gives you a realistic path out if the loan does not come together.

    Pay close attention to any financing deadline. A contract can require the buyer to apply within a short window, provide documents promptly, and accept a loan within stated terms. If rates move beyond your comfort level, a rate-lock strategy and a written conversation with the lender matter more than optimistic assumptions.

    Construction timing and the meaning of completion

    Builders commonly provide an estimated completion date rather than a guaranteed one. Weather, labor availability, material delays, permitting, utility work, and change orders can extend a schedule. In Kentucky, prolonged rain can affect grading and exterior work; on rural or sloped sites, driveway, drainage, septic, or utility coordination can add another layer.

    Read how the agreement defines completion. Is it certificate of occupancy, substantial completion, final municipal sign-off, or a date selected by the builder after notice? Also review the outside completion date, if one exists, and the buyer’s remedy if it is missed. A flexible estimate is understandable. An open-ended obligation with no meaningful buyer protection deserves closer review.

    Avoid scheduling a lease termination, movers, school transfer, or sale of your current home solely around a verbal target date. Build time and financial contingency into the larger move plan.

    Changes, substitutions, and site conditions

    The contract should address what happens when a specified material is unavailable or a field condition requires a change. Builders need reasonable substitution rights. A discontinued cabinet pull should not stop a build. But the agreement should distinguish minor substitutions from material changes to layout, square footage, exterior finish, mechanical systems, lot grading, or included amenities.

    For a homesite, do not treat the lot as scenery. Review easements, drainage areas, utility locations, sidewalks, retaining walls, shared drives, and any conservation restrictions. In parts of Central Kentucky, sewer availability and capacity should be confirmed early. Where public sewer is not available, septic suitability, reserve areas, and access easements deserve the same attention. Sewer first, always.

    A home can be beautifully finished and still have a backyard constrained by drainage swales, a utility pedestal in the wrong place, or a slope that makes fencing expensive. The site plan and recorded restrictions often tell that story better than the sales center does.

    Inspections Are Still Worth Having

    A new home should be inspected. Municipal code inspections and builder quality-control reviews serve different purposes from an independent inspector working for the buyer. The local jurisdiction is checking code compliance at specific stages. Your inspector is evaluating visible workmanship, function, safety concerns, and conditions that may warrant correction before closing.

    The ideal inspection strategy depends on the build and the builder’s access rules. For a longer build, a pre-drywall inspection can reveal framing, plumbing, electrical, and mechanical issues before walls are closed. A final inspection shortly before closing documents items for the punch list. If pre-drywall access is not permitted, do not assume you have no options. Confirm the policy before contract signing and plan for a thorough final inspection.

    The contract should make clear whether an inspection contingency exists and what it allows. Some builder forms permit an inspection but not a termination right, limiting the buyer to a repair request. Others require the buyer to submit concerns by a short deadline. That may be acceptable when the builder has a credible correction process, but it should be understood before the deposit is committed.

    At the final walk-through, test more than cosmetic details. Operate windows and doors, run faucets, check appliances, confirm heating and cooling, inspect floors in natural light, and compare installed finishes against signed selections. Photograph unresolved items and obtain a written punch-list process with target dates.

    Warranties, Closing Costs, and the Post-Closing Record

    Most new homes come with some form of builder warranty, often structured around different periods for workmanship, systems, and structural elements. Read the actual warranty, not just the summary. Look for exclusions involving settling, landscaping, moisture, grading, appliances, owner maintenance, and third-party products. Understand the notice procedure. A warranty claim often requires written notice within a defined period and may include mediation, arbitration, or other dispute provisions.

    Closing costs also need a line-by-line review. New construction can involve lender fees, title charges, prepaid taxes and insurance, HOA initiation fees, transfer-related charges, and utility deposits. Incentives may cover some costs but not all. If the builder quotes a closing-cost credit, confirm its permitted uses with the lender and obtain the estimate in writing.

    After closing, preserve the contract, signed plans, change orders, selection sheets, surveys, warranty documents, appliance manuals, permits, and final invoices. That file helps with warranty requests, future maintenance, insurance questions, and eventual resale. A later buyer may care deeply about what was built, who built it, and whether improvements were permitted and documented.

    Use Counsel Early When the Risk Is Meaningful

    A REALTOR® can help compare the contract against the market, organize due diligence, coordinate inspections, and keep the transaction moving. Legal interpretation is different work. If the agreement includes substantial nonrefundable money, broad waiver language, arbitration requirements, a custom-build scope, land complications, or a home-sale contingency, having a Kentucky real estate attorney review it before signing is usually money well spent.

    This is especially true for acreage, rural builds, custom homes, and investment properties. A cabin intended for short-term rental may need a different review of restrictions, road maintenance, utility capacity, and operational assumptions than a primary residence in an established subdivision. The contract cannot solve a bad site or an unworkable business plan, but it can keep those risks visible before they become expensive.

    A well-run new construction purchase is not about distrusting the builder. It is about making the promises, choices, deadlines, and remedies visible on paper. Buy the home you can document, inspect, finance, and operate with confidence.