Marcos Gil, REALTOR® · Keller Williams Commonwealth

Brokered by

The Journal

  • Kentucky Termite Letter: The Licence Behind the Signature

    Marcos Gil Realty · Due Diligence

    A Kentucky termite letter is only as good as the licence behind the signature — and Kentucky sets that bar in statute: a registered structural pest management company must carry liability insurance of at least $1,000,000, and the operator who holds its licence needs two years of verified experience or a degree in entomology. Both are checkable in a public state database before you close.

    What licence does a Kentucky termite inspection rest on?

    Two layers: the company must be registered with the Kentucky Department of Agriculture as a structural pest management company, and the individual doing the work holds an operator’s or applicator’s licence.

    The Kentucky Revised Statutes split those deliberately. KRS 217B.520 sets who may hold the operator’s licence. KRS 217B.522 requires an applicator’s licence for an employee of a structural pest management operator. And KRS 217B.516 governs what the company itself must prove before the department will register or renew it at all.

    How much insurance must the company carry?

    Not less than one million dollars in liability coverage, maintained at that level at all times during the registration period — the department cannot issue or renew the registration without it.

    RequirementWhat KRS 217B.516 says
    Minimum liability insuranceNot less than $1,000,000, maintained at all times during the registration period
    Notice of cancellation or reductionDepartment notified no less than 10 days beforehand
    Deductible ceilingA deductible clause may be accepted only if it does not exceed $5,000
    Unsatisfied prior deductibleDeductible clause not accepted unless a security bond or further insurance covers it
    If the surety lapsesRegistration is cancelled; unlawful for any employee or agent to engage in structural pest management until reinstated
    Liability for damageCompliance with the chapter does not relieve anyone of liability for damage caused by pesticide use
    Source: KRS 217B.516, effective June 29, 2021. Kentucky Legislative Research Commission statute database, currency date 11/05/2026.

    If the insurance lapses, the registration goes with it — and the statute makes it unlawful for the company’s own employees to keep working until it is back in compliance. That is the risk a lapsed vendor quietly passes to a closing.

    Who qualifies to hold the operator’s licence?

    A legal resident of the United States, at least eighteen, with at least two years of verified experience in structural pest management — or a degree in entomology, which qualifies with no experience at all.

    KRS 217B.520 names the degree route precisely: a bachelor’s, master’s or doctoral degree in entomology from an accredited college or university qualifies an applicant with no experience, and the educational background must be verified with official transcripts from the granting institution. The two-year experience route requires verification too. Those are the only paths the section lists.

    How do I verify the company before closing?

    The Department of Agriculture publishes two free public lookups: a licensed applicator search for individuals, and a pest control company directory for firms.

    In my experience this is the least-used sixty seconds in a Kentucky closing. The termite letter arrives as a scan, it gets stapled to the file, and nobody reads the name on the signature line. The name is the thing worth checking: the letter is a professional opinion, the opinion is backed by a credential, and the credential is public. Where a lender requires the letter, the letter’s weight depends entirely on the registration standing behind it — so a buyer who looks the company up has done something a lender’s checklist does not actually do for them. If the company does not appear in the directory, that is a question for the listing side before the inspection period closes, not after.

    This sits in the same family as the other credentials Kentucky attaches to a transaction: see the certification a Kentucky radon test rests on and which home inspections Kentucky’s licensing law exempts. For what the seller must put in writing, start with the Kentucky seller disclosure form and its clocks.

    Is a termite letter required to buy a house in Kentucky?

    Kentucky statute does not require one of a buyer; lenders and loan programmes commonly do. KRS Chapter 217B governs who may perform the work, not when a letter is ordered.

    Can an entomology graduate inspect with no field experience?

    For the operator’s licence, yes. KRS 217B.520 states that a bachelor’s, master’s or doctoral degree in entomology qualifies an applicant with no experience, verified by official transcripts.

    What happens if the company’s insurance is cancelled mid-job?

    Under KRS 217B.516 the department must be notified at least ten days before a cancellation or reduction, and if the surety is not replaced the registration is cancelled and work must stop until it is reinstated.

    Last updated 2026-11-06.

    By Marcos Gil, REALTOR® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209.

  • Lexington Versus Richmond Housing: Which Fits?

    Lexington Versus Richmond Housing: Which Fits?

    A move from Lexington to Richmond can change far more than a monthly payment. It may mean trading a shorter walk to restaurants and major employers for more land, a newer home, or a different pace of daily life. The useful question in Lexington versus Richmond housing is not which city is universally better. It is which location supports the way you will live, commute, maintain property, and eventually sell.

    Both markets sit within a practical Central Kentucky orbit, yet they operate on different rhythms. Lexington is the region’s larger employment, medical, education, and cultural center. Richmond is a university city and Madison County seat with its own employment base, a strong connection to Eastern Kentucky, and an increasingly familiar role for households seeking value within reach of Lexington.

    Lexington versus Richmond housing at a glance

    Lexington generally offers more neighborhood choice, greater buyer depth, and a broader range of polished in-town housing. Richmond often offers more square footage, land, or newer construction for a similar budget, particularly once a buyer looks beyond the city core. That broad distinction is real, but it can become misleading quickly.

    A renovated home near Lexington’s established employment centers is not directly comparable to a large Richmond subdivision home, just as a Richmond acreage tract is not comparable to a small Lexington lot with public utilities. Price per square foot is a starting point, not a verdict. Condition, lot utility, location, updates, school assignment, flood exposure, and financing eligibility all deserve equal weight.

    For buyers, the choice commonly turns on three practical questions: How often must you be in Lexington? What kind of property do you actually want to maintain? And how much resale flexibility do you want when the time comes to move again?

    Lexington: depth, access, and a wider resale audience

    Lexington appeals to buyers who want proximity to the University of Kentucky, major hospitals, downtown offices, restaurants, airport access, and established neighborhood amenities. It contains a remarkably wide housing inventory for one market: historic homes, infill construction, townhomes, suburban subdivisions, horse-country estates, condominiums, and acreage at the edge of town.

    That variety creates more choices, but it also requires sharper comparisons. Two homes a mile apart may belong to very different buyer pools because of school patterns, traffic routes, preservation constraints, lot sizes, or the degree of renovation needed. A charming older home can be a sound purchase, but charm does not replace updated electrical service, drainage control, roof life, or a clear understanding of prior additions.

    Lexington’s deeper demand base can support liquidity, especially for well-positioned homes that are correctly prepared and priced. Professionals, university-affiliated buyers, medical households, relocators, and move-up families all participate in the market. That does not mean every Lexington listing sells quickly or commands a premium. Overpricing, deferred maintenance, awkward floor plans, and poor presentation are still punished.

    For a seller, Lexington often rewards precise positioning. The strongest strategy is not simply to point to a nearby sale, but to explain why that sale is or is not relevant. Valuation should be in writing, with comparable sales sourced, dated, and interpreted rather than copied from a portal estimate.

    The Lexington trade-off

    Access and choice come with competition for desirable homes and, in many cases, a higher entry cost. Buyers may accept a smaller lot, an older property, higher taxes, or a more demanding renovation profile to live closer to the places they use every week. For some households, that is a rational premium. For others, it becomes an expensive compromise they feel after closing.

    Richmond: space, value, and a different operating reality

    Richmond offers a compelling mix of established neighborhoods, newer subdivisions, rural edges, and proximity to Eastern Kentucky destinations. Eastern Kentucky University anchors a meaningful part of the local economy and rental conversation, while the Blue Grass Army Depot also shapes demand for military-connected and civilian households. Richmond is not merely a less expensive version of Lexington. It is a distinct market with its own employment drivers, development patterns, and buyer expectations.

    For many buyers, the first attraction is buying power. A budget that produces a modest home or limited lot in Lexington may reach further in Richmond. That can mean an additional bedroom, a finished basement, a newer build, usable outdoor space, or acreage. The right comparison is not just purchase price. It is the total cost of ownership, including commute time, fuel, insurance, utilities, repairs, and future maintenance.

    Richmond can be especially attractive to households with flexible schedules, remote or hybrid work, local employment, or a genuine preference for more room. It also makes sense for buyers whose lives are oriented toward Madison County, Berea, the Gorge corridor, or Eastern Kentucky rather than daily Lexington appointments.

    The trade-off is that some Richmond properties require more careful utility and site diligence than a buyer expects. On the suburban and rural fringe, verify water source, septic capacity and condition, driveway responsibility, internet availability, drainage, zoning, road access, and any deed restrictions. Sewer first, always. A beautiful home on a large tract can lose its appeal quickly if its operating systems were never properly evaluated.

    The Richmond resale question

    Richmond has real resale demand, but its buyer pool is not identical to Lexington’s. Homes that appeal to local professionals, university households, military-connected buyers, and families seeking space can perform well when they are priced to their actual condition and location. A highly customized rural property, however, may have a narrower audience than a conventional home near services.

    That does not make a specialized property a poor purchase. It means the exit strategy should be considered before the offer. If you expect to sell within three to five years, a home with broad functional appeal, dependable access, and clear maintenance history usually provides more flexibility than a unique property with unresolved site questions.

    The commute is a financial decision, not just a map route

    The Lexington-Richmond drive is manageable for many households, but “manageable” is personal. A buyer commuting two days a week experiences that distance differently from a hospital employee, executive, or parent making daily school and activity runs. Traffic patterns, weather, construction, and the exact location on either end matter more than a generic drive-time estimate.

    Before choosing Richmond for a Lexington-based job, make the trip during the hours you will actually travel. Drive from the specific neighborhood to the actual office, school, hospital, or airport. Then calculate the annual cost in time as well as fuel and vehicle wear. More house is not automatically more value if the commute eliminates the flexibility you wanted the home to provide.

    The reverse is also true. Buyers who choose Lexington only because it feels more central can overpay for access they rarely use. If your work, family, recreation, and long-term plans are centered in Madison County, Richmond may be the more efficient base.

    Investors should separate the stories

    Investors often hear a simplified version of the comparison: Lexington for appreciation and Richmond for cash flow. That is too blunt to guide a purchase. A Lexington duplex near a durable employment or university corridor may have a very different operating profile from a Richmond student rental, a suburban single-family lease, or a rural short-term rental concept.

    Student-oriented property deserves particular discipline in both markets. Verify lease structure, turnover costs, parking, local occupancy rules, property condition, and the distance between the home and the tenant’s actual daily routine. Do not underwrite from advertised rents alone. Review achieved rents, vacancy assumptions, capital expenditures, insurance, property taxes, and management demands.

    For land, cabins, and acreage near the Richmond-to-Gorge corridor, access and utilities can matter more than the view. Confirm deeded access, survey boundaries, restrictions, septic feasibility, water, electric capacity, cellular service, and whether the road is truly suitable for guests, contractors, and emergency vehicles. A property can be marketable and still be operationally difficult.

    A better way to choose between the two

    Start with a written priority order. If convenience to Lexington institutions is first, evaluate Lexington neighborhoods before expanding the search. If land, space, or Madison County roots are first, study Richmond on its own terms rather than treating it as a fallback.

    Then compare specific properties by their full operating reality: condition, utility systems, commute, taxes, insurance, maintenance, neighborhood trajectory, and likely resale audience. The best choice may be a Lexington home that reduces daily friction, or a Richmond home that gives your household room to stay longer. The disciplined answer is rarely found in a citywide median. It is found in how one property performs against your life and your exit plan.

  • Buried Heating Oil Tank at a Kentucky House: What the Law Says

    Buried Heating Oil Tank at a Kentucky House: What the Law Says

    By Marcos Gil, REALTOR®, Keller Williams Commonwealth, KY license 296259

    Illustrative: a rusty oil tank removed during a 2014 debris cleanup in New Jersey. Photo: U.S. Fish and Wildlife Service, public domain. Not a Kentucky property.

    A pipe sticking out of the ground beside an older house may be the fill or vent for a heating oil tank, past or present. Two documents answer the first questions a buyer or seller has: Kentucky’s definition of an underground storage tank, and the Kentucky Real Estate Commission’s seller’s disclosure form.

    Kentucky’s UST definition leaves it out

    KRS 224.60-100(1) defines “Underground storage tank” as “any one (1) or combination of tanks (including underground pipes connected thereto) used to contain an accumulation of regulated substances,” with ten percent or more of the volume below ground. Then: “Such term does not include any:” and a list. Three items on that list matter for a house:

    • (a) “Farm or residential tank of one thousand one hundred (1,100) gallons or less capacity used for storing motor fuel for noncommercial purposes;”
    • (b) “Tank used for storing heating oil for consumptive use on the premises where stored;”
    • (i) “Storage tank situated in an underground area (such as a basement, cellar, mineworking, drift, shaft, or tunnel) if the storage tank is situated upon or above the surface of the floor.”

    The section applies “As used in KRS 224.60-105.”

    The federal definition matches

    The federal UST rule, 40 CFR 280.12, carries the same exclusion: “Tank used for storing heating oil for consumptive use on the premises where stored.” It defines the two key phrases. “Consumptive use with respect to heating oil means consumed on the premises.” And “On the premises where stored with respect to heating oil means UST systems located on the same property where the stored heating oil is used.”

    Read together, a buried tank that held heating oil burned in the house on the same lot falls outside both definitions. A tank that held motor fuel, or served a different property, is a different analysis.

    What the exclusion doesn’t answer

    The exclusion answers one question: whether the tank is a regulated underground storage tank under these definitions. It doesn’t answer whether the tank leaked, whether anything in the soil needs attention, or what a removal or closure would involve. Those stay UNKNOWN until an environmental professional looks at the specific property.

    What the seller’s disclosure form asks

    On the Kentucky Real Estate Commission’s Seller’s Disclosure of Property Condition (KREC Form 402, 12/2022), Section 11, Hazardous Conditions, item (a) asks: “Are you aware of any underground storage tanks, old septic tanks, field lines, cisterns, or abandoned wells on the property?” The answer boxes are N/A, Yes, No and Unknown.

    The question asks about “any underground storage tanks”; its text doesn’t reference the statute’s exclusions. How to answer it for a specific tank is a question for the seller and their attorney.

    Under 201 KAR 11:121, Section 4(1), a licensee “shall direct the seller-client of a single family residential real estate dwelling, duplex, triplex, fourplex, condominium, or townhouse to accurately complete and sign the Seller’s Disclosure of Property Condition form required by KRS 324.360,” unless the seller refuses and the refusal is documented.

    Questions for the inspection period

    • Is there a fill pipe or vent pipe in the yard or along the foundation?
    • How was the house heated before the current system?
    • What does the seller’s Form 402 say on Section 11(a)?
    • If a tank is suspected, ask an environmental professional which testing fits. Scope and cost: UNKNOWN until they see the property.

    This is general information about Kentucky and federal tank definitions, not legal or environmental advice. An environmental professional and a Kentucky real estate attorney have the final word on a specific property. I’m your agent, not your attorney or environmental consultant.

    Put the tank question on the list

    Buying or selling an older house in Central Kentucky? Call (859) 310-1209. I’ll put the tank question on the inspection-period list.

    Marcos Gil, REALTOR® · Kentucky license №296259
    Keller Williams Commonwealth · 1908 Bryant Rd Ste 250, Lexington, KY 40509
    Principal Broker: Bo Smith · (859) 721-2121
    Equal Housing Opportunity.

  • Kentucky Housing Trends That Move the Market

    Kentucky Housing Trends That Move the Market

    By Marcos Gil, REALTOR®, Keller Williams Commonwealth, KY license 296259

    A statewide headline can obscure more than it reveals. Kentucky housing trends are not one market moving at one speed. A renovated home inside New Circle Road, a single-family home in Richmond, acreage in Madison County, and a cabin near the Red River Gorge may all respond to different buyer pools, financing conditions, and supply constraints.

    That distinction matters when a buyer is deciding how aggressively to offer, a seller is setting expectations before listing, or an investor is underwriting income. The useful question is not whether Kentucky is a buyer’s or seller’s market. It is where the property sits, what condition it is in, who is likely to buy it, and whether its price is supported by recent, comparable sales.

    Kentucky Housing Trends Are Local Before They Are Statewide

    Central and Eastern Kentucky have a connected economy, but the housing markets within the corridor have different foundations. Lexington draws healthcare, university, professional, government, and equine-industry demand. Richmond has its own employment base, a regional university, Blue Grass Army Depot activity, and a practical appeal for households balancing space, price, and access to Lexington. Demand around the Red River Gorge includes second homes and short-term rentals as well as full-time residences.

    Those distinctions affect the way inventory behaves. A well-positioned home in an established Lexington neighborhood can attract immediate attention even when the broader market is quieter. A larger home outside town may take longer because its buyer pool is narrower. A Gorge cabin may generate interest on projected rental income, but the final value still depends on access, condition, utility reliability, restrictions, and realistic operating expenses.

    Broad reports remain useful as a temperature check. They are not a valuation. A reliable opinion of value is sourced, dated, and interpreted against the specific property in front of you.

    The Market Is More Selective, Not Necessarily Slow

    The defining condition in many Kentucky submarkets is selectivity. Buyers may still move quickly for homes that are clean, correctly priced, well photographed, and located in an established demand pocket. They are much less forgiving of deferred maintenance, awkward improvements, dated interiors presented at renovated-home pricing, or rural properties with unanswered questions.

    That split can make the market feel contradictory. One seller sees multiple offers while another receives little activity. The difference is often not simply price per square foot. It can be presentation, location, layout, lot utility, insurance considerations, financing eligibility, or the gap between the seller’s pricing expectation and the alternatives available to buyers that week.

    For sellers, this means preparation has regained its importance. A pre-listing plan should identify repairs that protect value, improvements that improve marketability, and projects that will not return their cost. Fresh paint and proper drainage may matter more than a fashionable but partial renovation. On rural homes and cabins, road condition, water source, septic information, and utility details can be more consequential than cosmetic staging.

    Mortgage Rates Still Shape the Conversation

    Financing costs influence affordability. Rate changes affect monthly payments differently depending on how a purchase is financed.

    Higher borrowing costs have also contributed to a practical inventory constraint. Owners with older, lower-rate mortgages may be reluctant to sell unless a move is necessary or clearly beneficial. That can limit the supply of conventional, well-maintained homes in established neighborhoods. It does not mean every listing deserves a premium. It means good inventory can be scarce while weak inventory remains visible for longer.

    Buyers should add up the full monthly cost of a property before falling in love with it, including taxes, insurance, association dues where applicable, and expected repairs. A rate change can alter buying power, but it should not erase the need for a property-specific inspection strategy. The right purchase is the house that fits the household’s cash flow and maintenance tolerance after closing. Loan options, rates, and qualification are questions for a licensed mortgage lender.

    Education only. I’m your agent, not your lender.

    Lexington, Richmond, and the Commute Trade-Off

    The Lexington-to-Richmond corridor trades commute time for different housing options. Richmond can offer more space, newer construction opportunities, and a lower entry point in certain segments than comparable choices closer to Lexington. For others, proximity to downtown Lexington, major employers, restaurants, and established neighborhoods outweighs that trade-off.

    There is no universal winner. Commute frequency changes how much location is worth against square footage. Richmond and Madison County may offer a larger yard, a newer home, or a different price point. Buyers should test the actual drive at the times they expect to use it, not just rely on a map estimate.

    The same principle applies to eastern properties. A scenic setting can be valuable, but distance affects contractor availability, delivery costs, emergency access, rental turnover, and ordinary errands. Lifestyle value is real. So are operating realities.

    Land, Farms, and Rural Homes Require a Different Lens

    Kentucky land is not interchangeable acreage. Two parcels with the same size and county can have sharply different utility and value. Road frontage, topography, floodplain, deed restrictions, mineral rights, fencing, water availability, soil conditions, and buildability all matter. A beautiful view does not establish a homesite.

    On rural property, settle the sewer question first. If public sewer is unavailable, the septic question should be addressed early, along with the location and condition of any existing system. Well yield, easements, boundary clarity, access agreements, and cellular service deserve the same level of attention. These are not minor diligence items to revisit after the emotional decision has been made.

    Horse properties add another layer. Barn condition, fencing quality, water distribution, ring footing, manure management, trailer access, and the practical relationship between the residence and working improvements all influence value. Comparable sales must reflect the property’s actual use, not merely its acreage count.

    Short-Term Rentals Need a Business Plan, Not a Weekend Fantasy

    The Red River Gorge remains a distinctive demand driver for cabins and second homes, but short-term rental interest should be analyzed as an operating business. Attractive photos and high seasonal rates do not answer the central questions: How many nights can the property reasonably book, what will it cost to manage, and what expenses will rise with remote ownership?

    A prudent projection accounts for cleaning, utilities, internet, insurance, maintenance, furnishings, platform fees, reserves, property management, and slower periods. It also considers local regulations, deed restrictions, access in poor weather, parking, septic capacity, and the guest experience from driveway to departure. A cabin that is charming but difficult to reach can have a very different revenue profile from one with reliable roads and straightforward check-in.

    Gross revenue is not value. Income can support pricing, but the property must still compete with nearby inventory and meet the expectations of the next buyer. In specialized markets, resale liquidity deserves as much attention as projected cash flow.

    What Buyers and Sellers Should Watch Next

    The next phase of the market will likely be decided less by one national forecast than by the interaction of rates, local inventory, household formation, and job stability. Pricing to the current market and removing avoidable friction help a listing compete. Preparation, inspection and a realistic read of condition support better decisions than reacting to headlines.

    Watch the new listings that actually compete with your property or search criteria. Watch pending sales, not just active list prices. Watch days on market by neighborhood and property type. And where data is thin, such as acreage, cabins, historic homes, or luxury estates, widen the time frame carefully without pretending that a distant sale is a direct match.

    The useful advantage in Kentucky real estate is not predicting every market turn. It is making a well-supported decision when the right property, price, and terms appear.

    Marcos Gil, REALTOR® · Keller Williams Commonwealth · KY license 296259 · Equal Housing Opportunity

  • Kentucky Mortgage Release: 30 Days, Then $500 a Day

    Beattyville Notes · Title & Closing

    A Kentucky mortgage release is supposed to happen within thirty days of payoff. KRS 382.365 says so plainly, and it attaches real money to the failure — a ladder that starts at $100 a day and reaches $500 a day, plus attorney’s fees. If you are selling a house in Lee County that was refinanced twice in the 1990s, this is the statute that decides whether an old lien still clouds your title.

    How long does a lender have to release a paid-off mortgage in Kentucky?

    Thirty days. A holder of a lien on Kentucky real property must file the release in the county clerk’s office where the lien is recorded within thirty days of satisfaction.

    KRS 382.365(1): “A holder of a lien on real property, including a lien provided for in KRS 376.010, shall release the lien in the county clerk’s office where the lien is recorded within thirty (30) days from the date of satisfaction.” The reference to KRS 376.010 means this covers a contractor’s or materialman’s lien as well as a mortgage.

    The statute does not leave “satisfaction” to argument. Subsection (7) defines the “date of satisfaction” as the date the lienholder receives “a sum of money in the form of a certified check, cashier’s check, wired transferred funds, or other form of payment satisfactory to the lienholder that is sufficient to pay the principal, interest, and other costs owing on the obligation.” The clock starts when the money lands, not when the servicer gets around to processing it.

    What are the damages if the lien is never released?

    They escalate on written notice. After notice and without good cause the lienholder owes $100 a day from the fifteenth day, rising to a total of $500 a day after the forty-fifth day.

    StageWhat KRS 382.365 provides
    Day 0Date of satisfaction — payoff funds received (subsection 7)
    Within 30 daysRelease must be filed with the county clerk (subsection 1)
    Written notice sentOwner or interested party notifies the lienholder of the failure
    Day 15 after notice$100 per day, for each day good cause did not exist (subsection 4)
    After day 45 after noticeAn additional $400 per day — “for a total of five hundred dollars ($500) per day” (subsection 5)
    ThroughoutActual expenses and a reasonable attorney’s fee (subsections 4 and 5)

    Each rung is conditioned on the absence of “good cause,” which the statute does not define — so none of this is automatic, and a court decides. But the structure tells you something useful even if you never file: the written notice is what starts the money running. A phone call to a servicer does not.

    The statute rewards one specific act: putting the demand in writing. Everything that follows is measured from that date.

    Can a court clear the lien if the lender will not?

    Yes. An owner or anyone acquiring an interest may file in District or Circuit Court, and on proof of payment in full the court directs the master commissioner to execute and file the release.

    Subsection (3) allows “a proceeding…by any owner of real property or any party acquiring an interest in the real property in District Court or Circuit Court against a lienholder that violates subsection (1) or (2),” and says such a proceeding “shall be given precedence over other matters pending before the court.” Subsection (4) then has the court, upon proof of satisfaction, enter judgment “authorizing and directing the master commissioner of the court to execute and file with the county clerk the requisite release.”

    That precedence language is the part worth knowing when a closing is scheduled. Court structure, divisions and local contacts are published by the Kentucky Court of Justice. Which court and which filing is a question for your attorney, not a form to download.

    What should a Kentucky seller do before listing?

    Pull your own chain at the county clerk and confirm every mortgage you have ever paid off shows a recorded release. Finding a gap in week one is a different problem than finding it in week six.

    This is the single most common avoidable delay I see in older housing stock around Beattyville, Irvine and Stanton — not a defect in the house, but a lender that stopped existing before it filed a release, or a release filed in the wrong county. Neither is hard to fix with lead time, and both are miserable to fix with a closing date on the calendar. Order the payoff statements you still have, note the lender names, and ask the clerk’s office to show you the release for each one.

    One more detail that matters for inherited property: subsection (8) provides that the section “shall not apply when a lienholder is deceased and the estate of the lienholder has not been settled.” Owner-financed notes are common here, and when the note holder has died the remedy in this statute may simply not be available.

    Frequently asked questions

    Does the lender have to mail me a copy of the release?

    Yes. Subsection (6) requires the former lienholder to send a copy of the release by regular mail to the property owner’s last known address within seven days of the release, and makes a violator liable to the owner for fifty dollars plus any actual expense incurred in obtaining documentation of the release.

    Does this statute replace other remedies?

    No. Subsection (10) states that the section “shall be held and construed as ancillary and supplemental to any other remedy provided by law.” It adds a route; it does not close others.

    What about an assignment of the mortgage that was never recorded?

    Subsection (2) requires an assignee to record the assignment as KRS 382.360 requires, while providing that an assignee’s failure to record “shall not affect the validity or perfection, or invalidity or lack of perfection, of a mortgage lien under applicable law.” Damages for failure to record an assignment are capped by subsection (5) at three times actual damages plus fees and costs, but not less than $500.

    Related reading

    Releases are one of several records to check before a Kentucky closing. For who pays what at the courthouse, see who pays the Kentucky real estate transfer tax. For the other lien that can surface late in a title search, see the eleven-year delinquent tax certificate search. For the annual bill itself, see Kentucky property taxes, explained.

    Last updated: November 2, 2026. Statutory text quoted from the Kentucky Revised Statutes database as last updated November 1, 2026.

    By Marcos Gil, REALTOR® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209. This is general information about Kentucky recording procedure, not legal advice, and I am an agent rather than a lender. Confirm your own chain of title with the county clerk and your attorney.

  • How to Stage Occupied Home Showings Without Disruption

    How to Stage Occupied Home Showings Without Disruption

    A vacant house can be arranged once and left alone. An occupied house has to perform between school mornings, remote-work calls, dog walks, dinner, laundry, and the occasional showing request with two hours’ notice. To stage occupied home showings well, the goal is not to make a family home look unlived in. It is to make it feel calm, cared for, and easy for a buyer to understand.

    For sellers in Lexington, Richmond, and the surrounding Kentucky corridor, this distinction matters. Buyers may forgive a child’s backpack by the door. They are less forgiving of crowded rooms, blocked sightlines, strong odors, deferred repairs, or evidence that the property will be difficult to maintain. Good occupied-home staging is an operating plan as much as a design exercise.

    Why Stage Occupied Home Showings Differ From Vacant Listings

    A vacant listing gives buyers an unobstructed view of square footage, light, circulation, and condition. It can also feel cold or expose an awkward room layout. An occupied listing has the opposite risk: it can feel warm and believable, yet visually noisy enough that buyers miss the room itself.

    The work is therefore selective. Sellers do not need to replace every piece of furniture or pack the house into storage. They need to remove the items that compete with the property. In a well-staged occupied home, buyers should notice the window wall before the television, the hardwood floor before the pet bed, and the kitchen’s work space before the countertop appliances.

    This is especially relevant in homes where buyers are comparing several options in one afternoon. A buyer touring a Chevy Chase bungalow, a Hamburg-area newer build, and a Madison County acreage property is making fast emotional and practical judgments. The listing that feels orderly and legible has an advantage, even when the homes are not directly comparable.

    Start With the Buyer’s First Five Minutes

    Most showing feedback is formed before buyers have reached the primary bedroom. The approach to the home, entry, main living area, and kitchen carry disproportionate weight because they establish the condition standard for everything that follows.

    Begin outside. Trim back vegetation that covers windows or walkways, sweep porches, replace failed exterior bulbs, and remove surplus planters, hoses, toys, and seasonal decor. A rural property may not need a suburban front-yard presentation, but its approach still needs to communicate stewardship. Gravel should be passable, gates should operate, and the entry should not suggest a weekend of catch-up work.

    Inside, create a clear landing zone at the front door. Limit shoes, coats, bags, and mail. If the home has a mudroom or side entry that the household genuinely uses, organize that space rather than pretending it does not exist. Buyers understand Kentucky weather and active households. They do not need perfection. They do need to see that storage works.

    The kitchen deserves unusually strict editing. Clear counters except for a few intentional items, such as a coffee maker or a simple bowl of fruit. Remove refrigerator magnets, pet supplies, medications, and paperwork. Buyers often use the kitchen to assess storage, work flow, and overall upkeep. A crowded counter makes even a generously sized kitchen feel short on cabinets.

    Edit Before You Decorate

    Occupied-home staging usually produces its best return through subtraction. Decorative purchases can help, but only after unnecessary volume is gone. This is where sellers commonly underestimate the issue: they tidy their belongings but keep too much of them in the room.

    Start by reducing furniture. If a room has seating for eight but only needs seating for four, remove the extra pieces. If a bedroom doubles as an office, fitness room, and storage area, decide what function the buyer most needs to see. In a three-bedroom home marketed to families, preserve the bedroom. In a downtown Lexington condo likely to appeal to a professional buyer, a disciplined office setup may add more value.

    Then depersonalize with judgment. Family photographs, collections, political items, and highly specific decor can pull attention away from the home, but stripping every surface can make the property feel generic. Keep art that suits the room, a few books, and restrained accessories. The standard is not hotel minimalism. It is visual confidence.

    Storage is part of the presentation. Overfilled closets, packed pantry shelves, and crowded garage walls tell buyers there is not enough room, whether or not that is true. Aim to show some breathing room in each storage area. This may require off-site storage for the listing period, particularly for inherited homes, growing families, and sellers preparing for a relocation.

    Build a Showing-Ready Routine That Can Last

    The best staging plan fails if it requires three hours of work before every appointment. A practical system keeps the property close to ready and reduces the stress of short-notice showings.

    Designate one concealed basket or bin for each high-traffic area. Before leaving, collect loose chargers, school papers, remotes, pet toys, and daily-use items into the appropriate bin, then place it in a closet, vehicle, or cabinet. This is more effective than trying to find a permanent home for every item in the final ten minutes.

    Create a short departure sequence for the household: make beds, empty the sink and dishwasher, wipe kitchen and bath counters, close toilet lids, turn on selected lights, adjust blinds, and take pets out. The sequence should be simple enough that every adult can execute it without debate. A printed checklist inside a pantry door is not glamorous, but it works.

    For homes with children, consider keeping a small activity bag in the car. For homes with dogs, arrange a reliable showing plan early rather than improvising each time. A barking dog behind a closed door can keep buyers from inspecting a room; a loose pet can end a showing altogether. Cat litter, feeding stations, and pet odors require honest attention. Air freshener is not a remedy for a cleaning problem, and heavy fragrance can create suspicion rather than reassurance.

    Address Condition Before Styling

    Staging cannot outperform obvious maintenance issues. Fresh towels and styled shelves will not offset a dripping faucet, stained ceiling, loose handrail, or damaged screen. Buyers tend to connect small unresolved defects with larger unknowns, fairly or not.

    Before photography and showings, walk the property with a condition-first eye. Test lights, doors, windows, appliances, toilets, and visible outlets. Repair items that are inexpensive and clearly noticeable. Touch up paint where scuffs, nail holes, or mismatched patches draw the eye. Clean grout, recaulk where appropriate, and replace worn caulk that makes an otherwise sound bath feel neglected.

    Not every repair should be completed without considering the likely return. An aging roof, original windows, or dated bath may be better handled through price, disclosures, and a clear marketing position than through a rushed cosmetic fix. The right answer depends on the home’s price range, competing inventory, and whether the work can be done correctly before launch. Valuation and preparation should be sourced, dated, and interpreted together, not treated as separate decisions.

    Protect Privacy During Occupied Showings

    An occupied home contains more than furniture. It contains documents, prescriptions, devices, valuables, schedules, and personal information. Sellers should remove or secure checkbooks, mail, firearms, jewelry, spare keys, financial records, and medications before the first showing.

    Do not leave a calendar, a school schedule, or a work badge in plain view. In acreage properties or homes with detached buildings, secure tools, equipment, and personal vehicles as well. This is not alarmist. It is basic preparation when unfamiliar people are walking through private spaces.

    If there are areas that cannot be accessed for a legitimate reason, communicate that limitation before showings whenever possible. But use restricted access sparingly. A locked closet is ordinary. Multiple locked rooms can lead buyers to wonder what they are not being allowed to see.

    Let the Property Tell the Right Story

    The final layer of occupied-home staging is not decor. It is alignment. A horse property should show practical tack, utility, and cared-for grounds without reading as cluttered. A Red River Gorge cabin should feel like a retreat while still proving it can handle luggage, supplies, and turnover. A historic home should retain its character, but its details should not obscure needed maintenance or awkward circulation.

    That is why a one-size-fits-all staging checklist is rarely enough. The right presentation depends on who is most likely to buy, what they will compare it against, and which practical concerns the home needs to answer before they become objections. A disciplined showing plan gives buyers room to picture their own life there – and gives sellers a manageable way to keep living theirs while the house is on the market.

  • Who Pays Kentucky’s Real Estate Transfer Tax?

    Who Pays Kentucky’s Real Estate Transfer Tax?

    Journal · Closing Costs

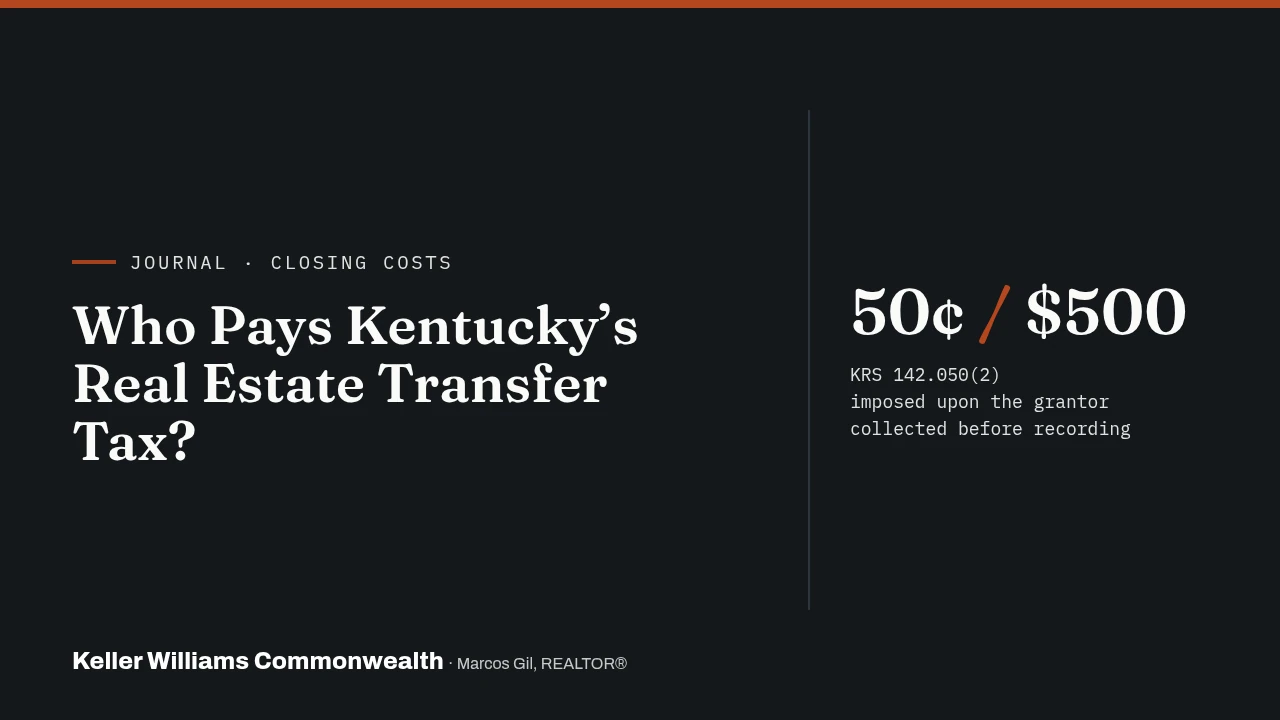
    Kentucky’s real estate transfer tax is imposed on the seller, not the buyer. The statute puts it “upon the grantor named in the deed” at fifty cents for each $500 of declared value, and the county clerk collects it before the deed will be accepted for recording. If you are buying a house in Lexington, Richmond or Beattyville, this is one closing-cost line that is not yours by law — though it is negotiable by contract.

    Who pays the transfer tax when a Kentucky house sells?

    The grantor — the seller. KRS 142.050(2) imposes the tax “upon the grantor named in the deed” at fifty cents per $500 of value, or any fraction of $500.

    Statute card for Kentucky’s real estate transfer tax: the grantor pays 50 cents per 500 dollars of declared value, with worked examples of 250,000, 300,000 and 300,100 dollars, and the five steps the county clerk follows at recording
    Figures are arithmetic from the statutory rate in KRS 142.050, as stated in this article, not quotes for any transaction.

    That works out to $1.00 per $1,000 of declared value, or one tenth of one percent. The “or fraction thereof” language matters: the count rounds up to the next $500 increment rather than prorating. On a deed declaring $300,000, the arithmetic is 600 increments of $500 at fifty cents each — $300.00. On a deed declaring $300,100, it is 601 increments — $300.50.

    What the tax is calculated on is defined, not estimated. Under KRS 142.050(1)(b), “value” for an ordinary sale is “the amount of the full actual consideration therefor, paid or to be paid, including the amount of any lien or liens thereon.” For a gift, a nominal-consideration deed or a deed with no stated consideration, value becomes “the estimated price the property would bring in an open market and under the then prevailing market conditions in a sale between a willing seller and a willing buyer, both conversant with the property and with prevailing general price levels.”

    Who actually collects it, and when?

    The county clerk, at the recording window. KRS 142.050(3)(a) makes collection “a prerequisite to acceptance of the deed for recordation” — no payment, no recording.

    Three mechanics follow from the same subsection and the one after it. The clerk computes the amount on the basis of the value set forth in the deed, not on an independent appraisal. The tax “shall be collected only once on each transaction,” and in the county where the deed is required to be recorded under KRS 382.110(1). And under KRS 142.050(4) the clerk certifies the date and amount of collection on the deed itself, retains five percent as the collection fee, and remits the balance every three months to the county treasurer, who deposits it in the county general fund.

    Two practical consequences. First, the certification is stamped on the recorded instrument, so the amount paid is a public record you can read back off the deed later. Second, because the money lands in the county general fund, this is county revenue — which is why the declared value on a deed is not a casual number.

    The statute says the seller owes it. Your purchase contract can say something else — and that is a term, not a correction.

    Which transfers are exempt?

    KRS 142.050(7) lists fifteen categories of transfer the tax does not reach. Several come up routinely in Central Kentucky and Gorge-region files.

    Exempt transferSubsection
    Between husband and wife, or between former spouses as part of a divorce proceeding(7)(e)
    Between parent and child, or grandparent and grandchild, with only nominal consideration(7)(l)
    Under a foreclosure proceeding, or a voluntary surrender under a mortgage in lieu of foreclosure(7)(j)
    A deed that confirms or corrects a deed previously recorded(7)(d)
    Solely to provide or release security for a debt or obligation(7)(c)
    Between a trustee and a successor trustee(7)(n)
    Between a limited liability company and any of its members(7)(o)
    On partition(7)(g)
    On sale for delinquent taxes or assessments(7)(f)
    Pursuant to merger, consolidation or entity conversion among corporations, partnerships, limited partnerships or LLCs(7)(h)

    The remaining five cover deeds recorded before March 27, 1968, gifts or nominal-consideration deeds to or from government bodies, parent-subsidiary transfers for no or nominal consideration, proportionate-interest contributions into an entity for nominal consideration, and matching proportionate distributions out of an entity on dissolution. Note how many of the exemptions turn on the words “nominal consideration” — the exemption is doing work the deed has to state.

    Also worth knowing what a “deed” is not. KRS 142.050(1)(a) defines it as any document conveying real property or an interest in it, “other than a will and other than a lease or easement.” A lease or an easement grant is outside the tax by definition, not by exemption.

    How this shows up on a real closing statement

    In practice the transfer tax is a small number that gets noticed for the wrong reason. It is almost never the dollar amount that causes a problem — it is the assumption. Buyers arrive expecting to pay every tax at the table and sellers sometimes arrive expecting the buyer to cover it, and the statute settles neither question for your particular contract, because the contract can allocate it however the parties agree. What I do is simple: confirm who the purchase contract assigns it to in writing, early, and confirm that the declared value on the deed is the number everyone believes it is. The second one matters more. Where a transfer looks like it may land in one of the KRS 142.050(7) exemption categories — a family transfer, an LLC-to-member transfer, a correction deed — that is a question for your closing attorney and the county clerk before the deed is drafted, not a decision for your agent. I am your agent, not your attorney or your tax adviser.

    Transfer tax is one line among several. The recurring one is on Kentucky property taxes, the earnest-money mechanics are on earnest money in Kentucky, and if you are buying in the Gorge region start at homes for sale in Beattyville or with Marcos Gil Realty directly.

    Questions that follow

    Can the buyer agree to pay the Kentucky transfer tax?

    The statutory burden in KRS 142.050(2) falls on the grantor, and the clerk collects before recording regardless of who hands over the money. How the parties allocate the cost between themselves is a contract term. Put it in writing.

    What is the Kentucky transfer tax on a $250,000 house?

    At the statutory rate of fifty cents per $500 of declared value, $250,000 is 500 increments — $250.00. The rate is set in KRS 142.050(2); the amount always turns on the value declared in the deed.

    Is the transfer tax charged twice if the property crosses county lines?

    No. KRS 142.050(3)(c) states the tax “shall be collected only once on each transaction,” and in the county in which the deed is required to be recorded by KRS 382.110(1).

    Source: KRS 142.050, Real estate transfer tax — Collection on recording — Exemptions, read from the Kentucky Legislative Research Commission on October 31, 2026. Dollar figures above are arithmetic from the statutory rate, not quotes or estimates of any particular transaction.

    Last updated October 31, 2026.

    By Marcos Gil, REALTOR® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209.

  • Winchester KY Housing Stock by Age: What ZIP 40391 Shows

    Market Notes · Winchester & Clark County

    If you are searching homes for sale in Winchester KY 40391, the listings will tell you what is available this week. They will not tell you what kind of houses Winchester is made of — and that second thing decides which inspections matter, which disclosures are coming, and what your repair budget should look like before you have seen a single property. The Census Bureau publishes that answer for the 40391 ZIP code, and it is worth ten minutes.

    How old are the houses in Winchester, Kentucky?

    The median Winchester-area house was built in 1979, and 51.2% of the ZIP’s 16,125 housing units were built before 1980.

    Those figures come from the American Community Survey 5-year estimates for 2023, for ZIP Code Tabulation Area 40391 — table B25035 for median year built and table B25034 for the full age distribution. Pulled from the Census Bureau’s API on October 30, 2026, the distribution looks like this.

    Year structure builtUnitsShare of stock
    2020 or later1200.7%
    2010–20199395.8%
    2000–20092,37514.7%
    1990–19992,88417.9%
    1980–19891,5479.6%
    1970–19792,79417.3%
    1960–19691,5909.9%
    1950–19591,5429.6%
    1940–19498985.6%
    1939 or earlier1,4368.9%
    Total16,125100%

    Two numbers jump out of that column. Only 6.6% of the housing in 40391 was built in 2010 or later — about one unit in fifteen. And the single largest decade is the 1990s at 17.9%, with the 1970s a close second at 17.3%. Winchester is not a new-construction market and it is not a historic-district market. It is a market of houses that are between thirty and fifty-five years old.

    Why does a median build year of 1979 matter to a buyer?

    Because the federal lead-based paint disclosure rule turns on 1978. Winchester’s median house was built one year after that line — which means roughly half the market sits on the older side of it.

    The EPA states that lead-based paint for use in homes was banned in the United States in 1978, and that the Lead-based Paint Disclosure Rule requires sellers, landlords, real estate agents and property managers to provide specific information about known lead-based paint and lead-based paint hazards before a prospective buyer or renter signs a contract or lease — a requirement that applies to most pre-1978 private housing. The EPA also notes that lead-based paint is usually not a hazard when it is in good condition, and that deteriorating paint is what needs prompt attention.

    Now the honest caveat, because this is where a lot of writing about Census housing data quietly cheats. The ACS does not publish a pre-1978 bucket. Its buckets are decades, and the relevant one spans 1970 to 1979 — straddling the cutoff. So the exact share of 40391 housing built before 1978 is not readable from this table. What the table supports is narrower and still useful: 34.0% of the stock was built in 1969 or earlier and is unambiguously pre-1978, a further 17.3% was built somewhere in the 1970s and may fall on either side, and the median build year of 1979 sits within a year of the line. Anyone quoting you a precise pre-1978 percentage for this ZIP from ACS data is estimating and should say so.

    Half of Winchester’s housing stock predates 1980. That is not a warning about the town — it is an instruction about which inspections you order first.

    What does the 1990s cohort mean right now?

    The 2,884 units built between 1990 and 1999 are now twenty-seven to thirty-six years old — the window where original systems reach the end of their service lives together.

    This is the same pattern worth watching one county over, and it is the practical reason the decade column matters more than the median. A house built in 1995 with its original roof, original HVAC, original water heater and original service panel is not a distressed property. It is a property whose major components were all installed in the same year and will therefore come due in roughly the same few years. When you tour a 1990s Winchester house, the question is not “is anything broken” — it is “what has been replaced, and when.” A seller who can produce dates is handing you a very different risk profile than a seller who cannot.

    What else does the Census say about the 40391 market?

    Owner-occupancy runs 71.4%, vacancy 8.1%, median owner-occupied home value $197,200, and median gross rent $884 per month.

    From the same 2023 ACS 5-year release for ZCTA 40391: 14,815 of the 16,125 units are occupied, of which 10,585 are owner-occupied, giving the 71.4% figure; 1,310 units are classified vacant, or 8.1% of all units. Median value for owner-occupied units is $197,200 (table B25077) and median gross rent is $884 (table B25064).

    Treat all of these as what they are: five-year averages published by a federal statistical agency, not today’s asking prices. ACS 5-year estimates pool survey responses across sixty months, so the median value is a smoothed figure that lags a moving market in both directions. It is the right tool for the question “what is this housing stock like” and the wrong tool for the question “what will this house sell for.” For the second question you want current comparable sales, which is agent work, not Census work.

    How to use this before you tour anything

    The professional habit here is unglamorous: read the stock before you read the listings. When half of a market was built before 1980 and the biggest single cohort is the 1990s, your diligence plan is knowable in advance — you will be asking about paint condition and disclosure on the older half, and about replacement dates for roof, HVAC, water heater and panel on the newer half. That lets you book the right inspections instead of discovering you needed them. It also changes how you read a price: two houses at the same number in the same ZIP can carry very different deferred-maintenance loads, and the build decade is the fastest tell.

    If you are working the area, the companion pages are Living in Winchester, Kentucky for the place itself and farms and land for sale in Winchester and Clark County if acreage is what you are after. The same thirty-year replacement analysis applied to a different county is in the Lee County 1990s homes replacement list.

    Sources, all verified October 30, 2026: the housing figures are from the U.S. Census Bureau American Community Survey, 2023 5-year estimates for ZCTA5 40391, tables B25001, B25002, B25003, B25034, B25035, B25064 and B25077 — table B25034 is viewable at data.census.gov. The lead-paint statements are from the U.S. Environmental Protection Agency’s real estate disclosure page.

    Is ZIP 40391 the same thing as the city of Winchester?

    No, and the difference matters when you read the numbers. These figures are for ZIP Code Tabulation Area 40391, a Census geography built to approximate the 40391 postal ZIP. It takes in the city of Winchester plus surrounding Clark County territory, so the stock described here is a Winchester-area figure rather than a city-limits figure.

    Does an older house mean a lead-paint problem?

    Not by itself. The EPA states that lead-based paint is usually not a hazard if it is in good condition, and that deteriorating paint — peeling, chipping, chalking, cracking or damaged — is the hazard that needs prompt attention. Age tells you the disclosure rule is likely in play and that paint condition is worth looking at. It does not tell you a specific house has a problem.

    Why use ACS data instead of just looking at listings?

    Because listings show you the slice of the stock that happens to be for sale this month, which is a tiny and non-random sample. The ACS describes all 16,125 units. One tells you what you can buy now; the other tells you what you are likely to be buying.

    This page is general education using published federal data. It is not an appraisal, not a condition report on any specific property, and not a prediction about prices.

    Last updated: October 30, 2026

    By Marcos Gil, REALTOR® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209.
  • Can Buyers Purchase Before Selling a Home?

    Can Buyers Purchase Before Selling a Home?

    A Lexington homeowner finds the right home in Hamburg or Richmond on Friday, but their current house has not reached the market. By Monday, there may be competing offers. That is the real question behind whether can buyers purchase before selling: not whether it is theoretically possible, but whether the household can carry the financial exposure without making a pressured decision on either property.

    For many Kentucky owners, buying first can be a sensible move. It can also turn a manageable transition into two mortgages, a rushed listing, and an avoidable price reduction. The answer depends on available cash, loan qualification, the likely net proceeds from the current home, the pace of the specific submarket, and the seller’s willingness to accept a contingent offer.

    Can Buyers Purchase Before Selling? Yes, With a Plan

    A buyer does not need to sell first simply because their down payment is tied up in their present home. Lenders and transaction structures can address that gap. What matters is choosing a structure that matches the risk tolerance of the household and the marketability of the home being sold.

    The first distinction is between qualifying to own two homes and merely expecting the first home to sell. A lender may approve a buyer using both housing payments if income, assets, and debt-to-income ratios support it. This is often the cleanest position in a competitive situation because the purchase is not dependent on closing the sale of the existing home.

    But approval is not the same as comfort. Carrying two payments for 60 or 90 days may be reasonable for one client and untenable for another. Property taxes, insurance, utilities, maintenance, and any required repairs belong in that calculation. So does the possibility that the existing home sells below the preliminary estimate. Valuation should be in writing, based on comparable sales that are sourced, dated, and interpreted, not on an optimistic portal estimate.

    The Main Ways to Buy Before You Sell

    There is no universally superior option. The right route changes with the buyer’s liquidity, loan profile, property type, and how much negotiating leverage exists on both sides.

    Purchase with a home-sale contingency

    A home-sale contingency makes the purchase contingent on selling and usually closing on the buyer’s current home by an agreed deadline. It protects the buyer from having to complete the new purchase without their sale proceeds.

    This can work well when the existing property is already listed, properly priced, and under contract or close to it. It is less attractive when a buyer is asking a seller to take their home off the market while the contingent property has not even been exposed to buyers. In a multiple-offer environment, a seller may accept a cleaner offer instead.

    Contingencies also need precise language. Is the contingency tied to listing the home, receiving an acceptable contract, or the actual closing? Can the seller continue marketing the property? Does the buyer have a short period to remove the contingency if another offer arrives? These terms determine how real the protection actually is.

    Buy with a bridge loan or home equity financing

    A bridge loan, home equity loan, or home equity line of credit can give an owner access to equity before their current home sells. The proceeds may fund a down payment, closing costs, or part of the new purchase price.

    The advantage is a stronger offer that is not dependent on the sale. The trade-off is cost and exposure. Rates, fees, repayment terms, and underwriting standards vary materially by lender. A home equity line may be useful for a buyer with substantial equity and strong income, but it should not be treated as free money because the old home is expected to sell quickly.

    For rural properties, acreage, cabins, and homes with unusual features, timelines can be less predictable than they are for a well-positioned neighborhood home in Lexington. A bridge strategy needs enough runway for the actual buyer pool, not the timeline everyone hopes for.

    Qualify while carrying both properties

    Some buyers can make the new purchase with conventional, VA, or other financing while retaining the present home temporarily. This may be suitable for households with strong reserves, low existing debt, or plans to keep the former property as a rental.

    Lenders will examine the full picture: principal and interest, taxes, insurance, HOA dues, credit obligations, and liquid reserves. If projected rental income from the former home is part of the plan, ask early how that income can be counted. A signed lease is not always enough, and the lender’s rules may differ by loan type.

    This approach gives the buyer meaningful control over move timing. It also makes it easier to prepare the former home after moving out, which can improve photography, repairs, cleaning, and showing access. Still, the carrying cost needs to be tolerable even if the home takes longer to sell.

    Negotiate a rent-back or delayed possession

    Sometimes the simplest answer is not financing at all. A seller may agree to a short post-closing possession period, allowing the buyer to close on the current home and remain there while completing the next purchase. Alternatively, a buyer of the current home may permit a rent-back after closing.

    This can reduce the need for temporary housing and storage, but it requires a clear written agreement. Insurance, security deposits, daily occupancy costs, condition at move-out, and holdover consequences should be addressed. A casual promise to “work something out” is not a transaction plan.

    Start With Net Proceeds, Not the List Price

    Before looking at the next property, determine what the current home is likely to contribute. The number is not the anticipated sale price. It is the estimated net after mortgage payoff, commissions, transfer-related charges, seller concessions if applicable, repair or preparation costs, and any liens.

    A seller who expects $150,000 in equity may have materially less available for the next down payment after those deductions. That difference can change loan terms, cash reserves, and the maximum purchase price.

    The same discipline applies to the replacement home. A $600,000 purchase is not simply a $600,000 decision. It includes closing costs, inspection findings, insurance, possible rate buydowns, moving expenses, and initial work after possession. Older Lexington homes, farm properties, and gorge-area cabins can each have property-specific costs that do not appear in the headline price. Sewer first, always. Then drainage, access, utilities, roof age, and the systems that make a house livable rather than merely attractive.

    When Selling First Is the Better Choice

    Selling first is often the more prudent route when the current home must sell to fund the next purchase and there is little capacity to carry two properties. It may also be preferable if the existing home has condition issues, an ambitious pricing expectation, or a narrower buyer pool.

    That does not mean moving into uncertainty without a plan. A seller can negotiate a longer closing period, request post-closing possession, use a short-term rental, or focus the search after the sale is secure. The inconvenience is real, but it may be less expensive than buying under pressure or accepting a weak offer on the current home.

    For relocators, timing deserves special attention. A new job start date, school calendar, lease expiration, and commute pattern can turn a sound financing plan into a difficult logistical one. The Lexington-to-Richmond decision, for example, is not just about purchase price. It is also about travel time, childcare routines, employer flexibility, and whether a temporary move would meaningfully disrupt daily life.

    Build the Decision Around the Downside Case

    The best time to consider buying first is before the preferred property appears. Speak with a lender about qualification under more than one scenario, obtain a current payoff figure, estimate net proceeds conservatively, and identify the cash reserve that remains after closing.

    Then test the uncomfortable version of the plan. What if the present home takes 90 days to sell? What if inspection negotiations require a credit? What if the new property’s appraisal comes in low? What if the first month of dual ownership includes a roof repair or a failed HVAC system? A strategy that only works under ideal conditions is not a strategy.

    A well-prepared buyer can move quickly when the right property arrives without treating every attractive listing as a reason to overextend. The goal is not simply to buy before selling. It is to preserve the ability to say no when the numbers, terms, or property condition do not hold up.

  • Kentucky Seller Disclosure Form: Two Clocks, Three Exemptions

    Beattyville & the Gorge Region · Diligence

    Kentucky’s seller’s disclosure of conditions form runs on two clocks and has three exemptions, and almost nobody on either side of a closing table can name them. The statute gives a listing agent seventy-two hours from a written offer to get the form to the buyer, gives a for-sale-by-owner transaction a hundred and twenty hours from contract, and makes it a licensing violation for an agent to fill in any part of the form the seller should have filled in.

    When does the Kentucky seller’s disclosure form actually have to be delivered?

    Within seventy-two hours of the listing agent receiving a written and signed offer to purchase. KRS 324.360(4) sets that clock, and it starts at the offer, not at the contract.

    Two other delivery duties sit alongside it in the same subsection. The seller completes and signs the form “at the time he or she executes any listing agreement or similar agreement by which a licensee intends to market the property” — so the form is a listing-day document, not a contract-day one. And separately, a copy “shall be provided by the listing agent to any prospective buyer or a buyer’s authorized representative upon request.” A buyer who asks before writing is entitled to it on the asking.

    The listing agent then has to close the loop in writing: the agent “shall solicit the signature of the buyer” on a copy retained in the principal broker’s records, and that signature is what evidences compliance. If the buyer refuses to sign, the statute does not leave the agent stuck — the licensee records the refusal on the form and keeps a copy in the broker’s records.

    What about a for-sale-by-owner house?

    A different clock, and a longer one. Where there is no listing agreement, KRS 324.360(5) requires any licensee involved in the transaction to give the owner a blank form and request that the owner complete and sign it.

    If the owner does complete and sign it, the licensee delivers it to the buyer “not later than one hundred twenty (120) hours after the creation of any executory contract for sale of the property.” Note the trigger moved: seventy-two hours from an offer in a listed sale, a hundred and twenty hours from a contract in an unlisted one. The same buyer-signature and refusal-notation mechanics apply, and under subsection (6) the original of the form is retained by the listing broker — or, where there is no listing agreement, by the broker of whichever licensee presented the offer.

    Seventy-two hours from the offer when it is listed; a hundred and twenty hours from the contract when it is not.

    Which sales are exempt from the form?

    Three, and they are narrow. KRS 324.360(7) says the form is not required for residential purchases of new homes if a warranty is offered, for a sale of real estate at an auction, or for a court-supervised foreclosure.

    Read the first one precisely. New construction is not exempt because it is new; it is exempt where a warranty is offered. A new house sold without a warranty is not inside that exemption as written.

    There is also a threshold that does the work of a fourth exemption. Subsection (1) limits the whole section to sales and purchases involving single-family residential dwellings “if any person licensed under this chapter receives compensation.” A true owner-to-owner sale with no licensee compensated anywhere in it is outside the section entirely — which is exactly why a buyer in that situation gets no form and should not read the silence as reassurance.

    What is on the form, and who may write on it?

    Five enumerated condition categories plus whatever else the Commission adds — and the seller writes it, not the agent. Subsection (9) makes agent completion a violation of the chapter.

    Subsection (2) directs the Kentucky Real Estate Commission to promulgate an administrative regulation authorizing the form, and subsection (3) lists what it must cover: basement condition and whether it leaks; roof condition and whether it leaks; source and condition of water supply; source and condition of sewage service; working condition of component systems; and other matters the Commission deems appropriate.

    Then the hard line. Subsection (9): “It shall be a violation of this chapter for a licensee to complete any portion of the form unless the licensee is the owner of the property or has been requested by the owner to complete the form.” Where the owner does make that request, it “shall be acknowledged in writing on the form,” and the licensee is then held harmless for any representation appearing on it. Helpfully filling in a blank the seller left empty, without that written acknowledgement on the form, is the error this subsection exists to punish.

    And if the seller declines altogether? Subsection (8) covers it: the refusal “shall be communicated in writing by the broker or sales associate who is involved in the transaction to the purchaser or prospective purchaser, without unreasonable delay.” A seller may refuse. The refusal cannot be quiet.

    Why those five categories matter in Lee, Estill and Powell counties

    Because three of the five are the systems most likely to be private rather than municipal here: water supply, sewage service, and the component systems that depend on them.

    “Source and condition of water supply” on a house outside a city system means a well, and there is a separate state record that should exist for it — our post on the Kentucky water well record covers which wells have one and who holds it. “Working condition of component systems” is a disclosure line, not an inspection; the difference between a disclosure, an inspection and a repair estimate is covered in why a repair estimate is not a home inspection and in the home inspection licence exemptions post. For the wider walkthrough of the form from a seller’s side, see our Kentucky seller disclosure guide. And on an older house, the federal lead-paint route runs on its own clock, covered in the pre-1978 lead paint 10-day inspection post.

    How I handle the form

    Working practice, not legal advice. Three habits, all of them about keeping the document the seller’s.

    I get the form filled at listing rather than at offer, because subsection (4) says that is when it is due and because a seller filling it out under offer pressure writes shorter answers. I do not write on it. If a seller asks me to, the request goes in writing on the form itself, which is what subsection (9) requires and the only thing that makes the hold-harmless language operate. And when a seller leaves a line blank, I ask the question again rather than guessing at an answer; a blank the seller chose is a disclosed fact of a kind, while a blank I filled is my representation on their document. On the buyer side the discipline is the reverse: I treat the form as the start of diligence and never as the end of it, because the statute asks the seller what they know, not what is true. A disclosure that says the roof does not leak is a statement about the seller’s knowledge on the day they signed.

    Does the seller have to fill out the form at all?

    A seller may refuse. KRS 324.360(8) then requires the broker or sales associate involved to communicate that refusal in writing to the purchaser or prospective purchaser without unreasonable delay.

    Is new construction exempt from the Kentucky disclosure form?

    Only where a warranty is offered. KRS 324.360(7) exempts residential purchases of new homes if a warranty is offered, sales at auction, and court-supervised foreclosures.

    Can my agent help me complete the disclosure form?

    Only if you ask and the request is acknowledged in writing on the form. KRS 324.360(9) makes it a violation of the chapter for a licensee to complete any portion of the form otherwise, unless the licensee owns the property.

    Last updated: October 29, 2026

    By Marcos Gil, REALTOR ® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209.