Brokered by

The Journal

  • Kentucky Homebuyer Closing Guide: What to Expect

    Kentucky Homebuyer Closing Guide: What to Expect

    A Kentucky homebuyer closing guide should begin with one practical fact: the day you receive the keys is not the day to discover an unpaid utility balance, a missing repair receipt, a boundary question, or a wire instruction that arrived by email. Closing is the final transfer of a property, but the quality of the closing is determined by the work done in the weeks before it.

    For a Lexington condominium, a Richmond family home, a farm outside Berea, or a Red River Gorge cabin, the paperwork follows a familiar sequence. The risk profile does not. A sound closing process is sourced, dated, and interpreted for the property in front of you – not borrowed from a generic checklist.

    What Closing Means for a Kentucky Buyer

    Closing is the legal and financial handoff from seller to buyer. Your lender, title company or closing attorney, real estate agents, insurance provider, and sometimes surveyor or contractor each contribute documents or information. The settlement agent coordinates the final figures, confirms that title requirements have been met, receives funds, obtains signatures, and records the deed and mortgage documents with the appropriate county clerk.

    Most financed buyers receive a Closing Disclosure at least three business days before consummation. This document deserves a slow reading. It sets out the loan terms, monthly payment, cash required to close, lender charges, title and government fees, prepaid items, and prorations. Compare it with your Loan Estimate, but do not assume every difference is an error. A change in closing date, insurance premium, prepaid interest, tax treatment, or lender credit can move the numbers legitimately. The question is whether each change is explained and supported.

    Cash buyers have fewer lender documents, but not fewer reasons to review the settlement statement. Title charges, recording costs, tax prorations, earnest-money credits, association fees, and any negotiated repair credit still need to be right.

    Before Closing: Clear the Conditions That Matter

    The purchase contract establishes deadlines, but deadlines alone do not make a buyer protected. Inspection, appraisal, financing, title, and insurance are distinct workstreams. A clean appraisal does not validate a roof, a septic system, a shared driveway agreement, or the insurability of an older electrical panel.

    Inspection Is a Decision Point, Not a Report Collection Exercise

    A general home inspection identifies visible conditions on the day of inspection. It is not a warranty and it is not a substitute for specialized review where the facts call for it. Older Lexington homes may warrant sewer-scope work, electrical review, or further investigation of moisture in a basement. Sewer first, always, where an older urban property, mature trees, slow drains, or a cast-iron line create a reasonable concern.

    In Madison County, Estill County, Powell County, and rural parts of the corridor, water, septic, road access, drainage, and outbuilding conditions may carry more weight than cosmetic updates. A cabin can photograph beautifully while presenting a difficult driveway, inadequate drainage, unverified short-term-rental assumptions, or a septic system poorly matched to its use. If a repair is negotiated, define it precisely: who performs it, whether permits are required, what documentation is due, and whether the work must be complete before closing.

    Title, Survey, and Property Rights

    Title work is where a closing stops being visual and becomes legal. The title search examines the recorded history of ownership and identifies matters that must be resolved, insured around, or accepted by the buyer. Common items include mortgages, judgment liens, easements, restrictive covenants, utility rights-of-way, and prior deeds that affect access or use.

    Do not treat an easement as automatically alarming or automatically harmless. A utility easement in a predictable location may be routine. An access easement serving several parcels, a shared drive without a recorded maintenance agreement, or a restriction affecting a planned barn, fence, rental use, or addition deserves focused review.

    A survey is especially useful when boundaries, fencing, acreage, improvements near a line, access, or planned construction matter. It may not be necessary in every conventional neighborhood purchase, but it is often cheap clarity for land, farms, historic properties, and irregular lots. Ask what type of survey is being provided, what it does and does not certify, and whether the title commitment includes exceptions that the survey could clarify.

    Read Your Closing Disclosure Like an Owner

    The final cash-to-close figure is not a number to glance at in the parking lot. Review it with enough time to ask questions. Confirm the purchase price, earnest-money credit, loan amount, seller concessions, inspection or repair credits, lender credits, and the amount of your down payment.

    Also review the recurring costs. Property taxes in Kentucky are commonly prorated between buyer and seller based on the contract and local billing cycle. The precise treatment can vary with the county, the closing date, lender escrow requirements, and contract language. Transfer and recording charges likewise should be shown clearly, with responsibility allocated according to the agreement and local practice. A settlement statement should not require guesswork.

    Homeowners insurance must be bound before a financed closing, and the policy must meet lender requirements. For rural homes, cabins, and properties with detached structures, make sure the coverage matches the actual property and intended use. A policy written as a primary residence may not fit a second home or rental operation. If you are relying on rental income, do not leave that underwriting question until the week of closing.

    The Final Walk-Through Is a Verification, Not a Second Inspection

    The final walk-through usually occurs shortly before closing. Its purpose is narrow but important: confirm the property is in substantially the agreed condition, confirm negotiated repairs are complete, verify agreed personal property remains, and look for damage caused by moving out.

    Bring the repair agreement and any receipts or invoices that were promised. Run the major systems that can reasonably be checked, including heat or air conditioning depending on the season, faucets, toilets, appliances that convey, garage doors, and lights. Look in the attic, basement, crawlspace access area, and under sinks when relevant. If the seller has moved out, this is also the moment when a concealed leak or newly visible wall damage often becomes apparent.

    A problem at the walk-through does not always mean the transaction should collapse. It may support a holdback, a repair before signing, a credit, or a written agreement for a specific cure. The right response depends on the issue, your financing, timing, and appetite for uncertainty. What should not happen is a verbal promise replacing a written solution.

    Funding the Purchase Without Creating a Preventable Problem

    Wire fraud remains one of the most avoidable closing risks. Criminals can impersonate agents, lenders, title companies, and even family members with convincing email addresses and altered payment instructions. Never rely on emailed wiring instructions alone. Call a known, independently verified phone number for the settlement office and confirm instructions verbally before sending funds. Do not use a number contained in the suspicious message.

    Your lender will also care about the source of funds. Avoid large unexplained deposits, new credit accounts, vehicle purchases, job changes, or transfers that cannot be documented during the final stretch to closing. A gift from a family member can be acceptable, but it generally needs to be documented in the format your lender requires. The rule is simple: do not make your financial file harder to underwrite after it is already approved.

    Bring the identification and certified funds, if required, that the settlement agent has specifically requested. Ask in advance whether a wire, cashier’s check, or other method is acceptable. Personal checks are often not appropriate for the final balance.

    Signing Day and the First Week of Ownership

    At closing, expect to sign the settlement statement, loan documents if financed, deed-related acknowledgments, title affidavits, and tax or occupancy forms. Take your time with documents that create ongoing obligations, particularly the promissory note, mortgage, and any homeowners association materials. Ask questions before signing, not after the recording queue has started.

    Keys, garage remotes, gate codes, mailbox information, warranties, and security-system details should be accounted for. Possession is usually delivered at closing, but the contract controls. If the seller remains in possession after closing, a written post-closing occupancy agreement should address dates, insurance, deposits, utilities, condition, and consequences if the move-out is delayed.

    Once the deed is recorded, keep your closing package in a secure place. Change exterior locks or rekey them, update alarm access, transfer utilities, and photograph the property condition on day one. For acreage or rural property, locate shutoffs, septic records, well equipment, boundary markers, and any shared-road contacts before an urgent repair forces the issue.

    A disciplined closing is not about making a complicated process feel ceremonial. It is about leaving the table with clean title, correct figures, documented repairs, understood obligations, and a property you can actually operate on the morning after you buy it.
  • Lexington Multifamily Investing That Holds Up

    Lexington Multifamily Investing That Holds Up

    A fourplex near the University of Kentucky can look exceptional on a spreadsheet and still be the wrong acquisition. The asking rents may be plausible, the location may be familiar, and the gross yield may look better than a comparable single-family rental. But Lexington multifamily investing is won or lost in the details behind those numbers: lease quality, utility configuration, deferred maintenance, tenant turnover, parking, zoning, and the realistic cost of bringing an older building into dependable operating condition.

    That is especially true in a market where housing demand comes from several distinct sources. University and hospital employment, state government, professional services, equine industry activity, and regional in-migration all support rental demand. They do not, however, support every property in the same way. A duplex in Chevy Chase, a small apartment building near campus, and a workforce-oriented asset on the east side are not interchangeable investments simply because each has multiple units.

    Start With the Tenant, Not the Unit Count

    The first question is not whether a property has two, four, or 20 doors. It is who rents there, why they choose that location, and what alternatives they have when a lease ends.

    Near the university, tenant demand can be deep but turnover is often built into the operating model. Student-oriented properties may require more frequent leasing, more wear on interiors, and a sharper approach to parental guarantors, roommate changes, and pre-leasing. A building that performs well under active management can produce disappointing results when treated like a passive hold.

    In established in-town neighborhoods, tenants may value walkability, neighborhood character, and proximity to employment centers. Those renters can be durable, but older housing stock often comes with older systems. The market may reward a thoughtful renovation, yet the work must be priced against the building’s construction, access constraints, historic considerations, and achievable rent ceiling.

    Further from the urban core, the investment case may rest on affordability and access to employment corridors rather than lifestyle amenities. These properties can provide steadier tenancy, but investors should test the local renter pool instead of assuming a lower acquisition price creates a margin of safety. Nearby competing inventory, household income, transit or commuting patterns, and the condition of surrounding properties all matter.

    A useful underwriting file separates market rent from current rent and from truly collectible rent. Those are three different figures. A unit advertised at a certain price is not necessarily leased at that price, and a signed lease is not the same as consistent cash received.

    Lexington Multifamily Investing Is Submarket Specific

    Lexington is compact enough to feel familiar and varied enough to punish broad assumptions. A property one mile away can serve a different renter profile, sit in a different school context, or compete against a newer and better-appointed inventory set.

    Campus and medical employment corridors

    Properties near the University of Kentucky, UK HealthCare, and downtown employment centers can benefit from reliable demand drivers. The trade-off is that acquisition pricing often reflects that visibility. Investors should not pay a premium simply because a property is close to campus. Examine the walkability of the specific block, parking availability, bedroom count, unit layout, safety perception, and the condition of competing rentals.

    A two-bedroom unit with off-street parking may attract a different tenant than a similarly sized unit requiring street parking and a longer walk. In small multifamily, those distinctions can materially affect vacancy and turnover expense.

    Established neighborhoods and infill locations

    Older duplexes, triplexes, and converted homes are common in desirable Lexington neighborhoods. They can be attractive because land is limited and replacement cost is high. They can also hide the most expensive problems: aging sewer laterals, galvanized plumbing, insufficient electrical service, foundation movement, roof transitions, and poorly documented additions.

    Sewer first, always. A sewer scope is a modest diligence expense compared with the cost and disruption of replacing a failed line under a driveway, mature landscaping, or an occupied building. The same principle applies to electrical panels, main water lines, drainage, and shared mechanical systems. Cosmetic renovation is easy to see. Infrastructure is where the real operating risk sits.

    Outer-ring and value-oriented locations

    Properties in less central locations may offer more favorable entry pricing or larger unit counts for the capital deployed. The question is whether the property is priced correctly for its tenant base and its physical condition. A lower rent does not excuse unreliable collections, chronic vacancy, poor layout, or a building that will require repeated capital infusions.

    The better opportunity is often a property with a clear, limited business plan: correct below-market rents, improve unit condition without overbuilding, repair known systems, and professionalize management. The weaker opportunity is the one marketed as “value-add” without a credible explanation of what value can actually be added.

    Underwrite Operations as Carefully as Purchase Price

    Small multifamily is frequently sold on gross rent multiplier, cap rate, or a simple cash-flow estimate. Those shortcuts can be useful for an initial screen. They are not a purchase decision.

    Begin with trailing operating statements, then reconstruct them. Verify rent rolls against leases and bank deposits where appropriate. Identify which utilities are owner-paid, whether tenants reimburse any portion, and whether common-area electric, water, trash, lawn care, snow removal, pest control, or laundry equipment are included in the expense history. In a four-unit building, one incorrectly assumed utility line can change the investment materially.

    Property taxes deserve separate attention. A sale can trigger a reassessment or otherwise alter the tax picture, and historical taxes may not reflect the new basis. Insurance should be quoted for the asset as it will be owned, not copied from a seller’s older policy. For buildings in older neighborhoods, ask whether replacement-cost coverage, ordinance and law coverage, and deductibles are sufficient for the actual structure.

    Set aside reserves for capital expenditures even when the seller says the building has been “well maintained.” A property can be clean, occupied, and still be approaching major expenditures. Roof age, HVAC age, windows, paving, water heaters, retaining walls, and exterior wood condition should be documented, dated, and interpreted. If the inspection identifies a concern, convert it into a cost range and a timing assumption before removing contingencies.

    Management is another line item investors routinely underestimate. Self-management can work for an owner with nearby operations, maintenance capacity, and the appetite for tenant communication. It is less compelling when the investor lives out of state, owns a demanding business, or acquires a tenant profile with high turnover. The right question is not whether management can be avoided. It is what the asset requires to perform well and whether that requirement is fully funded.

    Financing Can Change the Deal More Than the Rent Increase

    Two-to-four-unit properties can sometimes be financed differently from larger apartment buildings, particularly when an owner intends to occupy one unit. That may create a more accessible path into multifamily ownership, but it does not eliminate the need for disciplined underwriting. Owner-occupancy rules, reserve requirements, appraisal standards, debt-service coverage expectations, and lender treatment of projected rents all need to be understood early.

    For a five-unit or larger acquisition, commercial financing commonly places more weight on the property’s income, borrower experience, liquidity, and debt-service coverage. Loan terms, rate structure, prepayment provisions, recourse, and future refinance assumptions deserve the same scrutiny as the property itself. A deal that works only after an aggressive refinance or a perfect rent-growth assumption is not a conservative acquisition.

    Investors using a 1031 exchange have an additional constraint: the identification window can create pressure to buy quickly. That pressure is understandable, but it is not a reason to waive building-level diligence. A replacement property must still fit the investor’s long-term hold strategy, tax posture, operational capacity, and risk tolerance.

    Make Diligence Physical, Financial, and Legal

    A strong inspection is necessary, not sufficient. For multifamily, diligence should connect physical findings to the rent roll and operating statement. If three units have window air-conditioning, for example, confirm electric capacity and tenant utility responsibility. If a building has separate meters, verify that the meter configuration matches the leases and actual unit layout. If the seller reports recent renovations, ask what was permitted, who completed the work, and whether invoices or warranties are available.

    Review leases for renewal dates, security deposits, concessions, pet terms, utility responsibilities, notice periods, and any informal arrangements that may not appear on the rent roll. Walk every unit when possible. A vacant model unit tells very little about how occupied units have been maintained.

    Then review the legal and site context. Confirm zoning, unit count, parking compliance, access, easements, flood considerations, and any local restrictions relevant to the current use. Converted homes are particularly worth examining closely. The building may have functioned as multifamily for years, but investors should understand how the use is documented and what constraints could affect future renovation, rebuilding, or financing.

    The Best Deal Is Usually the One You Can Explain Clearly

    Good Lexington multifamily acquisitions rarely depend on a clever spreadsheet formula. They depend on buying a specific building at a defensible basis, for a known renter pool, with enough capital to correct what is wrong and operate it properly afterward.

    Before making an offer, write the investment case in plain language. State why tenants will choose the property, where rent growth will come from, which repairs are required, what could interrupt cash flow, and what return remains if the optimistic case never arrives. If that explanation is vague, the property is not ready to buy. If it is clear, dated, and supported by the building itself, you have the kind of discipline that tends to hold up long after closing.

  • EKU Off Campus Housing Guide for Richmond Renters

    EKU Off Campus Housing Guide for Richmond Renters

    A lease can look inexpensive until the first utility bill, parking charge, roommate dispute, or August move-in problem arrives. This EKU off campus housing guide is built for the practical questions that matter before you commit: where you will live, how you will get to campus, what the lease actually requires, and whether the monthly number still works after every recurring cost is counted.

    Eastern Kentucky University gives students and university-affiliated households a compact campus setting, but Richmond rental choices spread well beyond the blocks nearest campus. A good decision is rarely about finding the lowest advertised rent. It is about matching location, lease structure, property condition, and transportation to the way you will actually live for the next 10 to 12 months.

    Start With Your Real Monthly Housing Cost

    Advertised rent is only the starting point. Ask for a written breakdown of what is included and what is billed separately. In many rentals, tenants may be responsible for electricity, water, sewer, trash, internet, renter’s insurance, parking, and sometimes a monthly administrative or pest-control fee. A house shared by several tenants can also have a very different utility profile than an apartment with newer systems and better insulation.

    Build a monthly ceiling before touring. Include rent, expected utilities, transportation, groceries, and a reserve for move-in costs. The security deposit, first month’s rent, application fee, utility deposits, furniture, and moving supplies can make the first month materially more expensive than the months that follow.

    If parents are contributing or co-signing, have the financial conversation early. A guarantor may be responsible for more than one student’s share of rent. In a joint lease, one roommate’s missed payment can become everyone else’s problem, depending on the lease language.

    Choosing an Area for EKU Off Campus Housing

    Richmond is not one uniform rental market. The right area depends on whether walking to campus, keeping a car, working off campus, or living with roommates matters most.

    Near campus and downtown Richmond

    Housing near EKU and downtown can appeal to renters who want a shorter campus trip and easier access to restaurants, services, and university activity. The trade-off may be older housing stock, more varied maintenance histories, limited off-street parking, or smaller floor plans. Older homes can be appealing and perfectly functional, but they deserve a closer look at windows, heating and cooling, drainage, electrical outlets, and laundry arrangements.

    Do not assume a listing described as close to campus is an easy walk in every season or at every hour. Drive or walk the actual route. Note sidewalks, crossings, lighting, hills, and the time required with a backpack, groceries, or bad weather.

    Eastern Bypass and retail-oriented corridors

    Apartment communities and newer rental options along the Eastern Bypass and Richmond’s commercial corridors often make sense for renters who drive, work part-time, or want convenient access to groceries and daily services. These locations can offer more predictable parking and modern layouts, but the campus commute may be less convenient without a car.

    For these properties, ask whether parking is assigned, whether guests need permits, and whether towing is actively enforced. A unit with two bedrooms is not automatically designed for two vehicles.

    Residential areas farther from campus

    A house or duplex farther from EKU can provide more space, a yard, or a quieter separation from campus life. It can also create a transportation dependency. Calculate the commute rather than treating it as an afterthought. Fuel, maintenance, insurance, and the inconvenience of moving a car for every errand can outweigh a modest rent difference.

    Avoid broad neighborhood labels or assumptions. Evaluate the specific property, the route you will use, the lease terms, and your own daily schedule. That is more useful than a generalized ranking of one part of Richmond against another.

    Read the Lease Like It Is a Financial Document

    Because it is one. A lease governs far more than rent due dates. Before signing, confirm the lease start and end date, renewal terms, late fees, notice requirements, guest rules, pet rules, parking rules, maintenance procedures, and the policy for subletting or replacing a roommate.

    The most consequential question for many EKU renters is whether the lease is joint and several or individual by bedroom. Under a joint lease, the landlord may generally seek the full amount due from any tenant named on the agreement. An individual lease can limit that exposure, but it may carry a higher rent or different utility structure. Neither arrangement is automatically better. It depends on how well you know your roommates and how much financial risk you are willing to accept.

    Pay close attention to automatic renewal provisions. Some leases require notice 30, 60, or more days before the end date if you do not intend to renew. Missing that deadline can reduce your options for the following year.

    Ask how maintenance requests are submitted and what qualifies as an emergency. Then test the unit before move-in. Run faucets, flush toilets, operate appliances, check every outlet you can reasonably access, and look under sinks. Sewer first, always: slow drains, recurring odors, water staining, or soft flooring near bathrooms deserve documentation before keys change hands.

    Tour for Condition, Not Just Layout

    A staged model unit or a quick showing can hide operational details. During a tour, assess the actual unit you would lease whenever possible. Look for water marks on ceilings, damaged screens, loose handrails, window operation, visible pests, and evidence of rushed repairs. Notice whether doors close properly and whether bedrooms have practical storage and outlets.

    For a house, inspect the exterior as well. Gutters, grading, steps, porches, exterior lighting, and the condition of driveways affect daily living. In Richmond’s wet periods, drainage is not cosmetic. Water that is not directed away from a building has a way of becoming an interior problem.

    At move-in, take dated photos and video of every room, including existing damage, appliance condition, and meter readings where applicable. Submit the landlord’s move-in checklist promptly and retain a copy. This is not adversarial. It creates a clear record when the security deposit is reconciled later.

    Roommates Need Written Ground Rules

    A compatible friend is not necessarily a compatible roommate. Before applying together, discuss budgets, visitors, cleaning, pets, overnight guests, parking, noise, shared purchases, and what happens if one person wants to leave early.

    Put your agreement in writing, even if it is informal. Decide how utilities will be divided, whose name is on each account, and when reimbursements are due. If one roommate is the sole account holder for internet or electricity, the others should understand the consequence if payments are late.

    The same principle applies to furnishings. A shared living-room sofa is simple until the lease ends. Clarify who owns what before money changes hands.

    Timing Matters More Than Most Renters Expect

    Richmond’s student-oriented rental cycle can tighten well before the next academic year begins. Waiting until summer may produce a few opportunities, but it can also mean fewer layouts, less choice in roommate configurations, and more pressure to sign quickly. Start researching early enough to compare several properties, not merely accept the first available unit.

    That does not mean signing sight unseen months in advance is always wise. If you are relocating from outside Kentucky, request a live video tour of the exact unit, read the lease before paying a nonrefundable fee, and verify who manages the property. Dated information matters. A review from years ago or an old online listing tells you less than current lease terms, current photos, and a direct answer about the unit you are being offered.

    When Renting May Not Be the Only Option

    For a typical undergraduate timeline, renting is usually the cleaner choice. Buying a condo, townhome, or small house can introduce financing costs, maintenance exposure, resale risk, and management obligations that do not fit a short stay.

    The analysis changes for a household planning to remain in Richmond for several years, a faculty or staff relocation, or a family considering housing for multiple students over time. In those cases, compare ownership costs against rent with conservative assumptions for repairs, insurance, taxes, vacancy, and resale. A property should work as a home first and an investment only after the numbers have been sourced, dated, and interpreted.

    Marcos Gil Realty can provide local housing guidance for buyers and relocating households whose EKU connection extends beyond a single lease term.

    The right Richmond rental should feel manageable after move-in, not merely exciting on tour day. Give yourself enough time to inspect the property, read every obligation, and price the full monthly commitment. That discipline leaves more room for the part of college housing that should matter most: having a dependable place to come home to.

  • How to Inspect Historic Homes Before You Buy

    How to Inspect Historic Homes Before You Buy

    A historic home can make an ordinary showing feel decisive: heart-pine floors, tall windows, original millwork, a front porch that belongs to the street rather than the driveway. But knowing how to inspect historic homes means looking past the details that photograph well. The question is not whether an older house has quirks. It will. The question is whether its systems, structure, drainage, and past repairs support the price, your intended use, and the work ahead.

    In Central and Eastern Kentucky, that work often begins below grade. Many older Lexington and Richmond homes sit on aging sewer laterals, stone or early concrete foundations, and sites where decades of water management have been improvised one repair at a time. A period-appropriate restoration can be worthwhile. An unpriced infrastructure problem is not character.

    How to Inspect Historic Homes Before the General Inspection

    Start during the showing, before emotion outruns observation. Walk the exterior slowly from the street to the rear lot. Look at roof lines, gutters, downspouts, grading, retaining walls, porch columns, masonry joints, and the condition of painted wood. Water is the common thread. It enters through failed roofs and flashing, migrates through neglected gutters, pools against foundations, and damages framing long before a room looks compromised.

    Pay attention to the ground around the house. Soil should generally move water away from the foundation, not toward it. Downspouts that empty at the base of a wall, low spots beside the house, stained foundation masonry, and damp basement odors all deserve follow-up. In Kentucky’s freeze-thaw cycles and heavy rain events, a modest drainage issue can become a persistent basement or crawlspace problem.

    Inside, use your senses without trying to become the inspector. Does the house smell damp, heavily fragranced, or freshly painted in only one location? Are there stains at ceiling corners, bubbling plaster, uneven flooring, or doors that no longer latch? Each can have an ordinary explanation. Together, they create a pattern worth investigating.

    Original plaster deserves a careful reading. Fine cracking can be normal in a house that has settled over a century. Broad cracks, separation from lath, recurring staining, or a wall that feels loose may point to moisture, movement, or deferred repair. Do not assume drywall over old walls means the issue was resolved. Sometimes it merely means it was covered.

    Put Structure and Water Ahead of Cosmetic Work

    Historic houses were built with materials and methods that differ substantially by era. A 1910 foursquare, a Victorian cottage, and a mid-century ranch may all be considered older homes, but they call for different questions. The inspection should identify what is original, what has been altered, and whether the alterations were competently executed.

    Foundation evaluation is especially important. Stone foundations can perform well for generations when mortar, drainage, and ventilation are maintained. Problems arise when hard modern mortar traps moisture in softer historic masonry, when walls bow under soil pressure, or when prior owners have patched movement without addressing its cause. Ask the inspector to distinguish cosmetic cracking from active displacement. If conditions warrant it, bring in a structural engineer rather than relying on a broad verbal opinion.

    The roof should be evaluated as a system, not just by age. Ask about remaining life, flashing at chimneys and dormers, ventilation, visible decking condition, and any evidence of past leaks in the attic. Slate, standing-seam metal, and wood shingles may be historically appropriate and long-lived, but repair requires specialists and costs can be materially different from an asphalt replacement. That is not automatically a reason to walk away. It is a reason to budget accurately.

    Porches also deserve more than a quick glance. Their columns, railings, decking, steps, and roofs are exposed on every side. Rot at the bottom of a column may be repairable; widespread framing deterioration can become a substantial project. Confirm whether a previous repair preserved load-bearing function or simply improved the appearance from the sidewalk.

    Sewer First, Always

    For older homes connected to public sewer, a sewer scope is a separate due-diligence item, not an optional add-on. Sewer first, always. A standard home inspection may identify slow drains or visible plumbing concerns, but it does not show the condition of the lateral line running from the house to the public connection.

    Older properties may have clay tile, cast iron, Orangeburg, or mixed piping, sometimes with roots at joints, bellies, offsets, cracks, or partial collapses. A line can appear functional during a brief inspection and still be near the end of its useful life. The scope should include video, location information where possible, and a written assessment of recommended repair or replacement.

    If the property uses a septic system, the process changes. Ask for system records, confirm the location and capacity of the tank and field, and arrange a septic inspection suited to the system type. For rural historic homes, also verify the water source, well components, pump age, water quality, and any shared-road or access obligations. A beautiful farmhouse without clear utility and access facts is not yet a fully understood purchase.

    Inspect Electrical, Plumbing, and Heating as Working Systems

    Period details should never distract from life-safety systems. Older electrical panels, limited service capacity, ungrounded outlets, knob-and-tube wiring, cloth-covered conductors, or amateur additions need direct evaluation by a licensed electrician. Some older wiring can remain serviceable in limited conditions; insurers and lenders may take a different view, particularly when renovation plans involve new loads, electric vehicle charging, or a larger HVAC system.

    Plumbing requires the same discipline. Galvanized supply lines can corrode internally and reduce water pressure. Cast-iron drains may be nearing replacement age. Look for active leaks beneath sinks, evidence of past water damage around bathrooms, and shutoff valves that actually operate. If a home has been renovated, ask whether supply and drain lines were replaced throughout or only where walls were opened.

    Heating and cooling should be assessed for condition, capacity, and distribution. Historic homes often have rooms added over time, and those additions may be uncomfortable because ductwork, insulation, or equipment sizing was never reconsidered. A newer furnace sticker is useful information, but it is not the whole answer. Ask whether the system heats and cools the entire house evenly and whether the electrical service can support future upgrades.

    Understand Windows, Lead Paint, and Preservation Rules

    Original wood windows are often treated as a binary choice: replace them all or keep them at any cost. The better answer depends on their condition, energy goals, historic value, and repairability. Well-maintained original windows, combined with weatherstripping and storm windows, can perform better than many buyers expect. Full replacement may make sense where units are badly deteriorated, but it can change the home’s appearance and may be restricted in designated historic districts.

    Lead-based paint is common in homes built before 1978. The federal disclosure requirement is familiar to many buyers, but the practical issue is condition. Intact painted surfaces present a different risk profile than peeling trim, friction surfaces around windows and doors, or renovation work that creates dust. If children will live in the home or major work is planned, seek appropriate testing and use contractors trained in lead-safe practices.

    Before committing to exterior changes, verify whether the property is within a local historic district or subject to neighborhood preservation standards. Rules may affect windows, doors, roofing materials, siding, additions, and even paint-related exterior work. These standards protect streetscape value, but they can add review time and limit inexpensive substitutions. Buyers should understand that trade-off before inspection deadlines pass, not after a contractor has been hired.

    Read the Renovation History, Not Just the Finish Schedule

    Ask for permits, invoices, warranties, contractor information, and before-and-after photos when they exist. The goal is not to demand a perfect archive. It is to determine whether significant work was planned, permitted where required, and completed with a coherent approach.

    Be cautious with renovated historic homes that look uniformly new but offer little documentation. Fresh cabinetry and polished fixtures can coexist with old wiring behind walls, unresolved drainage, or a basement that was cosmetically finished around moisture problems. Conversely, a house with visible age and documented stewardship may be the more dependable opportunity.

    Your inspection period should give you time to obtain specialist opinions where the general inspection raises questions. That may include a structural engineer, roofer, chimney professional, electrician, plumber, HVAC contractor, pest specialist, sewer-scope provider, or preservation-minded window contractor. Use the findings to decide whether to proceed, renegotiate, request repairs, or reserve capital for work after closing. The right path depends on the home’s price, rarity, condition, and your appetite for management.

    A well-bought historic home is not one without defects. It is one whose defects are sourced, dated, and interpreted before you own them. Keep the inspection focused on water, structure, sewer, safety, and documentation, then let the architectural details earn their place in the decision.

  • What Is a Sewer Scope Inspection for Homebuyers?

    What Is a Sewer Scope Inspection for Homebuyers?

    A polished kitchen, fresh paint, and a clean general inspection can still leave one expensive question unanswered: what is a sewer scope inspection, and what is happening below the ground between the house and the public sewer? For buyers, especially those considering older Lexington or Richmond homes, the answer can materially change the cost and terms of a purchase. Sewer first, always.

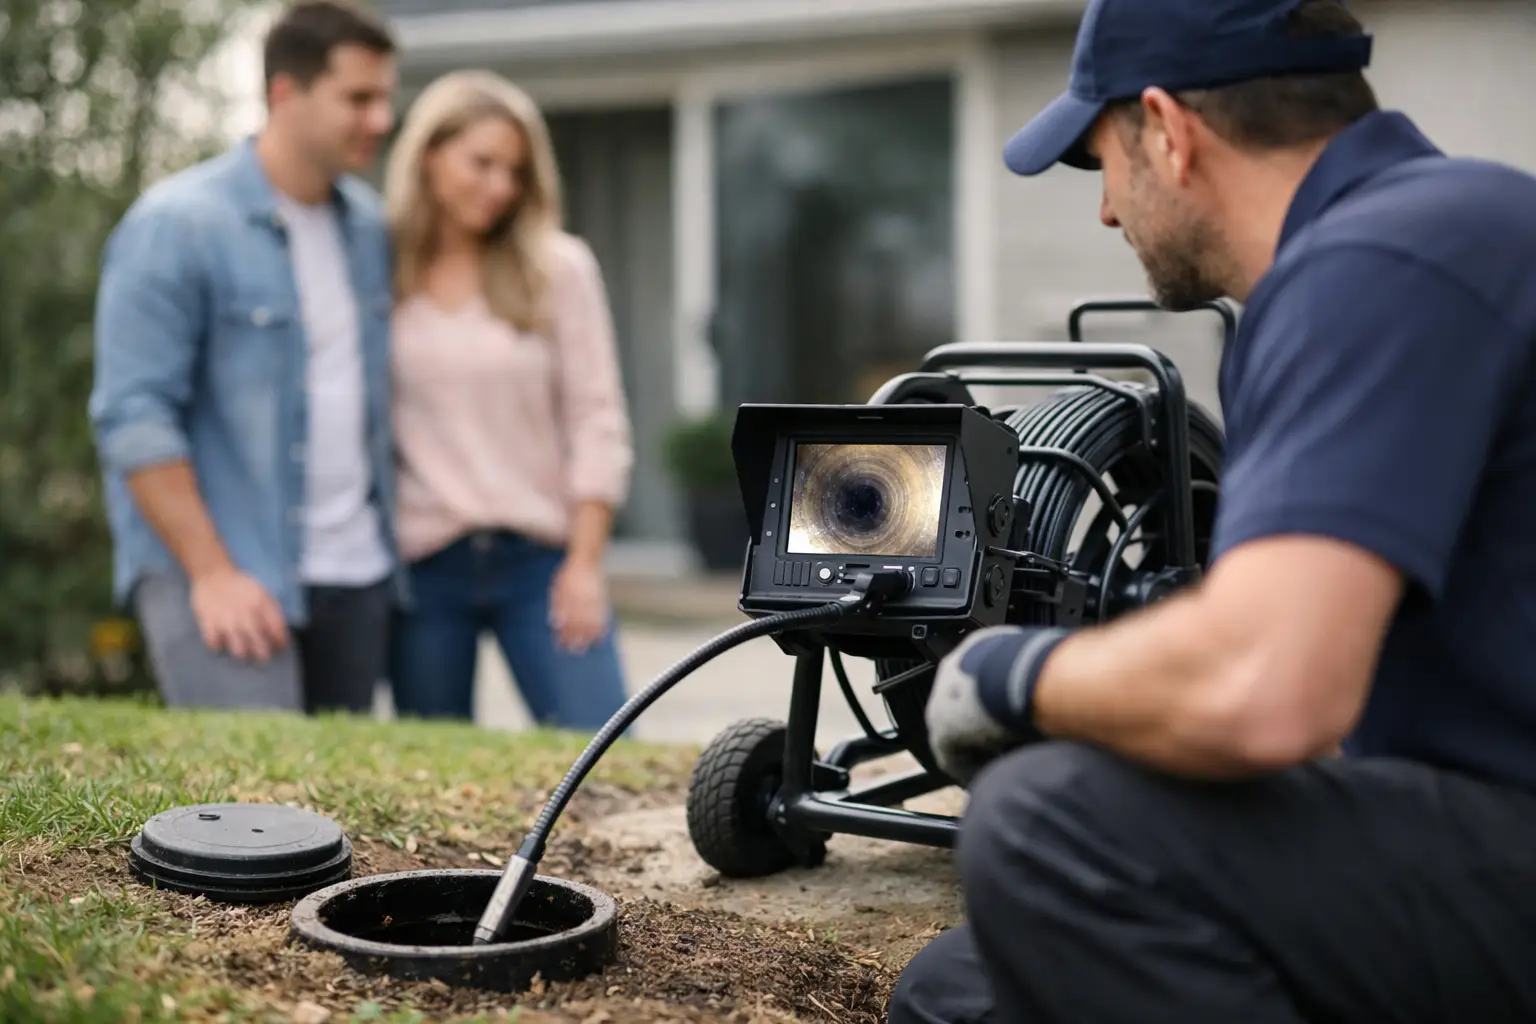
    A sewer scope inspection uses a specialized waterproof camera to view the private sewer lateral – the pipe that carries wastewater from the home to the municipal sewer connection. A technician feeds the camera through an accessible cleanout, records the line, and identifies visible defects, blockages, and pipe conditions that a standard home inspection cannot see.

    It is not glamorous due diligence. It is often some of the most useful due diligence on the property.

    What a Sewer Scope Inspection Actually Covers

    The camera travels through the drain line, typically from a cleanout near the home or in the basement, toward the street connection. The technician watches a live feed and usually provides video, photos, a written finding, or some combination of the three. Good reporting identifies the approximate location of a concern, the direction of the camera, and the distance from the access point.

    The scope is intended to evaluate the condition of the visible sewer lateral. It can reveal roots, separated joints, crushed sections, heavy buildup, standing water, poor connections, and obsolete pipe materials. It may also show whether the line appears to be flowing normally at the time of inspection.

    That last phrase matters. A camera is a visual inspection, not a guarantee that the line will never back up. It may not reveal every defect behind a heavy deposit, a section obscured by water, or a problem that only appears under unusual volume. Still, it gives a buyer far more evidence than assuming the pipes are fine because the toilets flushed during a showing.

    Why the General Home Inspection Is Not Enough

    A capable home inspector will test fixtures, observe drainage, and note obvious signs of plumbing trouble. They do not typically run a camera through the buried lateral as part of a standard inspection. The underground line may extend dozens of feet beyond the foundation, through landscaping, driveways, sidewalks, or public right-of-way areas.

    The home can look entirely sound while that line is compromised. A slow drain may be a minor maintenance issue. It may also be the first signal of root intrusion or a deteriorating clay line. By the time sewage backs up into a lower-level bathroom, the repair conversation is no longer theoretical.

    For a purchase, the distinction is straightforward: the general inspection tells you how the home is performing at the surface. A sewer scope helps establish what is happening in one of its least visible and potentially most disruptive systems.

    Common Findings in Central and Eastern Kentucky Homes

    The age of a home is a useful screening tool, but it is not the whole story. A newer house can have construction debris, a poorly aligned connection, or damage from settlement. An older house may have a well-maintained line that still has years of service left. The camera evidence, sourced and dated, should lead the decision.

    In Lexington, Richmond, and established small-town neighborhoods across the corridor, these are the findings that most often deserve attention:

    • Root intrusion: Tree roots can enter at joints or small cracks, particularly in older clay or cast-iron lines. Roots may be cleared, but repeated intrusion usually points to a joint or pipe condition that needs a longer-term plan.
    • Offset or separated joints: Sections of pipe shift over time due to settlement, age, or installation issues. Waste can catch at the opening, increasing the chance of blockage.
    • Bellies or standing water: A low section of pipe holds water rather than draining fully. The severity depends on the amount of standing water, pipe material, flow, and whether solids are collecting there.
    • Cracks, breaks, or a collapse: These findings can range from localized repairs to full replacement. The exact location, depth, access, and surface restoration needs drive the cost.
    • Orangeburg, clay, or deteriorating cast iron: Older materials are not automatic deal-breakers, but they require informed budgeting. Orangeburg, a fiber-based pipe used in parts of the mid-20th century, is particularly worth evaluating closely because it can deform and fail with age.

    A report that merely says “roots present” is incomplete for negotiation purposes. Buyers need to know how extensive the roots are, whether the line is backing up, whether the pipe is visibly damaged, and where the concern sits. A defect under open lawn is a different project from one beneath a driveway, mature landscaping, or a finished addition.

    When Should a Buyer Order a Sewer Scope?

    For many properties connected to public sewer, the practical answer is during the inspection period. The cost is modest compared with the cost of replacing a lateral, and it gives the buyer time to request repairs, negotiate a credit, revise the offer strategy, or walk away when the contract permits.

    A scope is especially sensible when the home is older, the seller has limited maintenance history, large trees sit near the route to the street, drains have been slow, or the property has a finished basement. It is also prudent when a home has been renovated extensively. New kitchens and baths do not necessarily mean the buried sewer line was replaced.

    Investors should be particularly disciplined. A sewer failure can interrupt a tenant’s occupancy, create an emergency repair, and damage returns during the first year of ownership. For a Red River Gorge cabin or rural property, first determine whether the home is on public sewer at all. A sewer scope does not replace a septic inspection, tank evaluation, or assessment of the drain field. Those are separate systems with separate risks.

    How to Read the Results Without Overreacting

    Not every unfavorable observation requires a seller-funded replacement. This is where judgment matters.

    A few fine roots in an otherwise intact, flowing line may justify cleaning and periodic maintenance rather than a demand for a new lateral. A moderate belly may deserve a contractor opinion and a repair reserve, particularly if the line is flowing and there is no evidence of recurring blockage. A visible collapse, severe offset, or extensive deterioration is a different category. Those conditions deserve a qualified sewer contractor’s written repair recommendation before the inspection deadline expires.

    Ask for the video, not just a verbal summary. Confirm the footage is from the subject property, and review whether distances were documented. If the technician cannot access the line because there is no cleanout or because the opening is inaccessible, that is itself useful information. Installing a cleanout may be a worthwhile request or future improvement, since it provides a practical point for maintenance and emergency service.

    Buyers should also separate immediate health or function concerns from future capital planning. A line can be serviceable today yet nearing the end of its expected life. That does not always mean the seller must replace it. It does mean the purchase price, cash reserves, and ownership plan should reflect the risk honestly.

    What Findings Mean for Negotiation

    A sewer scope is not a tool for reopening every negotiated point. It is evidence for addressing a documented condition that was not visible during normal review. The cleanest path is usually to obtain a clear contractor estimate, understand whether repair or replacement is recommended, and compare that work with the property’s price and competing options.

    Depending on the contract, the parties may agree to a repair before closing, a credit, a price adjustment, or no change at all. Credits can give a buyer control over the contractor and timing, but they also require enough cash after closing to complete the work. Seller repairs can reduce immediate expense, yet buyers should understand the scope of work, permits if applicable, and whether pavement, landscaping, or other surfaces will be restored.

    Responsibility can become less clear near the public connection. In many locations, the owner is responsible for the private lateral, sometimes extending to the point of connection, but local rules and the precise location of the defect matter. Do not rely on assumptions. Verify the municipal utility’s standards and obtain a contractor’s assessment before assigning responsibility in a negotiation.

    A Small Inspection With a Large Practical Value

    The best time to learn about an aging sewer lateral is before closing, when there are still choices. A camera inspection cannot make an older property new, and it should not erase the value of a well-located home with strong bones and a manageable repair plan. It simply replaces guesswork with a clearer record.

    For Kentucky buyers, that is the point of disciplined due diligence: understand the condition beneath the landscaping, price the risk appropriately, and move forward with eyes open rather than hoping the next flush does not become the first emergency.

  • New Construction Contract Kentucky Guide

    New Construction Contract Kentucky Guide

    A model home can make a new build feel settled long before it is legally or physically complete. The new construction contract Kentucky guide buyers need begins with that distinction: the builder’s sales process is designed to move you from lot selection to deposit, while the contract determines what you are actually buying, when you must perform, and what happens if the build changes course.

    In Central and Eastern Kentucky, the differences can be material. A Lexington infill home, a Richmond subdivision build, a farm-adjacent custom residence in Madison County, and a cabin near the Red River Gorge may all be called new construction. Their utility arrangements, site conditions, lender requirements, access issues, and construction timelines can be very different. The contract should reflect the property in front of you, not merely the builder’s standard form.

    Start With the Builder’s Contract, Not the Model Home

    Most production and semi-custom builders use their own purchase agreements. Unlike a resale transaction, where the parties often begin with a familiar statewide form and negotiate around it, a builder contract is usually drafted for the builder’s process. It may limit the buyer’s remedies, set narrow cancellation rights, define allowances broadly, and give the builder substantial discretion over substitutions and completion timing.

    That does not make the contract unreasonable. It does mean the buyer should read it as an operating document, not a brochure attachment. The floor plan, included-features sheet, lot exhibit, upgrade selections, financing addendum, warranty materials, and community documents should all be identified and retained. If a sales representative says a feature is included, ask where it appears in writing. A conversation about a covered patio, quartz level, appliance package, retaining wall, or fence has little value if the contract and exhibits say otherwise.

    Before signing, separate three categories: what is included in the base price, what is an upgrade with a fixed price, and what is an allowance or a future decision. Allowances deserve extra attention. They can be appropriate for lighting, tile, landscaping, or finishes that have not been selected. But an allowance is not a guaranteed final cost if actual selections exceed it. Ask who approves overages, when they are due, and whether labor, delivery, taxes, and installation are included.

    The New Construction Contract Kentucky Buyers Should Review Closely

    A purchase price is only one line of the transaction. The most consequential provisions often sit in the timelines, contingencies, and remedy language.

    Deposit and earnest money terms

    Know the deposit amount, when it becomes nonrefundable, and who holds it. Some builders use an earnest money structure that becomes nonrefundable shortly after signing, even when construction has not started. Others permit refunds only for a narrowly defined financing failure. A large deposit can be sensible for a highly customized home, but it changes the buyer’s exposure if employment, lending, or life plans shift.

    Ask whether the deposit is applied to the purchase price, whether upgrade deposits are treated differently, and what happens if the builder cannot deliver the home. The contract should be clear about the buyer’s remedy if construction is abandoned, materially delayed, or completed in a substantially different form than promised.

    Financing is not the same as preapproval

    A lender’s preapproval is a useful first screen, not a guarantee that financing will be available at closing. With new construction, months can pass between contract and loan application completion. Credit changes, debt-to-income ratios, rates, appraisal conditions, insurance costs, and employment changes can all affect approval.

    Many builders offer incentives for using a preferred lender or title company. The incentive may be worthwhile, particularly when it offsets closing costs or provides a pricing concession. Still, compare the total loan cost and the contractual protections. The right question is not whether the preferred lender is good or bad. It is whether the offer is competitive and whether the financing contingency gives you a realistic path out if the loan does not come together.

    Pay close attention to any financing deadline. A contract can require the buyer to apply within a short window, provide documents promptly, and accept a loan within stated terms. If rates move beyond your comfort level, a rate-lock strategy and a written conversation with the lender matter more than optimistic assumptions.

    Construction timing and the meaning of completion

    Builders commonly provide an estimated completion date rather than a guaranteed one. Weather, labor availability, material delays, permitting, utility work, and change orders can extend a schedule. In Kentucky, prolonged rain can affect grading and exterior work; on rural or sloped sites, driveway, drainage, septic, or utility coordination can add another layer.

    Read how the agreement defines completion. Is it certificate of occupancy, substantial completion, final municipal sign-off, or a date selected by the builder after notice? Also review the outside completion date, if one exists, and the buyer’s remedy if it is missed. A flexible estimate is understandable. An open-ended obligation with no meaningful buyer protection deserves closer review.

    Avoid scheduling a lease termination, movers, school transfer, or sale of your current home solely around a verbal target date. Build time and financial contingency into the larger move plan.

    Changes, substitutions, and site conditions

    The contract should address what happens when a specified material is unavailable or a field condition requires a change. Builders need reasonable substitution rights. A discontinued cabinet pull should not stop a build. But the agreement should distinguish minor substitutions from material changes to layout, square footage, exterior finish, mechanical systems, lot grading, or included amenities.

    For a homesite, do not treat the lot as scenery. Review easements, drainage areas, utility locations, sidewalks, retaining walls, shared drives, and any conservation restrictions. In parts of Central Kentucky, sewer availability and capacity should be confirmed early. Where public sewer is not available, septic suitability, reserve areas, and access easements deserve the same attention. Sewer first, always.

    A home can be beautifully finished and still have a backyard constrained by drainage swales, a utility pedestal in the wrong place, or a slope that makes fencing expensive. The site plan and recorded restrictions often tell that story better than the sales center does.

    Inspections Are Still Worth Having

    A new home should be inspected. Municipal code inspections and builder quality-control reviews serve different purposes from an independent inspector working for the buyer. The local jurisdiction is checking code compliance at specific stages. Your inspector is evaluating visible workmanship, function, safety concerns, and conditions that may warrant correction before closing.

    The ideal inspection strategy depends on the build and the builder’s access rules. For a longer build, a pre-drywall inspection can reveal framing, plumbing, electrical, and mechanical issues before walls are closed. A final inspection shortly before closing documents items for the punch list. If pre-drywall access is not permitted, do not assume you have no options. Confirm the policy before contract signing and plan for a thorough final inspection.

    The contract should make clear whether an inspection contingency exists and what it allows. Some builder forms permit an inspection but not a termination right, limiting the buyer to a repair request. Others require the buyer to submit concerns by a short deadline. That may be acceptable when the builder has a credible correction process, but it should be understood before the deposit is committed.

    At the final walk-through, test more than cosmetic details. Operate windows and doors, run faucets, check appliances, confirm heating and cooling, inspect floors in natural light, and compare installed finishes against signed selections. Photograph unresolved items and obtain a written punch-list process with target dates.

    Warranties, Closing Costs, and the Post-Closing Record

    Most new homes come with some form of builder warranty, often structured around different periods for workmanship, systems, and structural elements. Read the actual warranty, not just the summary. Look for exclusions involving settling, landscaping, moisture, grading, appliances, owner maintenance, and third-party products. Understand the notice procedure. A warranty claim often requires written notice within a defined period and may include mediation, arbitration, or other dispute provisions.

    Closing costs also need a line-by-line review. New construction can involve lender fees, title charges, prepaid taxes and insurance, HOA initiation fees, transfer-related charges, and utility deposits. Incentives may cover some costs but not all. If the builder quotes a closing-cost credit, confirm its permitted uses with the lender and obtain the estimate in writing.

    After closing, preserve the contract, signed plans, change orders, selection sheets, surveys, warranty documents, appliance manuals, permits, and final invoices. That file helps with warranty requests, future maintenance, insurance questions, and eventual resale. A later buyer may care deeply about what was built, who built it, and whether improvements were permitted and documented.

    Use Counsel Early When the Risk Is Meaningful

    A REALTOR® can help compare the contract against the market, organize due diligence, coordinate inspections, and keep the transaction moving. Legal interpretation is different work. If the agreement includes substantial nonrefundable money, broad waiver language, arbitration requirements, a custom-build scope, land complications, or a home-sale contingency, having a Kentucky real estate attorney review it before signing is usually money well spent.

    This is especially true for acreage, rural builds, custom homes, and investment properties. A cabin intended for short-term rental may need a different review of restrictions, road maintenance, utility capacity, and operational assumptions than a primary residence in an established subdivision. The contract cannot solve a bad site or an unworkable business plan, but it can keep those risks visible before they become expensive.

    A well-run new construction purchase is not about distrusting the builder. It is about making the promises, choices, deadlines, and remedies visible on paper. Buy the home you can document, inspect, finance, and operate with confidence.

  • Choosing a Kentucky 1031 Exchange Replacement Property

    Choosing a Kentucky 1031 Exchange Replacement Property

    A Kentucky 1031 exchange replacement property is not simply the next asset that fits the deadline. It must work as an investment after the exchange closes, when the pressure of the 45-day identification window is gone and the actual costs of ownership begin. In Central and Eastern Kentucky, that means looking beyond a cap-rate headline to utility service, access, insurance, deferred maintenance, local rental demand, and the property’s realistic exit options.

    A 1031 exchange can defer federal capital-gains tax when an owner sells qualifying real estate held for investment or business use and acquires qualifying replacement real estate. The rules are strict, the calendar is unforgiving, and the wrong replacement property can turn a tax strategy into an expensive operating problem. The best approach is to begin the replacement-property search before the relinquished property is under contract, with a written acquisition standard rather than a last-week scramble.

    What Qualifies as a Kentucky 1031 Exchange Replacement Property?

    For most investors, the core question is use. Both the relinquished property and replacement property generally must be held for investment or productive use in a trade or business. A Lexington rental house, Richmond duplex, student-housing asset, commercial building, cabin operated as a genuine rental business, farm leased to an operator, or development land held for investment may qualify depending on the facts.

    A primary residence does not become exchange property because it has appreciated. Nor does a vacation home automatically qualify because it is occasionally rented. Personal use, rental history, intent, operating records, and the duration of ownership all matter. A buyer considering a Red River Gorge cabin should be especially careful here: a property promoted as a short-term rental may have strong personal appeal, but exchange treatment depends on how it is actually held and used, not on the listing description.

    The replacement property does not need to be in Kentucky. Likewise, an investor selling property outside Kentucky may acquire here. What matters is that the real estate meets the federal like-kind standard and the exchange is structured correctly. “Like kind” is broader than many owners assume. An apartment building can be exchanged for land, a rental home for a retail asset, or a commercial property for a portfolio of rentals. The investment logic, however, should be narrower than the tax rule.

    The Dates That Control the Transaction

    The replacement search should begin with two non-negotiable deadlines. After the sale of the relinquished property closes, the exchanger generally has 45 calendar days to identify potential replacement properties in writing. The exchange must generally be completed within 180 calendar days of that sale, or by the due date of the taxpayer’s return, including extensions, if earlier.

    These are calendar days, not business days. A holiday, lender delay, inspection dispute, or seller who suddenly decides not to move does not stop the clock.

    The exchanger also needs a qualified intermediary in place before the relinquished property closes. If sale proceeds are received or controlled by the seller, the exchange can fail. The intermediary holds the proceeds and prepares the required exchange documents, but does not select the asset, validate the investment, or replace legal and tax counsel.

    Identification rules deserve attention before an offer is written. Many investors use the three-property rule, identifying up to three potential replacements regardless of value. Other identification methods exist, but they can become technical quickly. In a thin inventory environment, identifying only one property can be unnecessarily fragile. Identifying three credible alternatives is often more prudent than identifying three aspirational listings with no path to contract.

    Buy for the Exchange, but Underwrite for Kentucky

    A full tax deferral commonly requires buying replacement property of equal or greater value, reinvesting all net equity, and replacing debt paid off at sale with new debt or additional cash. Cash received or debt relief not replaced can create taxable boot. The exact calculation should be reviewed with the exchanger’s CPA and qualified intermediary before an offer is submitted.

    That financial threshold is only the beginning. A replacement property should be tested against the income it can reasonably produce, the capital it will require, and the market that will eventually absorb it. This is where generic online estimates become particularly dangerous.

    A Lexington fourplex near the university may appear straightforward, yet its value can turn on tenant turnover, parking, unit condition, lease timing, and whether rents are truly at market. A Richmond single-family rental may offer easier management and broader resale appeal, but could produce a lower yield than a more operationally intensive asset. A Gorge cabin may generate exceptional seasonal revenue, while carrying higher cleaning, furnishing, road-maintenance, insurance, and booking-volatility costs.

    The right property depends on the exchange investor’s objective. Someone leaving a management-heavy apartment asset may prioritize stable, lower-touch income. Another owner may accept more operating complexity for growth potential. An investor seeking a partial move into land or development property may value long-term appreciation over immediate cash flow. The exchange does not decide that strategy. It merely creates a narrow window in which to execute it.

    Start With the Income That Can Be Verified

    Request actual leases, trailing income and expense statements, utility bills where relevant, tax records, service contracts, and records of major repairs. For short-term rentals, review platform statements, booking pace, cancellation patterns, owner blocks, cleaning costs, occupancy tax handling, and the age of the revenue data. A single exceptional season is not an underwriting model.

    Separate cosmetic upside from required capital expenditure. New paint and light fixtures are one category. A failing retaining wall, aging HVAC system, roof near the end of its life, undersized electrical service, or unpermitted addition is another. The exchange deadline can make buyers overly tolerant of defects that would otherwise end negotiations. That is usually the moment to become more disciplined, not less.

    Location Risk Is an Operating Cost

    Kentucky property requires localized due diligence. In rural and edge-of-market areas, sewer first, always. If the property is served by septic, confirm system type, permit history, inspection results, capacity, and the location of reserve areas before assuming a renovation, additional bedroom, or expanded rental use is possible.

    Water, road access, drainage, flood exposure, easements, and internet service also deserve early review. A beautiful acreage tract can be constrained by a shared drive, limited road frontage, steep topography, or a utility arrangement that changes the development equation. In karst areas, drainage and foundation observations warrant particular care. For land, farms, and cabins, mineral rights, timber rights, hunting leases, boundary questions, and access rights may carry more weight than a polished aerial photograph suggests.

    For a property intended for short-term rental use, verify applicable county or city rules, deed restrictions, insurance availability, parking, emergency access, and neighbor context. A high nightly-rate projection cannot overcome an access road that guests avoid in winter or an insurance premium that changes the operating margin.

    Financing and Contract Terms Need Room for Reality

    A replacement-property offer should reflect the exchange timeline without sacrificing the ability to investigate. The seller may welcome a well-capitalized 1031 buyer, especially if the buyer can move quickly. But speed is not the same as removing contingencies blindly.

    Use a financing structure that matches the asset and the deadline. Conventional residential financing, commercial financing, portfolio lending, seller financing, and cash each carry different appraisal, underwriting, and closing risks. If the replacement requires rehabilitation, confirm whether the lender will finance the property in its present condition and whether post-closing repairs fit the investor’s plan.

    For some exchanges, a build-to-suit or improvement exchange may be appropriate, but it requires advance structure and specialized guidance. It is not a solution to invent after a standard purchase contract is signed. Similarly, a Delaware statutory trust may suit an investor seeking passive ownership, but it presents its own sponsor, liquidity, fee, and concentration considerations. These are tax and securities questions as much as real estate questions.

    Keep the contract path clean. Confirm that the seller can deliver marketable title, identify who will handle known repair items, and understand whether any lease, tenant, vendor, or management agreement survives closing. A property with good projected yield can still be the wrong acquisition if its title, access, operating agreements, or condition cannot be resolved before the exchange period expires.

    Build a Replacement Bench Before You Sell

    The strongest 1031 buyers do not wait for closing to begin searching. They create a replacement bench: a short list of on-market candidates, off-market possibilities, and property types that meet the investment mandate. They also know what they will not buy.

    That written standard may include a target price range, minimum debt-service coverage, acceptable repair budget, preferred geography, tenant profile, expected hold period, and tolerance for management intensity. It should also identify deal breakers such as septic uncertainty, steep-access roads, unverified short-term-rental revenue, flood risk, or dependence on a single tenant.

    For an out-of-area investor, local interpretation matters as much as access to listings. The question is not merely whether a property is available in Lexington, Richmond, Berea, Winchester, or the Gorge. It is whether its pricing, condition, and operating assumptions are credible for that specific submarket. Marcos Gil Realty approaches that work with valuation in writing and property-level diligence rather than a broad search portal and a hopeful projection.

    A 1031 exchange is most useful when the replacement property improves the owner’s position beyond tax deferral. Buy the asset you would still want to own if the tax deadline were not staring at the calendar. That standard tends to produce better decisions, quieter closings, and a portfolio that remains defensible long after the exchange documents are filed.

  • Buying Land With Septic in Kentucky: What to Check

    Buying Land With Septic in Kentucky: What to Check

    A beautiful tract can fail the most basic test of ownership: whether it can legally and reliably handle wastewater. That is the central risk in buying land with septic Kentucky buyers should understand before they become attached to the view, the creek frontage, or the promise of privacy. In Central and Eastern Kentucky, usable acreage is not the same thing as buildable acreage, and buildable acreage is not automatically septic-suitable acreage.

    The disciplined order is simple: sewer first, always. If public sewer is available, confirm the actual connection point, capacity, extension requirements, tap fees, and whether the property can physically reach it. If it is not, septic due diligence needs to happen early enough to influence price, contract terms, and the decision to proceed at all.

    Why Septic Changes a Kentucky Land Purchase

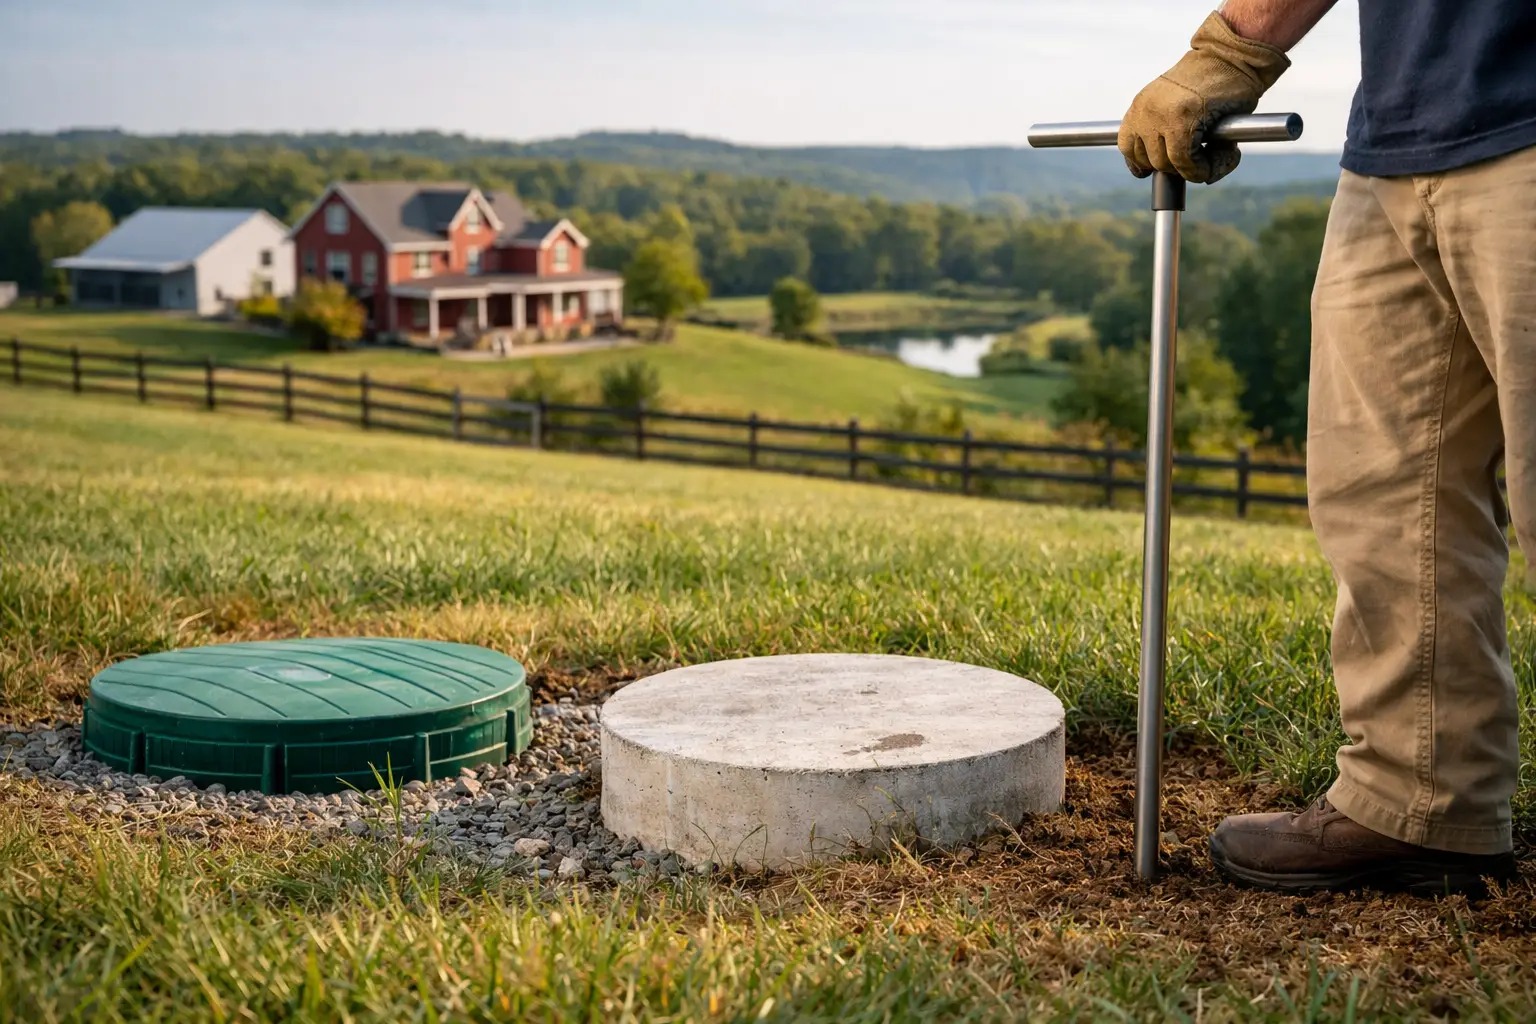
    A septic system is not just a tank buried in the yard. It is a permitted wastewater treatment system tied to the property’s soils, slope, drainage, proposed home size, water source, and site plan. A parcel can have ten, fifty, or one hundred acres and still offer only a narrow area where a residence and onsite sewage system can be approved.

    That distinction matters across the Lexington-Richmond-Red River Gorge corridor. Rolling terrain, shallow bedrock, wet-weather drainage, restrictive soil conditions, flood-prone ground, and irregularly shaped tracts can all limit the feasible building envelope. On a wooded Gorge-area parcel, the obvious cabin site may not be the site that works for septic. On a farm outside Richmond, the pasture nearest the road may be ideal for access but unsuitable for a leach field.

    A listing phrase such as “septic approved,” “perc tested,” or “septic on site” should begin a document request, not end the analysis. Ask what was approved, when, for how many bedrooms, for which exact location, and whether the approval remains usable for the home you intend to build.

    Start With Sewer Availability and the Legal Record

    Before discussing tank condition or soil tests, establish whether the property is served by public sewer, can be served by public sewer, or must rely on an onsite system. An agent, seller, or neighbor may use “sewer nearby” loosely. Nearby is not connected, and a line across the road does not necessarily mean a practical or affordable connection.

    For an existing septic system, request the septic permit, site evaluation, installation record or as-built drawing if available, pumping and maintenance receipts, repair invoices, and any records of prior failure. These documents should be sourced, dated, and interpreted. A permit from decades ago can still be useful, but it does not confirm present performance or establish that an addition, guest house, finished basement bedroom, or short-term rental use will be supported.

    For vacant land, ask the local health department what records exist for the parcel and whether a new site evaluation will be required. Kentucky’s onsite sewage process is administered locally, so procedures and record availability can vary by county. A soil and site evaluation – often casually called a perc test – is not something to assume transfers from one lot configuration or building plan to another.

    If the seller cannot produce a permit or clear record, that is not automatically a deal-breaker. It is, however, a reason to price the uncertainty correctly and make the offer contingent on satisfactory septic and site approval.

    Existing Septic Systems Need More Than a Walkover

    A green lawn, no odor, and drains that appear to work during a brief showing are not evidence that a septic system is sound. Many systems reveal trouble only under sustained use, heavy rain, or when a tank is overdue for pumping.

    Hire a qualified septic professional to inspect the system during the due-diligence period. The inspection should identify the tank type and approximate size, assess accessible components, locate the drainfield where possible, evaluate signs of surfacing or backup, and review whether the system appears appropriately matched to the home. A separate plumbing inspection may also be warranted, particularly for older rural homes, cabins, and properties with additions.

    The most consequential question is often bedroom count. Septic approvals are generally tied to design flow, commonly connected to the approved number of bedrooms rather than the number of people currently occupying a home. If a three-bedroom property is marketed with a fourth sleeping room, bunk room, or finished lower level, buyers should not assume the septic approval supports that use.

    This deserves special attention for Red River Gorge cabins and investment properties. A property that performs acceptably as a lightly used second home may face materially different demand as a high-turnover short-term rental. Rental income projections should never be built on occupancy assumptions that outrun wastewater capacity.

    The Reserve Area Is Part of the Property

    Where a replacement or reserve area is required, it is not spare land to casually repurpose. It may be essential to the property’s long-term usability if the original drainfield fails. Parking pads, barns, pools, retaining walls, driveways, heavy equipment, and deep-rooted landscaping can all create problems when placed over septic components or an intended reserve area.

    This is where survey review and site planning become practical, not academic. Confirm the boundaries, easements, proposed driveway, utility route, well location if applicable, house footprint, drainfield, and reserve area together. On a narrow or steep parcel, each decision competes for the same usable ground.

    Buyers also need to understand that a future lot split can change the equation. A tract that works as one homesite may not support a second residence, family compound, or additional cabin. If development potential is part of the value proposition, investigate septic feasibility before assigning a premium to hypothetical density.

    Wells, Water, Drainage, and Topography Belong in the Same Review

    Septic is one part of a larger site system. If the property will use a private well, the well and septic layout must work together with required separation distances and the actual terrain. The proposed well location should not be treated as a pin dropped anywhere on a survey.

    Water management matters just as much. Walk the parcel after rain if possible. Look for drainage swales, wet spots, springs, sinkholes, pond overflow paths, and evidence of standing water. In parts of Eastern Kentucky, slope and rock can turn an apparently straightforward homesite into a much more engineered project. In low-lying areas, flood conditions and saturated soils can make conventional expectations unrealistic.

    The trade-off is not always a rejection of the property. Some sites can be improved with an alternative system, grading, or a more carefully located home. But those solutions can be expensive, may require specialized design and approval, and should be understood before the inspection period expires. “It can probably be worked out” is not a budget.

    Write the Contract Around the Real Risk

    For land or rural homes, a generic inspection contingency can be too vague. The purchase agreement should give the buyer enough time and authority to obtain septic records, inspect an existing system, conduct any needed soil or site evaluation, confirm access to utilities, and evaluate well and drainage conditions.

    The exact structure depends on the property. A buyer purchasing an older farmhouse may need a septic inspection, pumping history, and a repair estimate. A buyer purchasing raw acreage may need written confirmation that a homesite and onsite sewage system can be approved for the intended use. A buyer acquiring land for a cabin portfolio may need clarity on how many separate systems and dwellings are realistically permissible.

    Keep the economics visible. If the system is near the end of its useful life, that does not necessarily mean walk away. It may mean adjusting the purchase price, requesting a credit where appropriate, reserving funds, or choosing a property whose location and land quality justify the future capital expense. What matters is knowing whether the issue is a manageable improvement or a constraint that limits the entire plan.

    A Better Way to Look at Rural Value

    Kentucky land is often marketed through emotion: the ridge view, the horse pasture, the quiet road, the proximity to Lexington or the Gorge. Those qualities have real value. Yet the infrastructure underneath them determines whether that value can be used, financed, insured, rented, or resold without friction.

    The best rural purchase is not necessarily the parcel with the most acreage or the newest-looking cabin. It is the one where access, water, wastewater, boundaries, terrain, and intended use align on paper as well as they do from the road. Ask the septic questions early, retain the right professionals, and let the answers shape the offer before the land starts shaping your expectations.

  • Central Kentucky Market Pulse — Week of August 15, 2026

    One agent, one weekly read on the corridor — and this week the numbers come straight from the Bluegrass REALTORS® MLS rather than a third-party estimate. The short version: both Lexington and Richmond are still seller’s markets, prices are up year over year in both, and the real difference between them is not price. It is speed.

    Lexington and Richmond, side by side

    MeasureLexington (Fayette Co.)Richmond & Berea (Madison Co.)
    Active listings645337
    Months of supply2.1 months3.1 months
    Average days on market23.950.1
    Median sold price, July$372,500$322,000
    Year-over-year change+5.7%+4.2%
    Median asking price$414,900$330,500
    New listings, last 7 days7627

    Source: Bluegrass REALTORS® MLS via FlexMLS. Monthly statistics reflect the last complete month, July 2026; new-listing counts are as of August 15, 2026. Months of supply is calculated as active inventory divided by the trailing twelve-month average of closed sales. Deemed reliable but not guaranteed.

    What this means if you are buying

    In Lexington, you are competing on the clock. An average of 23.9 days on market means a well-priced home in a desirable pocket is spoken for inside of a month — often inside of a week. With 2.1 months of supply, you need financing lined up and a decision process that can move in days, not weekends. Browsing without pre-approval in this market is how buyers lose three houses before they get serious.

    In Richmond, you have room to think. At 50.1 days — more than double Lexington’s pace — and 3.1 months of supply, Madison County gives buyers something Fayette County does not: time to walk a property twice, get an inspection scheduled without panic, and negotiate on more than price. And the entry point is roughly $50,500 lower at the median. If you are searching homes for sale in Richmond KY, that combination is the whole argument for looking south of Fayette County.

    What this means if you are selling

    Both markets moved up year over year — Lexington’s median sold price is up 5.7% and Madison County’s up 4.2%. But notice the gap between asking and selling in each market. Lexington’s median asking price is $414,900 against a $372,500 median sale; Madison County’s spread is narrower. Inventory that lingers is usually inventory that was priced against the asking column instead of the selling column. A valuation grounded in what actually closed is worth more than an optimistic list price you will spend two months walking back.

    One more signal worth watching: Lexington’s active inventory bottomed at 531 listings in March and has climbed to 645 since — a 21.5% increase off the floor. That is normal summer seasonality, not a downturn. But it does mean sellers who list in the fall will face more competition than sellers who listed in the spring did.

    Common Questions

    Is the Central Kentucky market slowing down?

    Not by these numbers. Both counties show year-over-year price gains and both remain under four months of supply, which is seller-favorable territory. Inventory is up from its March low in Lexington, but it is still slightly below where it stood a year ago. That is a market normalizing from extreme tightness, not one turning over.

    Why is Richmond so much slower than Lexington if prices are rising in both?

    Different buyer pools. Fayette County draws a large relocation and university-driven demand base concentrated in a compact geography, so well-priced homes clear fast. Madison County covers more ground with a more local buyer base. Slower is not weaker — Madison County still closed 155 sales in July against 337 active listings.

    How is months of supply calculated?

    Active listings divided by the trailing twelve-month average of monthly closed sales. We use a twelve-month average rather than the current month because summer months flatter the ratio and would make both markets look tighter than they are.

    Thinking about a move anywhere on the corridor? Selling, buying, or you just want the numbers for your street — call or text.

    By Marcos Gil, REALTOR® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209.

  • Is a Red River Gorge Cabin Investment Worth It?

    Is a Red River Gorge Cabin Investment Worth It?

    A Red River Gorge cabin investment is rarely won or lost on the nightly rate shown in an online search. It is won in the less glamorous details: whether guests can reach the property after a hard rain, whether the septic system matches the sleeping capacity being marketed, whether insurance is available at a workable premium, and whether the gross revenue estimate still makes sense after management, maintenance, utilities, and reserves.

    The Gorge has genuine demand. Climbers, hikers, wedding guests, families, and Lexington-area buyers seeking a quick reset continue to support a distinctive lodging market. But it is not a uniform market, and a cabin with a pretty view is not automatically a sound investment. The better question is whether a specific property can operate reliably, legally, and profitably in its exact location.

    What Makes a Red River Gorge Cabin Investment Different

    Red River Gorge cabins trade on experience. Guests may pay a premium for a hot tub, fire pit, wooded privacy, architectural character, pet-friendly policies, proximity to trailheads, or a view that feels removed from ordinary life. A well-positioned cabin near Slade can attract a different guest than a larger, more secluded property farther into Wolfe, Powell, Lee, Menifee, or Estill County.

    That distinction matters because location affects more than demand. It changes drive times, road maintenance, cellular service, emergency access, trash service, utility reliability, and the practical cost of turning a rental between stays. A property can be technically close to the Gorge yet feel inconvenient to the guest who arrives after dark on an unfamiliar two-lane road.

    Unlike a conventional long-term rental, this asset is an operating business tied to a real property. The buyer is underwriting land, improvements, furnishings, local regulations, guest expectations, and an ongoing maintenance program at the same time. Gross bookings are only one input.

    Start With Revenue, Then Stress-Test It

    A credible income estimate should begin with comparable cabins, not broad regional averages. Compare bedroom count, guest capacity, finish level, amenities, road access, proximity to Slade and major recreation draws, and whether the property has meaningful differentiation. A three-bedroom cabin with a hot tub and polished interiors may compete in a different rate band than a basic three-bedroom on the same road.

    Past booking statements can be useful, but they are not proof of future performance. Ask how the revenue was generated. Was the owner actively managing pricing? Did the property benefit from unusually strong reviews, a recent renovation, or a one-time event cycle? Were owner stays blocked during high-demand weekends? Did the reported figure include cleaning fees or taxes that do not belong in operating revenue?

    A conservative underwriting model should separate gross rental revenue from the money actually available to the owner. Account for management fees, platform fees, cleaning coordination, laundry, consumables, electric, internet, propane, water, septic service, pest control, snow or road work where applicable, repairs, furnishings, insurance, property taxes, and a capital reserve.

    Cabins are hard on systems. Hot tubs need regular attention. HVAC equipment works through Kentucky humidity and winter cold. Decks, stairs, roofs, retaining walls, and gravel drives all require recurring capital. An owner who models only mortgage payment, taxes, and a cleaning fee is not modeling the asset.

    Seasonality Is a Planning Issue, Not a Footnote

    The Gorge has multiple demand drivers, which is an advantage. Climbing and hiking seasons can be strong, weekends carry disproportionate weight, and fall can produce exceptional demand. Still, weekday occupancy and shoulder-season performance often decide whether an investment has sufficient margin.

    Build a monthly model rather than applying one annual occupancy percentage. Then test it against a lower-rate, lower-occupancy case. If the property only works at an optimistic average daily rate and near-perfect weekend conversion, the acquisition price may be too aggressive or the operating plan too thin.

    Sewer First, Always: Utilities and Site Due Diligence

    For rural Kentucky cabins, sewer first, always. Many properties rely on septic systems, and the distinction between bedroom count, septic capacity, and advertised guest count can be consequential. A listing may describe bunks, lofts, or sleeping rooms that do not align with the system’s permitted design. That creates operational, regulatory, and resale risk.

    Obtain the available septic records, identify the system type and location, and understand its service history. Ask where replacement area may exist if the current system fails. An inspection should go beyond a casual look at the yard. Buyers should also verify the water source, water pressure, filtration needs, well records if applicable, and any shared-water or private-road agreements.

    Roads deserve the same seriousness. Who owns and maintains the approach? Is there a recorded easement? Can a standard guest vehicle reach the cabin in wet weather? Will a propane truck, trash hauler, cleaner, emergency vehicle, or repair contractor have practical access? A steep, narrow drive can be part of the cabin experience, but it may also narrow the guest pool and raise operating costs.

    The property condition review should include roof age, drainage, foundation movement, deck structure, retaining walls, tree risk, moisture control, HVAC, electrical capacity, internet options, and cell coverage. In a remote setting, a small deferred-maintenance issue can become expensive because service calls take longer and contractor availability can be limited.

    Regulations, Restrictions, and the Cost of Being Wrong

    Short-term rental rules are local and can change. County requirements, building-code considerations, occupancy standards, lodging taxes, business licensing, deed restrictions, homeowners association rules, and insurance requirements should be verified for the specific parcel before a buyer removes contingencies. Do not rely on a seller’s statement that a cabin has “always been rented.” Prior use is not a complete legal or operational analysis.

    If the property sits in a development, read every recorded restriction and amendment. Some communities regulate rental duration, parking, signage, noise, exterior changes, or amenity use. Others place maintenance obligations on owners that affect annual expenses. The same is true for private roads and shared drives: the agreement may be more important than the view.

    Insurance deserves early attention. Wood construction, remote fire response, steep drives, water features, hot tubs, and rental use can affect availability, deductibles, exclusions, and premiums. Request quotes before finalizing the financial model, not after inspection. A low initial insurance estimate can make an otherwise marginal deal appear viable.

    Buy the Right Cabin, Not the Loudest Listing

    The strongest investment candidates generally have a clear guest proposition and fewer hidden operating problems. That does not always mean the newest or largest cabin. A modest property with excellent access, reliable systems, a well-designed outdoor area, and a manageable maintenance profile may outperform a more dramatic cabin that is difficult to reach and expensive to keep guest-ready.

    Consider who the intended guest is. A two-person retreat can command a healthy rate with privacy, design, and a quality hot tub. A family-oriented cabin may need usable bedrooms, safe outdoor space, durable furnishings, and dependable internet. A group property requires adequate parking, septic capacity, noise management, and enough common space that the sleeping count feels credible rather than crowded.

    This is also where buyer goals matter. Some owners want personal use and will accept lower yield in exchange for protected weekends. Others need income consistency, a 1031 exchange replacement property, or a business that can support professional management. Neither approach is wrong, but the underwriting should match the purpose. A personal retreat should not be priced as though every premium weekend will remain available for rental.

    An Exit Strategy Should Be Present at Purchase

    Cabin values can be influenced by lifestyle demand, construction quality, acreage, views, road conditions, and income history. But short-term rental revenue is not guaranteed to transfer neatly to the next owner. A buyer should be able to explain the property’s appeal without relying entirely on one year of bookings.

    Think through the likely resale audience. Is the next buyer an investor, a second-home owner, a local household, or someone seeking land and privacy? A cabin with broad appeal, documented improvements, clean records, and well-maintained systems is easier to position when market conditions change. Keep invoices, permits, septic records, service logs, and before-and-after documentation. In a rural transaction, orderly records can materially improve buyer confidence.

    A disciplined Red River Gorge cabin purchase is not about finding a fantasy number on a revenue calculator. It is about paying the right price for a property whose access, systems, regulations, guest appeal, and operating costs have been examined in writing. The cabin should still make sense after the view wears off and the first repair invoice arrives.