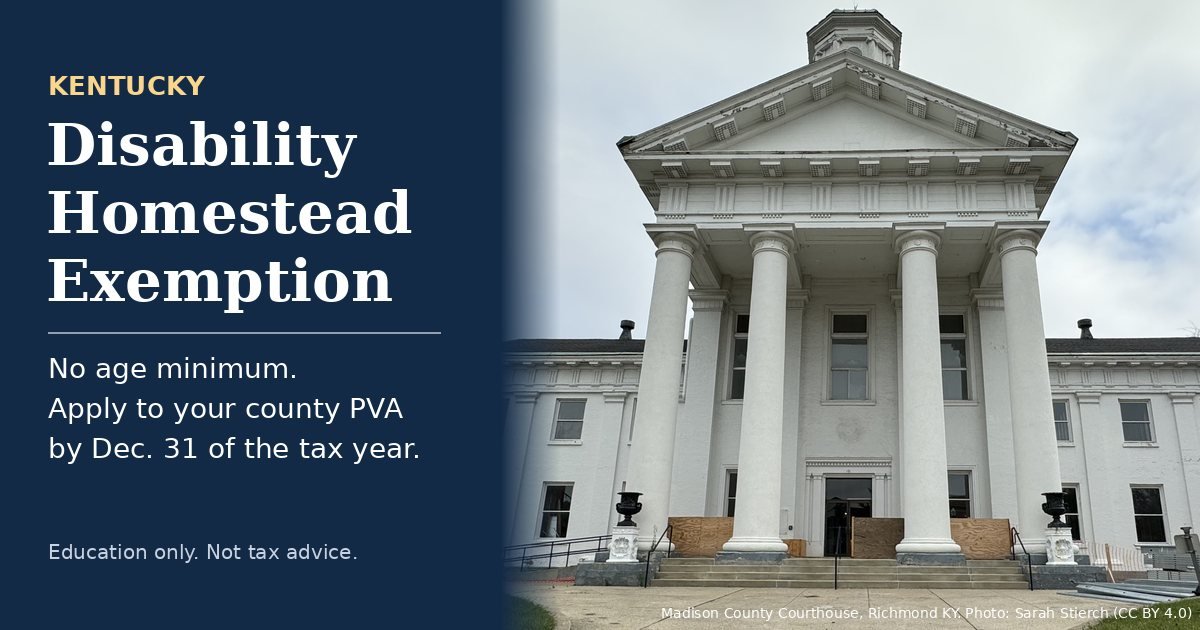
Photo: Madison County Courthouse, Richmond, KY by Sarah Stierch (CC BY 4.0), via Wikimedia Commons. Modified: cropped; title panel and text added.
Gorge Region · Property Taxes
The Kentucky disability homestead exemption is the same $49,100 deduction most people know as the “over 65” break — but it has no age limit, and the statute defines it far more broadly than the phrase “disability” suggests. You apply to your county Property Valuation Administrator (PVA) by December 31 of the tax year you’re claiming. For the 2026 tax year, that date is December 31, 2026.
Last updated: November 3, 2026
How much is the Kentucky homestead exemption in 2026?
$49,100 of assessed value, for both the 2025 and 2026 tax periods. It is deducted from the assessment before the tax rate is applied.
The Kentucky Department of Revenue set the figure on November 14, 2024, and published it as the 2025-2026 homestead exemption. It is a $2,750 increase over the $46,350 that applied in 2023 and 2024. The same release reports that in the 2023 tax year the exemption produced roughly $293 million in state and local property tax savings for more than 474,000 elderly or disabled Kentuckians.
The two-year cycle is not administrative habit. KRS 132.810(2)(e) says the $6,500 figure written into Section 170 of the Kentucky Constitution “shall be construed to mean sixty-five hundred dollars ($6,500) in terms of the purchasing power of the dollar in 1972,” and that every two years thereafter, if the federal cost-of-living index has moved as much as one percent, the maximum exemption is adjusted accordingly. The number changes because 1972 recedes, not because the legislature revisits it.
The Department of Revenue recalculates the amount every two years. As of November 3, 2026, it had not yet published the 2027–2028 figure, so check the DOR homestead page before you rely on a number for 2027.
Who qualifies under the disability route?
Anyone classified as totally disabled by a United States government agency or by any retirement system, inside or outside Kentucky, on January 1 of the application year.
That phrasing, from KRS 132.810(2)(a), is wider than most homeowners assume. The Department of Revenue’s own summary puts it as “classified as totally disabled by any public or private retirement system.” A private pension plan’s total-disability classification counts. A classification from another state’s retirement system counts. The statute does not restrict the route to Social Security or to veterans, and it does not impose a minimum age — the age-65 test and the disability test are alternatives, not a pair.
Two conditions travel with it. Subsection (2)(c) requires that the applicant actually received disability payments under the disability and maintained the classification for the entirety of the taxation period — a classification that lapsed mid-year is a problem. And the property has to be owned, occupied and maintained as the applicant’s personal residence on the January 1 assessment date.
Under 65, the default is to reapply every year, but the statute names exceptions.
Do you have to reapply every year?
Under 65 and totally disabled: yes, annually — unless you fall inside one of four categories the statute names, which file once and document the disability.
KRS 132.810(2)(d) sets the default as annual reapplication, then carves out the exceptions in subparagraph 2. The exempt categories are a service-connected totally disabled veteran of the United States Armed Forces, and a totally and permanently disabled individual found disabled under the applicable rules of the Social Security Administration, the applicable rules of the Kentucky Retirement Systems, or any other provision of the Kentucky Revised Statutes. Those applicants “shall document the disability at the time of application” and are not required to apply annually.
| Situation | Reapply annually? |
|---|---|
| Age 65 or older | No — the exemption runs with the qualifying residence |
| Service-connected totally disabled veteran | No — document at first application |
| Total and permanent disability found under SSA rules | No — document at first application |
| Total and permanent disability under Kentucky Retirement Systems or another KRS provision | No — document at first application |
| Any other total-disability classification, under 65 | Yes — every year |
What kinds of homes and ownership qualify?
More than a deeded single-family house. A manufactured home counts, and under KRS 132.810(2)(f) the property may be held “by legal or equitable title, by the entireties, jointly, in common, as a condominium, or indirectly by the stock ownership or membership representing the owner’s or member’s proprietary interest in a corporation owning a fee or a leasehold initially in excess of ninety-eight (98) years.”
This matters in Lee, Estill, Powell and Wolfe County more than it does in a subdivision market. KRS 132.810(2)(g) states that a mobile home, a recreational vehicle when classified as real property under KRS 132.751, or a manufactured house qualifies as a residential unit for homestead purposes. Subsection (2)(f) allows the real property to be held by legal or equitable title, by the entireties, jointly, in common, or as a condominium, and limits the exemption to the value of the real property assessable to that owner. Subsection (2)(e) caps it at one exemption per residential unit — a household where one spouse is over 65 and the other is totally disabled gets one exemption, not two, and so does a house with several residents over 65.
When and where to apply
The application goes to your county Property Valuation Administrator, not to Frankfort. KRS 132.810(1) requires you to file with the PVA on the Department of Revenue’s form. That form, 62A350 (Application for Exemption Under the Homestead/Disability Amendment), says it must be submitted by December 31 of the year the exemption is sought, and that you must own, occupy and maintain the home as of January 1 of that year. On the disability route, the form also asks for your disability verification by December 31 of your first year of eligibility. If you qualify after you’ve already paid that year’s bill, KRS 132.810(4)(d) provides a refund of the tax on the exempt amount.
Two timing issues are easy to miss. The first is a transfer: when title to exempted property changes hands, the exemption does not follow the house to the new owner by itself — the new owner is a new applicant, and the year of a purchase is exactly the year the paperwork gets forgotten in the move. The second is the January 1 ownership date. If you close on a home any time after January 1, you weren’t its owner-occupant on that year’s assessment date, so your first homestead year on the new home is the following tax year. A buyer who closes in March applies for the next year, not the current one. If you’re buying or selling in the Gorge counties, ask the PVA directly which tax year your application will land in. Our note on the Kentucky homestead exemption in Lee, Estill and Powell County works through what the deduction is worth against local rates, and assessment versus rate in Lee County explains which half of the bill the exemption actually touches. For the wider picture, see Kentucky property taxes, explained.
Can I claim both the age-65 and the disability exemption?
No. KRS 132.810(2)(e) allows only one exemption per residential unit “even though the resident may be sixty-five (65) years of age and also totally disabled, and regardless of the number of residents sixty-five (65) years of age or older occupying the unit.”
Does a private pension’s disability classification count?
The statute says “totally disabled under a program authorized or administered by an agency of the United States government or by any retirement system either within or without the Commonwealth of Kentucky,” and the Department of Revenue describes it as any public or private retirement system. Take the classification letter to the PVA and let that office apply the test to your documents.
Does the exemption lower the assessment or the tax rate?
Neither, exactly. It deducts $49,100 from the assessed value before the rate is applied, so the saving equals $49,100 multiplied by the combined rate on that property, and it is capped by the assessment itself.
General information about Kentucky property tax statutes, not tax or legal advice. Eligibility is determined by your county Property Valuation Administrator on the documents you file.
By Marcos Gil, REALTOR® — Keller Williams Commonwealth · KY Real Estate License No. 296259 · Call or text (859) 310-1209.
Leave a Reply